Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
Copper and cobalt are attracting attention, but the real question is who controls them
In the Democratic Republic of the Congo, minerals are about more than export figures. They also determine the influence of companies, the state’s ability to negotiate and the country’s place in global supply chains. It is against this backdrop that a major commodities trader is strengthening its foothold in Kinshasa and the Congolese copper belt in the south-east.
The appointment of a Congolese executive to lead the group’s activities in the DRC is no trivial matter. It comes as Kinshasa seeks to capture more value from copper, cobalt and so-called critical minerals, while industrial companies seek to secure their flows, logistics and relations with public authorities.
A country at the heart of the energy transition, and a sector being reshaped
The DRC remains a nerve centre of the global battery metals market. In the first quarter of 2025, the country produced 817.639,17 tonnes of copper and 42.855,31 tonnes of cobalt, according to official statistics from the Technical Unit for Coordination and Planning of Mining, which is attached to the Ministry of Mines. These volumes underscore the scale of a sector in which raw exports, local processing and traceability remain sensitive issues.
In Kinshasa, the policy line is clear: the government wants mining resources to contribute more to the national economy, rather than only to factories located outside the country. In this context, relations between private companies, Gécamines, the General Cobalt Company and the mining authorities carry considerable weight. Gécamines, the long-standing state-owned company, remains a pivotal player in the sector’s structure.
This reshaping extends beyond the DRC. It also involves Angola, through the Lobito Corridor, and, more broadly, competition between Asian, European and North American markets for access to strategic minerals. Trafigura said in May 2026 that its partnership with EGC and EVelution Energy was intended to make use of this rail corridor linking Angola’s port of Lobito to the Congolese mining interior.
What the announced appointment changes
According to the group’s statement, Hervé Otschudi is to lead the strategic development of Trafigura’s activities in the DRC, including relations with public authorities and institutions, as well as energy, metals and minerals trading operations and associated logistics. The choice of a Congolese executive who previously worked at Gécamines signals proximity to the sector’s local networks.
For the company, there are two objectives. One is to secure a lasting presence in a country where competition for mining assets and logistics outlets is intensifying. The other is to show that it can operate within a more structured framework, with national counterparts, traceability rules and heightened compliance expectations. Trafigura says it is already working with EGC on a direct supply chain for Congolese cobalt hydroxide to the United States, subject to final agreements.
For the Congolese state, the stakes are broader. A more organised presence by a global operator could facilitate marketing, improve some logistics flows and open up new outlets. But it does not resolve the central question: who captures the added value, from the mine to the arrival of the shipments? As long as local processing remains limited, the balance of power will continue to favour operators able to finance, transport, negotiate and refinance shipments on a large scale.
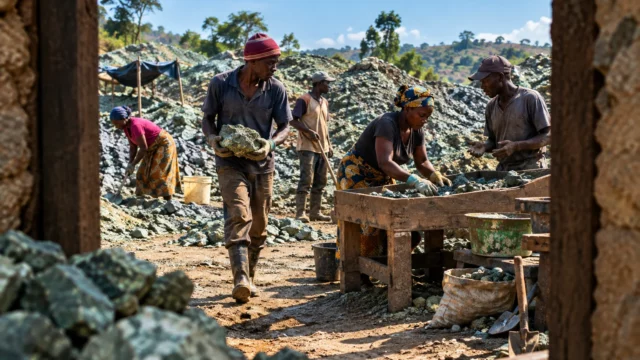
The benefits will not be the same for everyone. In the major mining areas of Lualaba and Haut-Katanga, industrial groups and trading companies are seeking predictability. In artisanal mining, traceability and oversight remain essential, but they must also avoid abruptly excluding thousands of households that depend on this activity. Formalisation only makes sense if it reduces risks, improves incomes and limits opaque practices.
A test for Congolese mining diplomacy
The DRC is no longer negotiating solely in terms of extraction volumes. It is now negotiating in terms of economic sovereignty, local processing, certification and market access. This is precisely where the significance of this appointment lies. An executive director based in the DRC will have to convince the authorities, industrial partners and transport operators alike that value can move without disappearing into the sector’s usual grey areas.
The timing is revealing. In 2026, the critical minerals market remains tight as the United States, Europe and Asia seek to secure their supplies. The DRC, for its part, wants to avoid being merely a source of raw materials. It wants a greater say in the governance of its own resources. Hervé Otschudi’s announced appointment should therefore be seen as another element of this strategy: bringing international trading closer to the Congolese decision-making centre without shifting real power away from Kinshasa.
The next steps will hinge on very practical issues: final commercial agreements, the Lobito Corridor logistics chain, EGC’s mandate and the state’s ability to impose stable rules on operators active in its territory. In the copper-cobalt sector, every contractual advance matters. So does every delay.