Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
In Kolwezi, a legal battle that reaches beyond the mines
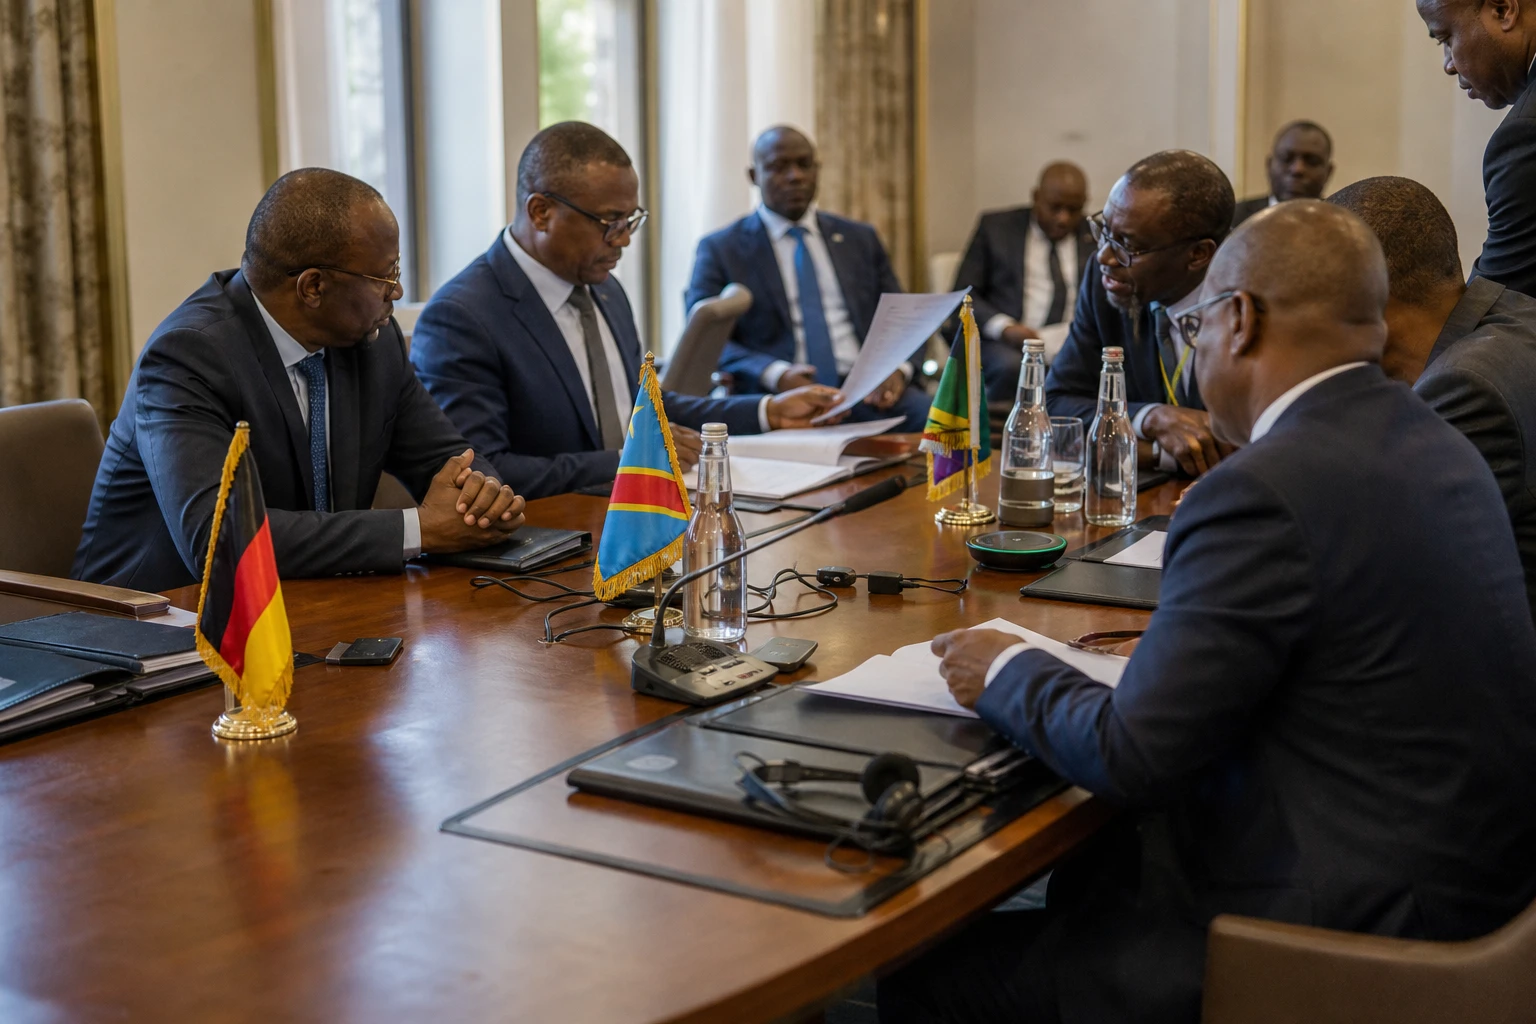
In Congolese copper and cobalt, the question is no longer just how to produce more. It is also about who actually works in the value chain, and who captures its revenues. In the Democratic Republic of the Congo, the Regulatory Authority for Subcontracting in the Private Sector has raised the stakes by targeting two industry heavyweights, Kamoto Copper Company and Mutanda Mining, both subsidiaries of Glencore, over contracts deemed non-compliant.
The issue touches on a sensitive point in the Congolese economy: mining subcontracting. Congolese law reserves this activity for companies with majority Congolese capital, in order to keep more value circulating in the country and support the emergence of a local business sector. The ARSP, headquartered in Kinshasa, is responsible for enforcing the rules.
What the decision says
Decision No. 020/ARSP/DG/2026, dated 11 September 2026, orders KCC and MUMI to terminate contracts currently being performed with ineligible subcontractors and remove them from their supplier lists. The two companies also have 30 days to submit a corrective plan detailing the companies concerned, the reasons for termination and the measures planned to open up more contracts to eligible operators.
An inspection carried out in July revealed significant discrepancies. At Kamoto Copper Company, documents reviewed by the regulator listed 1,427 declared suppliers, around 950 of which did not meet the eligibility criteria. At Mutanda Mining, nearly 40% of the approximately 1,300 suppliers recorded were deemed non-compliant. In total, the measure therefore affects around 1,540 companies, according to figures corroborated by a second local publication.
The legal framework is clear. The 2021 ministerial decree requires, among other things, that eligible companies be registered, have a majority Congolese workforce and comply with the conditions set out in the 2017 law. The same framework provides for penalties in cases of violation, including fines, temporary closure and, in some cases, the nullity of the subcontracting agreement.
Why the case matters to Congolese businesses
For small and medium-sized Congolese businesses, the stakes are tangible. Subcontracting opportunities in the mining sector are not limited to a handful of ancillary contracts. They cover handling, maintenance, logistics, security, civil engineering works and specialised services that feed into the entire industrial ecosystem of Lualaba and Haut-Katanga. When these contracts go to ineligible operators, some formal jobs, technical training and local cash flow disappear with them.
This is precisely the rationale the ARSP champions. Its mandate is to ensure that companies with majority Congolese capital gain access to subcontracting markets and share more fully in the benefits of the private sector. The decision against KCC and MUMI shows that the regulator wants to move from awareness-raising to enforcement. It is a signal to clients in the extractive sector, as well as to local suppliers who have for years called for more transparent access to contracts.
This latest development comes amid a broader economic shift towards domestic priorities. In Kinshasa, the authorities are sending increasingly strong signals in favour of local content and economic sovereignty, while the state seeks to regulate major contracts in mining, infrastructure and strategic partnerships more closely. At the same time, the government must preserve the appeal of a mining sector that remains central to public revenues and the country’s exports.
A message to Glencore—and the entire mining sector
The message is aimed at the entire sector, not just Glencore. KCC and MUMI operate in the south-eastern Congolese copper belt, at the heart of a highly sought-after market where international groups, state-owned companies, local subcontractors and provincial authorities intersect. Social and legal compliance is becoming as important as production itself. Glencore describes KCC and MUMI as major assets in the Democratic Republic of the Congo, and in recent months the group has continued to communicate about its operations, volumes and commitments relating to copper and cobalt.
The decision should also be viewed in the context of the balance of power between the state and major extractive companies. For several years, the Congolese administration has sought to impose stricter rules on access to contracts, following recurring criticism of opaque tenders and the limited role of national players. The law already provides for penalties, but their effective application remains a test of credibility for the entire institutional chain, from the ARSP to the competent courts.
On the ground, the impact will depend on how the termination timetable is implemented. If the transition is swift and based on clear criteria, Congolese businesses could win contracts, margins and visibility that they often lack. If it proceeds without support, there is a risk of disrupting operations, particularly in technical services where the availability of qualified operators remains a challenge.
Regional implications for Central Africa and the mining industry
The case resonates beyond the DRC. Across Central Africa, mineral-producing states are trying to better link resource extraction with taxation, local employment and the growth of national businesses. The DRC, a member of SADC and ECCAS, is advancing a clear position: mineral wealth should not merely be extracted from the ground; it should also help build a network of Congolese businesses capable of working with major groups.
For Kinshasa, the challenge now is to make this decision stick. The 30 days given to KCC and MUMI will be an initial test. They will show whether the ARSP intends to remain a regulator in principle or become a lasting instrument for redistributing contracts. At continental level, the case highlights a tension familiar to many African countries: how to enforce local-content rules without undermining production or allowing major contracts to become closed shops.