Algeria
 Egypt
 Libya
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
Another boost for agricultural lending in Morocco
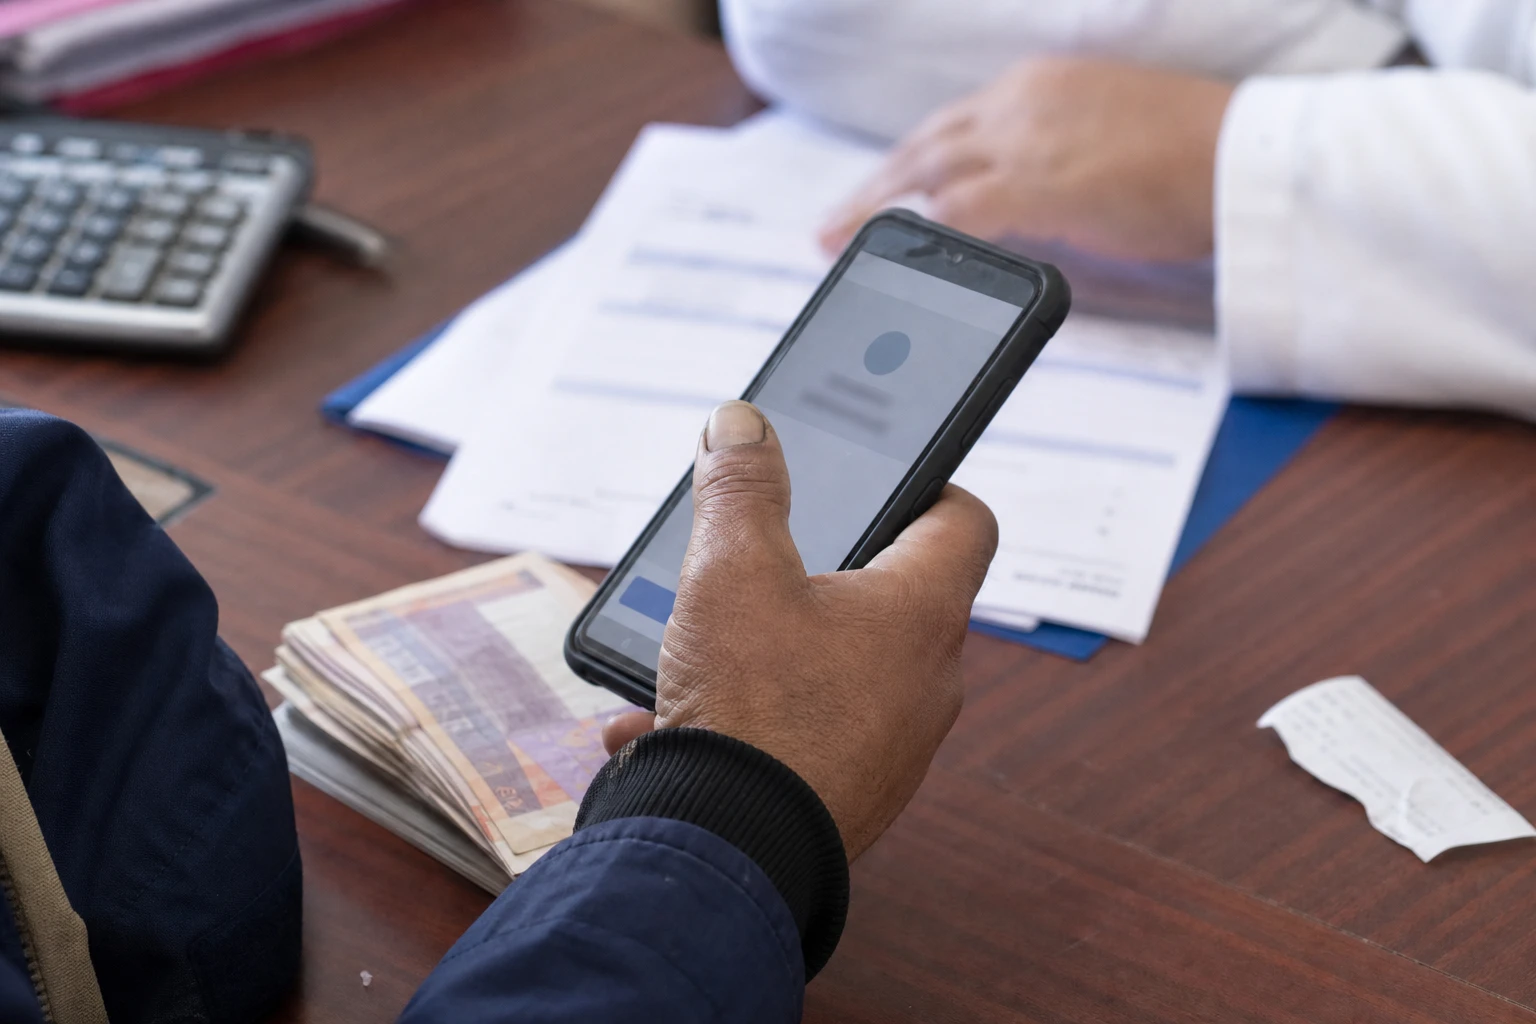
In Morocco’s countryside, financing often remains the weakest link. A good season is not always enough to buy a pump, modernise an orchard, replace equipment or absorb a climate shock. This is where, in very practical terms, the difference lies between an activity that survives and one that grows.
Morocco, and Rabat in particular through its financial and public institutions, has been pushing for several years to modernise its productive economy. Small and medium-sized enterprises, including agricultural businesses, occupy a central place in this landscape. They make up most of the country’s economic fabric, but their access to credit remains more limited than that of large companies.
A guarantee mechanism, not a conventional loan
The new arrangement announced between the International Finance Corporation, the World Bank Group’s private-sector arm, and Crédit du Maroc is not a direct loan. It is a risk-sharing facility. Put simply, the international institution covers part of the potential losses on a loan portfolio, encouraging the bank to lend more to clients considered harder to finance.
According to the published details, the guarantee covers 125 million dirhams, or about $13.5 million, for a loan portfolio of up to 250 million dirhams, about $27 million. The arrangement covers up to 50% of credit risk. It is part of IFC’s Global Small and Medium Enterprises Financing programme, which uses this type of instrument to unlock private financing without adding to sovereign debt.
This choice is not insignificant. In its country diagnostic published in 2026, IFC notes that credit remains concentrated among large companies and the least risky sectors, while lending to SMEs accounts for less than 15% of total loans in Morocco. In other words, the problem is not just a lack of money in the system. It is also how risk is shared between banks, guarantors and investors.
Crédit du Maroc strengthens its agricultural strategy
Crédit du Maroc is not entering this area for the first time. The bank, headquartered in Casablanca, has already worked with IFC. In February 2024, the two institutions announced a $100 million facility for SMEs, women’s entrepreneurship and green projects, including a component for climate-smart agriculture. In 2025, the banking group confirmed a risk-sharing agreement targeting farmers and SMEs in the agricultural sector.
The bank also says it wants to make agriculture and agrifood a strategic focus. It has a department dedicated to this segment and already offers specific products for farming seasons, stocks and operating needs. The new mechanism is therefore intended to support an existing strategy, but on a more structured scale and with risk-sharing arrangements strengthened.
The facility also includes advisory support. This matters as much as the guarantee itself. Agricultural lending requires banks to have teams able to assess seasonal income, crop cycles, climate risks and the creditworthiness of farms that may have limited access to banking services. IFC therefore intends to help Crédit du Maroc strengthen its internal capabilities while guiding it towards responsible finance practices.
What this means for rural SMEs
For a Moroccan agricultural SME, the issue is straightforward: obtaining a loan on manageable terms and on a schedule that fits the seasons. A greenhouse, a packing facility, a drip irrigation system or a refrigerated truck cannot be financed like ordinary working capital. Without sufficient collateral, many applications remain blocked, especially in segments more exposed to volatile yields and prices.
The mechanism also benefits the value chain, not just farmers. When a bank lends more effectively to producers, it also supports input suppliers, transporters, processing facilities and local markets. Agricultural credit then becomes a means of driving economic activity between rural areas, secondary cities and agro-industrial hubs.
Morocco also has a broader strategic interest. Its agriculture remains exposed to water stress, climate variability and trade-offs over water use. IFC has already highlighted the importance of irrigation technologies and more water-efficient solutions in other projects in Morocco. In this context, providing more finance to agricultural SMEs does not simply mean lending more. It also means directing investment towards equipment that protects future productivity.
Significance beyond Morocco
The initiative extends beyond the national context. Across North Africa, banks and public institutions are increasingly seeking to develop risk-sharing mechanisms to channel private savings towards small businesses. Morocco is moving ahead with a non-sovereign structure, closer to market-based approaches, while retaining a public-interest rationale. IFC describes this type of instrument as a way to bring more private capital into segments where perceived risk continues to constrain credit supply.
For Rabat, the initiative also has institutional significance. The country wants to build a deeper financial system capable of serving SMEs, women entrepreneurs and high-value-added activities. For IFC, Morocco remains an important testing ground, with several recent commitments in banking, infrastructure and sustainable finance. The partnership with Crédit du Maroc extends this trajectory, anchoring it more firmly in agriculture, a key sector for employment and territorial balance.
What happens next will depend above all on how quickly the facility is implemented. If the guaranteed portfolio translates into loans actually disbursed, the effect could be tangible for farms, rural SMEs and processing chains. If the arrangement remains too limited, it will still be a useful but modest signal. In a country where SME lending remains below their share of the economy, every mechanism of this kind becomes a practical test of the financial system’s ability to support real production.