Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
An understated but decisive mineral for industry
When zinc prices tighten, it is not merely a matter of stock-market charts. For the Democratic Republic of the Congo, it is also a test of moving up the value chain. The country is no longer content with exporting copper and cobalt. It is seeking to play a greater role in other strategic metals, as zinc regains strength on international markets.
Zinc is used mainly to galvanise steel, protecting metals against corrosion. It is also used in alloys for the automotive industry, electronics and various industrial equipment. As Central Africa seeks to capture more value from its raw materials, this metal matters as much as the minerals better known to the general public.
In Kinshasa and Haut-Katanga alike, the challenge is straightforward: sell more concentrate, but also process it better, collect more tax and connect production more effectively to infrastructure. This is where some of the tangible benefits for the state, Gécamines, subcontractors, transport operators and communities in the mining area will be determined.
Kipushi, the asset changing the scale
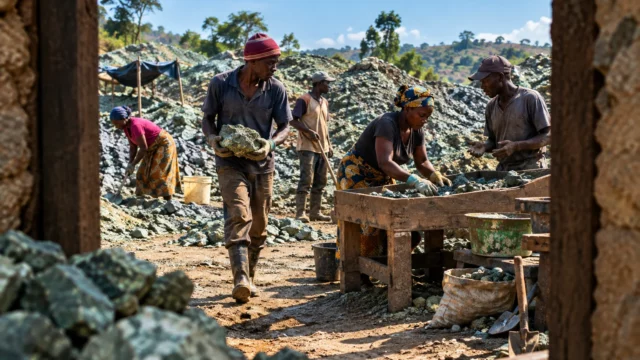
The current momentum in DR Congo’s zinc sector is explained first and foremost by Kipushi, in the country’s south-east, near Lubumbashi and the Zambian border. The mine was officially restarted in November 2024 after decades of inactivity, as part of a joint venture between Gécamines and Ivanhoe Mines. Gécamines holds 38% of the project, while the Canadian group owns 62%.
Industrially, Kipushi has rapidly moved up a scale. Ivanhoe says the plant produced a record 203,168 tonnes of zinc in concentrate in 2025, followed by 65,044 tonnes in the first quarter of 2026, another quarterly record. In the first half of 2026, the mine produced 135,221 tonnes of zinc, according to the company, which also says volumes are rising sharply.
This pace explains why DR Congo’s figures have surged. Operating data published by the project’s stakeholders show that Kipushi now accounts for most of the country’s zinc production. The country has also seen shipments increase, although logistical constraints between the mine and export ports have weighed on unsold stocks, estimated at about 44,000 tonnes of concentrate at the end of the first half of 2026.
The Congolese government is closely monitoring this expansion. For several months, the mining ministry has highlighted the digitisation of geological data, clarification of production flows and regulation of the marketing of commercial mining products. In Congolese terminology, these are tools of economic sovereignty: they help establish what is coming out of the ground and track more effectively what is entering public coffers.
A firmer global market, but not without risks
The market outlook remains favourable. Zinc reached its highest levels in more than four years in August 2026. Trading Economics put it at about $3,823 a tonne on 23 August, up more than 6% over the month. Other market trackers confirmed a move to around $3,780-$3,830 a tonne over the same period.
This rise did not come out of nowhere. Reuters reported that prices had been supported by concerns about physical supply, tight stocks and production disruptions elsewhere in the world. In short, the market has tightened, favouring producers able to ramp up volumes quickly. Kipushi is precisely such a producer.
Ivanhoe expects annual production of between 240,000 and 290,000 tonnes of zinc contained in concentrate in 2026, up from 203,168 tonnes in 2025. If that target is met, Kipushi could join the ranks of the world’s largest zinc mines. But this trajectory depends on the site’s technical stability, transport, market access, and the security and regulatory environment.
For Kinshasa, the key issue is not just the volume extracted. It is capturing value. As long as DR Congo exports mainly concentrate, a significant share of industrial revenue and refining remains outside the country. Zinc therefore strengthens the foundations of Congolese mining, but also highlights the structural limits of the extractive model: producing a great deal is not enough if processing, logistics and advanced manufacturing take place elsewhere.
What this surge says about DR Congo and African mining
The rise in Congolese zinc production has significance beyond the Kipushi mine alone. It reinforces DR Congo’s position as a mining power in Central Africa, in a region where CEMAC, logistics corridors to Zambia and southern African export networks shape the flow of raw materials. Even without being a major historical zinc exporter, Kinshasa can now count on an asset capable of broadening its mining portfolio.
For the Congolese state, the budgetary stakes are direct. A mine producing more generates royalties, taxes, potential dividends and subcontracting contracts. In Haut-Katanga and neighbouring areas, the impact is also measured in jobs, road traffic, services, local commerce and pressure on infrastructure. The benefits nevertheless remain uneven as long as value chains are concentrated around the extraction site.
The 2026 episode also sends a broader signal to the continent. Several African states want to move beyond the simple role of raw-material suppliers. DR Congo shows that a well-financed, properly rehabilitated project backed by a public-private partnership can revive an old deposit and restore its place in global markets. The next step will be less spectacular, but more decisive: turning this mining performance into a local industrial base, lasting revenue and Congolese expertise.