Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
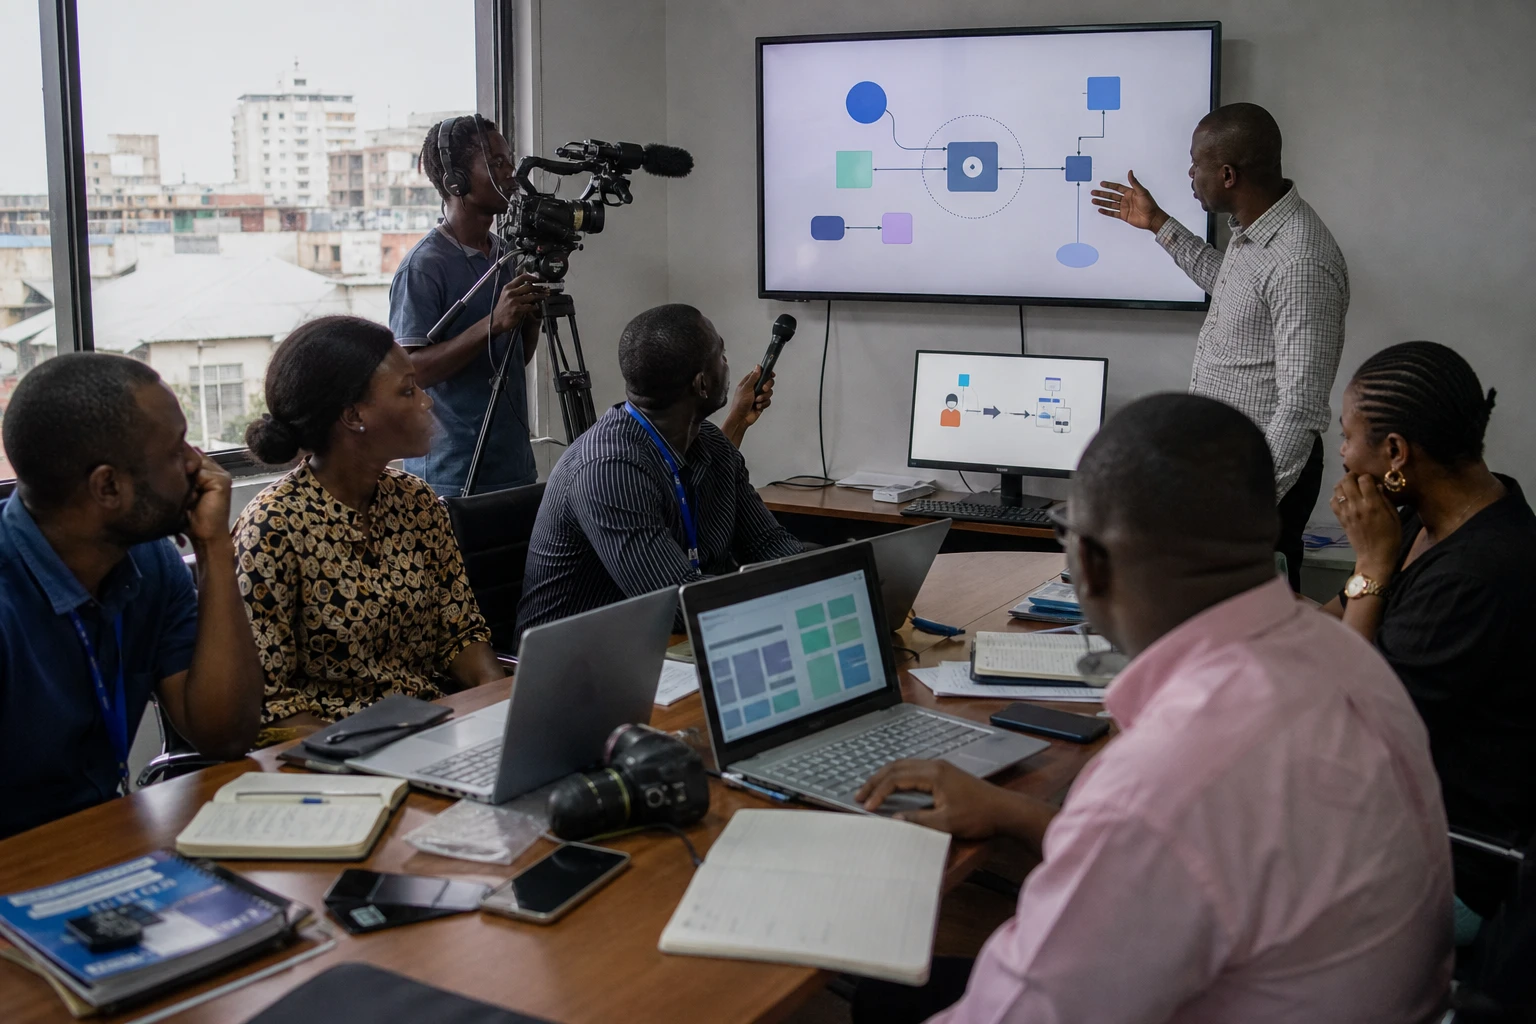
Guinea tests its digital sovereignty in payments
In Guinea, paying has long been neither quick nor simple. Cash, mobile wallets and bank accounts often operated in separate circuits. The launch of NimbaPay in Conakry on Wednesday 22 July 2026 changes that: the country is getting a public instant payment infrastructure designed to move money between different actors without unnecessary technical barriers.
This shift comes as the Central Bank of the Republic of Guinea, the BCRG, seeks to modernise payment methods while retaining control of the national architecture. The central bank notes that cash remains the most widely used means of payment in the Guinean economy, while its services have been involved for years in efforts to reform payment systems.
The choice also has a regional dimension. Guinea is a member of ECOWAS, the West African organisation that has long championed the freer movement of financial flows across the sub-region. And in West Africa, the BCEAO launched its interoperable instant payment platform in the WAEMU on 30 September 2025, an important precedent for neighbouring countries seeking to connect their own infrastructures.
What NimbaPay changes in practice
NimbaPay is designed to connect banks, electronic money institutions and microfinance institutions in a single payment environment. The aim is clear: to enable instant transfers between accounts, wallets and merchants, including in the informal economy, where money still circulates largely in cash. The platform is based on Mojaloop, an open-source system, with technical support from AfricaNenda and ThitsaWorks.
The BCRG presents the system as a response to fragmentation in the payments market. This fragmentation comes at a cost: delays, processing fees, difficulty getting systems to communicate and continued dependence on cash. With an interoperable infrastructure, a transfer can move from a bank to a mobile wallet and then to another institution, without users having to worry about technical barriers. This is what distinguishes a national system from a simple app.
Governor Karamo Kaba also highlights financial inclusion. According to figures he cited at the launch, access to financial services rose from 4% in 2011 to nearly 36% in 2024, driven in particular by electronic money. This figure should be read as an indicator of progress, not as an end point. Above all, it shows that a user base now exists for a more ambitious infrastructure.
For the state, the applications are immediate. NimbaPay could speed up the payment of salaries, social assistance and suppliers. For businesses, the benefits are operational: faster payments, improved cash flow and shorter waiting times. For households, especially outside Conakry, the advantage lies in being able to send and receive money without using lengthy or costly channels.
A technical project, but also a political and regional one
The launch of NimbaPay is not just an IT project. It is also a governance choice. By relying on public digital infrastructure, Guinea reduces its dependence on proprietary solutions and retains strategic leverage over a sensitive economic function: payments. This approach reflects a broader African trend, with several central banks seeking to control their payment rails rather than delegate them entirely to private platforms.
This choice also has social implications. In a country where the gaps between urban and rural areas remain pronounced, an instant system can reduce travel costs, secure transactions and make financial services more accessible in places far from a bank branch. But the impact will only be real if agent networks, mobile coverage, user trust and service quality keep pace. An interoperable system does not solve everything; above all, it creates the conditions for a more transparent market.
The regional dimension is just as important. Guinea has an interest in preparing to connect with future continental payment rails, notably PAPSS, the Pan-African Payment and Settlement System backed by Afreximbank and the AfCFTA, which aims to facilitate cross-border payments in local currencies. If NimbaPay delivers on its promises, Conakry could have an entry point compatible with this emerging African architecture.
For ECOWAS, the stakes go beyond Guinea alone. West Africa is progressing at different speeds. WAEMU put its PI-SPI platform into service in September 2025, while other countries in the sub-region are developing their own systems. The future will therefore depend less on multiplying closed solutions than on their ability to communicate with one another. This is where NimbaPay will have to prove its value: not only by working within the country, but also by opening up to regional payments in the future.
Ultimately, the issue is simple. If the system wins the trust of banks, mobile operators, microfinance institutions, merchants and public administrations, Guinea will cross a quiet but decisive threshold: making instant payments an everyday public infrastructure, serving a more fluid, inclusive economy that is better connected to West Africa.