Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
Home loans remain the main obstacle
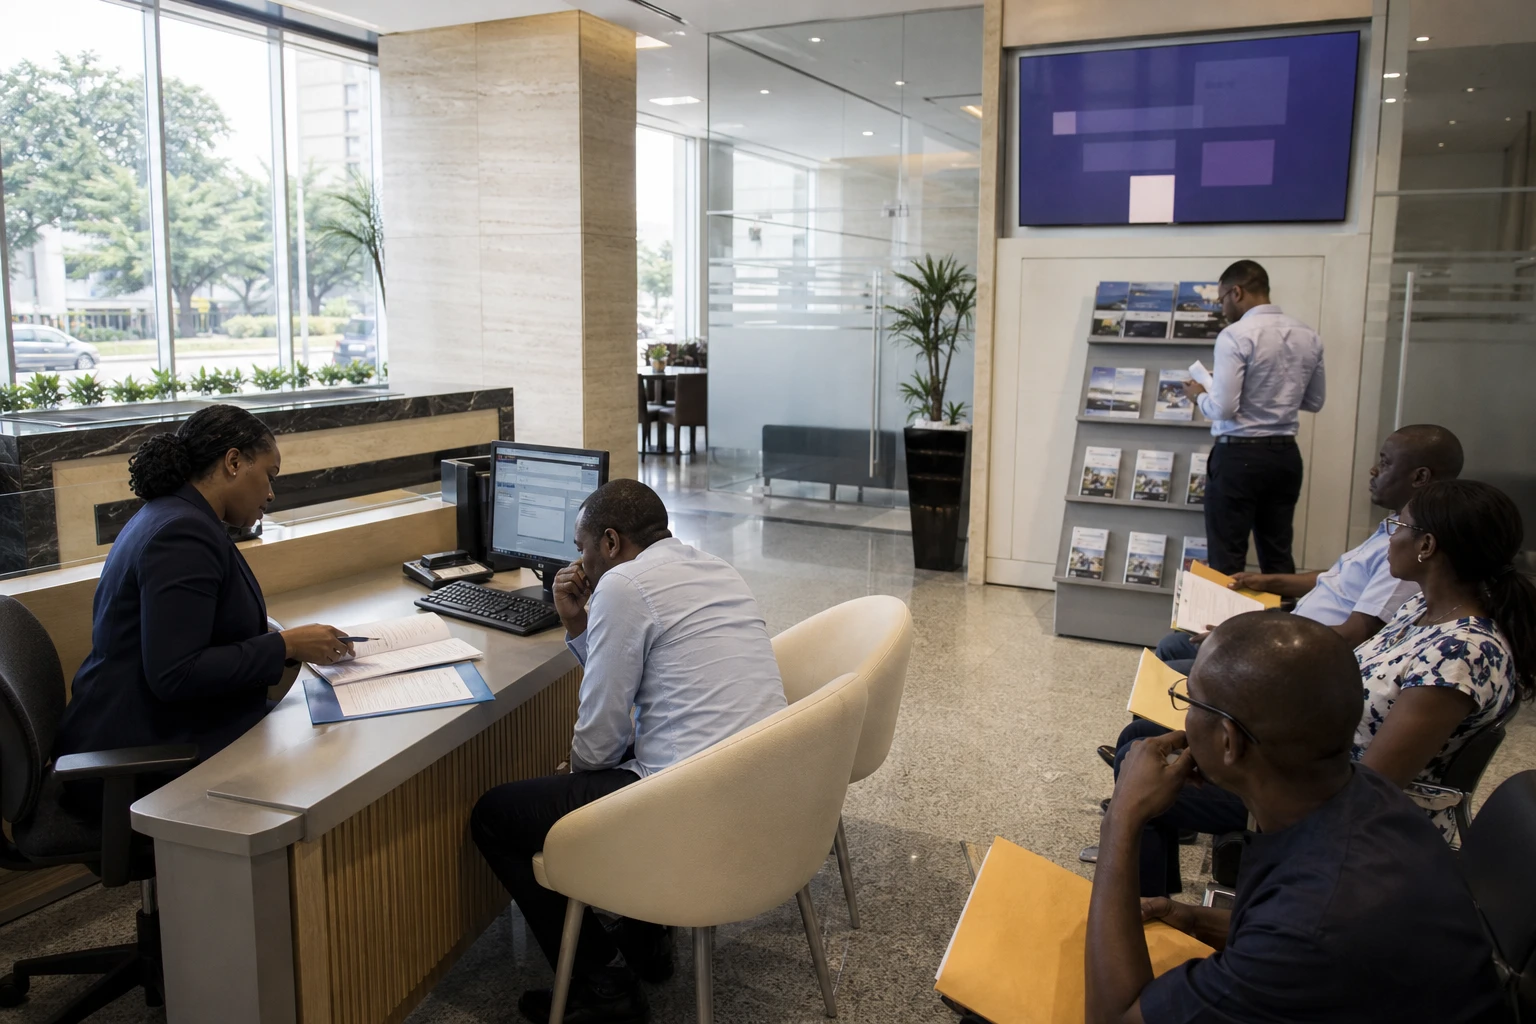
In Côte d’Ivoire, buying a home is not simply a matter of finding a plot of land or signing a preliminary agreement. The hardest part is often the same: turning a family’s plans into a robust bank application. It is in this space, between regular income, a personal contribution and guarantees, that access to home ownership remains out of reach for a large share of Ivorian households.
The issue is all the more pressing as the country continues to absorb rapid urban growth. Ivorian authorities cite a housing deficit estimated at more than 800,000 units, increasing by around 10% a year. The government also notes that nearly 150,000 households settle in Côte d’Ivoire each year, keeping pressure on Abidjan and secondary cities.
Against this backdrop, NSIA Banque Côte d’Ivoire has launched a commercial campaign dedicated to home loans, running from 15 July to 15 October 2026. Designed for individuals, the offer covers purchases, construction, renovation and even rental investment. It provides financing of up to CFA150m, repayable over a maximum of 21 years depending on the customer’s profile.
A bank offer backed by a regional facility
The standard rate announced for this type of financing is 8% excluding tax. It can fall to 6.5% excluding tax when the transaction comes under the CRRH-UEMOA scheme, the Regional Mortgage Refinancing Fund of the West African Economic and Monetary Union, which provides long-term funding to banks in the region for home loans. The CRRH-UEMOA covers the eight WAEMU countries: Benin, Burkina Faso, Côte d’Ivoire, Guinea-Bissau, Mali, Niger, Senegal and Togo.
This is important. In West Africa, the problem is not only the cost of housing. It also involves the cost of money, the maturity of banks’ funding and households’ ability to submit an application that meets lending requirements. The regional refinancing mechanism is specifically intended to ease this constraint. The World Bank also notes that the WAEMU region faces a shortfall of about 3.5m decent homes.
NSIA Banque also says it intends to help borrowers put together their applications, taking into account their income, borrowing capacity and the nature of their project. The offer is aimed in particular at civil servants, private-sector employees on permanent contracts, and customers and prospective customers who meet the bank’s lending criteria. This focus shows that access to housing remains closely linked to stable formal employment, while a large part of the Ivorian economy remains informal.
Housing between public policy and financial markets
The bank’s campaign has not emerged in isolation. It is part of a wider effort by public and private actors to overcome the same obstacle: financing more homes without putting excessive strain on banks’ balance sheets. A few months before this commercial initiative, the BRVM, the Regional Securities Exchange, hosted the first listing of bonds linked to the “FCTC ZAKA RMBS NSIA BANQUE CI 2025-2036” vehicle. The BRVM set the first listing date for 29 April 2026.
The transaction has both symbolic and technical significance. It marks one of the first public issues of securities backed by residential mortgages on the WAEMU market. The bank sold a portfolio of 188 loans worth a total of CFA10bn to refinance its existing loans and free up new lending capacity.
For Côte d’Ivoire, the issue goes beyond commercial messaging. For several years, the country has pursued a policy of social and affordable housing, with recurring announcements about homes built, land reforms and refinancing mechanisms. The authorities stress in particular that the national housing programme was designed to reduce the structural deficit and broaden access to decent housing.
But a substantial gap remains between household needs and construction capacity. In Abidjan, where most effective demand is concentrated and much of the pressure on land is felt, land prices, servicing costs and bank requirements make home ownership difficult for the middle classes. In provincial areas, the problem is often different: there is less formal supply, and financing is even harder to obtain. Home loans thus remain a product reserved for a small, banked minority.
What the push says about the Ivorian market
By opening a commercial window on housing, NSIA Banque is also seeking to expand its customer base and attract long-term savings, which remain scarce in the region. It is a rational bet in a market where demand is structural. The country’s urbanisation rate has risen sharply over the decades, and housing needs continue to grow faster than formal supply.
For households, the stakes are concrete: a longer-term loan reduces monthly repayments, but it does not solve everything. Borrowers still need a stable income, borrowing capacity that complies with banks’ limits and, often, an initial contribution. For banks, the challenge is twofold: lend more without taking on excessive portfolio risk, then refinance those loans so as not to constrain their lending capacity. This is precisely where the CRRH-UEMOA plays its regional role.
Across West Africa, the issue remains strategic. WAEMU shares the same monetary framework, the same regional financial market and some of the same pressures: rapid urban growth, land scarcity, irregular incomes and a huge need for affordable homes. NSIA Banque’s campaign in Côte d’Ivoire will not solve this problem on its own. It does, however, show that part of the response now involves more sophisticated arrangements combining retail banking, mortgage refinancing and the regional bond market.