
 Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
An industrial bet on a sector that accounts for a large share of Ghana’s imports
In West Africa’s coastal countries, the question is no longer just how to produce more. It is also how to process, preserve and transport food on a large scale. In Ghana, poultry has become a practical test of that capacity.
The average Ghanaian faces more than the high price of imported chicken. Behind the market shelves in Accra and inland cities, they can also see the limits of a local industry still too dependent on inputs, cold storage and financing. It is against this backdrop that a $270 million private-sector project takes on strategic significance.
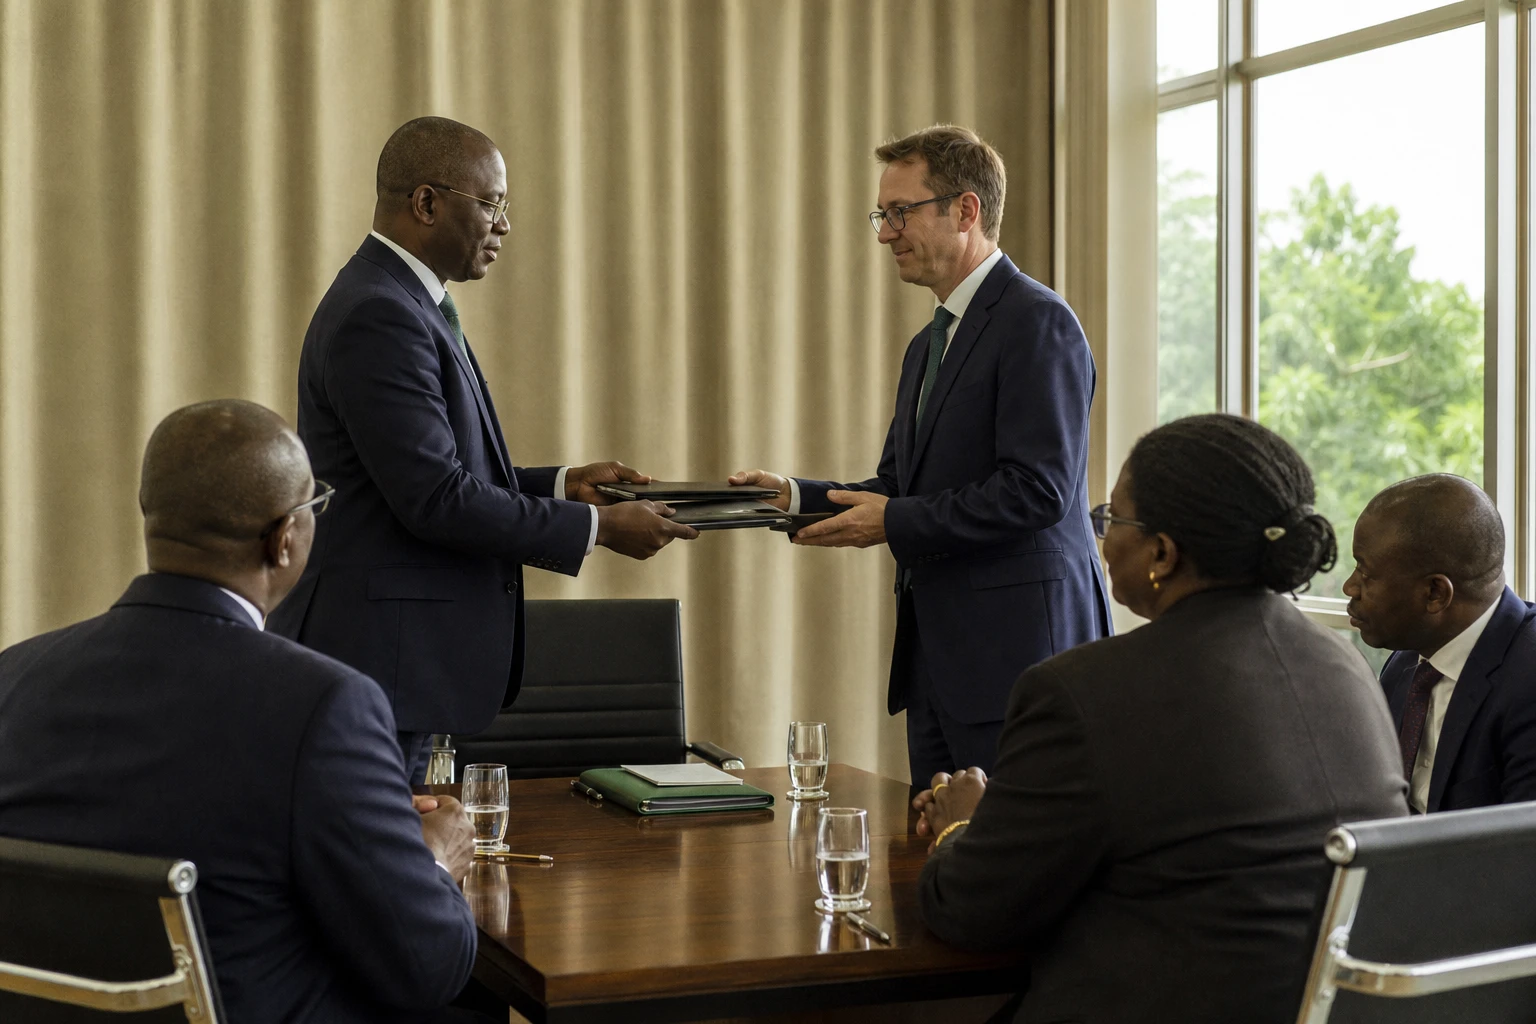
On 28 August 2026 in Accra, the secretariat of the 24-Hour Economy and Accelerated Export Development programme, private-sector partners and Ghanaian financial institutions signed heads of terms for a national poultry transformation programme. The deal brings together Agrium Capital, the agribusiness subsidiary of British group Asset Green, Petra Trust, Axis Pension Trust and Ghana EXIM Bank. The plan spans the entire value chain: poultry feed, hatcheries, commercial farming, processing, cold storage, logistics and distribution.
According to the official document, the first phase is to produce 20,000 tonnes of processed chicken a year, before scaling up to 50,000 tonnes. The project is billed as the largest British agribusiness investment ever announced in Ghana and is expected to create 12,000 direct jobs.
Ghana as a test case for a wider African strategy
The choice of Ghana is no accident. The country belongs to ECOWAS, the Economic Community of West African States, and also hosts the secretariat of the AfCFTA, the African Continental Free Trade Area, in Accra. In other words, poultry is not just a matter for farms or the local market. It also concerns regional integration and the continent’s ability to sell more processed goods.
In this context, the initiative announced in Ghana fits a pattern already visible elsewhere. In Ethiopia, EIH, EABC and Asset Green signed a project agreement worth about $600 million for an integrated dairy farm and commercial crops. In Nigeria, the NSIA announced a $496 million partnership with Asset Green for a dairy and processing platform. The three projects therefore share the same investment signature, with different formats but the same target: food value chains in deficit.
Adding up these announced amounts gives $1.366 billion in agribusiness projects in Africa since February 2025. This is an indicator, not a guarantee of delivery. But it clearly shows the British group’s direction of travel towards markets where local demand is strong and production remains insufficient.
An import bill weighing on households and the trade balance
The core issue remains dependence on imports. On paper, Ghana still produces too little chicken to meet its consumption needs. US Department of Agriculture data put Ghana’s chicken meat imports at 270,000 tonnes in 2024, while domestic production remains well below total demand. The same document puts domestic consumption at around 340,000 tonnes that year.
In Ghana, the Ministry of Agriculture has for several years said that the annual poultry import bill stands at between $300 million and $400 million. In April 2026, the FAO cited this range in support for the Feed Ghana programme, which aims to strengthen local livestock farming, particularly in the north of the country.
This dependence has very tangible effects. For urban consumers, it keeps pressure on prices and limits access to a common source of protein. For local producers, it means competition from frozen imports, high feed costs, limited access to cold storage and difficulty financing the expansion of farms. For the state, it increases foreign currency outflows and reduces the share of local value added.
The project announced in Accra is designed precisely to address these bottlenecks. It is not just about rearing more chickens. It is about securing feed supplies, controlling hatcheries, improving meat processing and connecting production to cold storage and distribution. That is where the difference lies between a simple farm and an industrial value chain.
What the project says about the new agricultural balance of power in West Africa
The Ghanaian agreement also reflects a change in approach. Financing does not rely solely on the state. It combines foreign private capital, Ghanaian institutional investors and public instruments such as Ghana EXIM Bank. This structure is of particular interest to African countries seeking to industrialise agriculture without shouldering the sovereign debt burden alone.
For Ghana, delivery will be the key. The heads of terms are not yet a definitive shareholders’ agreement. The official text says the parties still need to turn the agreement into a shareholder agreement in the coming weeks. The announced design and development period of 10 to 12 months also suggests that the most sensitive phase is now beginning.
At regional level, the signal is clear. ECOWAS economies import large quantities of food that they are themselves capable of producing, at least in part. Yet the combination of growing urban demand, a more integrated regional market and pressure on foreign currency reserves is now pushing governments to offer greater support for local processing. Ghana clearly wants to position itself within this movement.
The project’s continental significance therefore goes beyond poultry. It touches on agribusiness financing, food sovereignty and African states’ ability to attract capital to productive projects rather than purely commercial operations. The Ghanaian project will be closely watched until the UK-Ghana bilateral summit scheduled for 24 September 2026, which could provide a showcase for this type of partnership.
Ultimately, the question is simple: can Ghana turn a costly dependence into a competitive industry? The answer will depend less on the announcement than on the speed of implementation, the actual reduction in production costs and the project’s ability to support a sustainable local industry beyond the capital investment.



