Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
When the state takes a stake, the risk changes
In Accra, the idea seems simple: if gold is extracted from Ghanaian soil, Ghana should receive more than taxes and royalties. But when the state becomes a shareholder, it also shares the risks of operations, cash-flow pressures and market shocks. That is precisely the territory of the experiment involving Asante Gold, whose trajectory is a reminder that public ownership is no automatic shield.
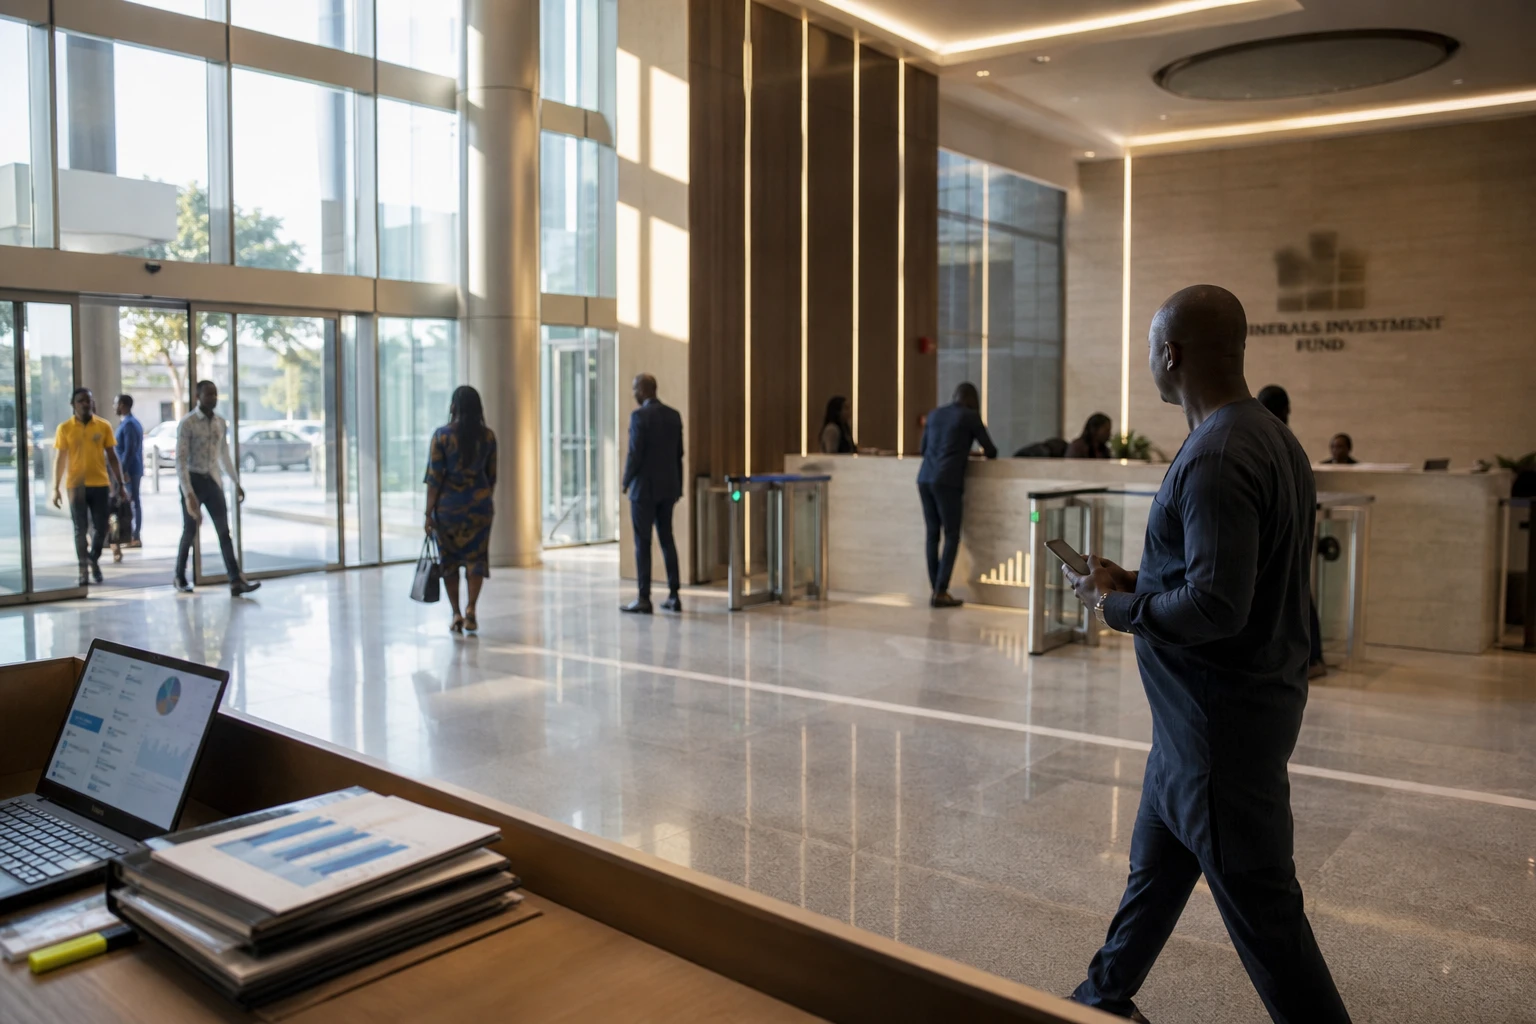
In Ghana, this strategy operates within a specific framework. The Minerals Income Investment Fund, or MIIF, manages the state’s equity interests in mining companies and revenues from minerals. Its entry into Asante Gold was presented as a way to capture a more direct share of gold revenues, while giving local investors access to a major listed mining company.
The issue goes beyond the case of Accra. In West Africa, where ECOWAS is still seeking its bearings in the face of political and economic shocks, the question of mining sovereignty is once again coming to the fore. Several states want to move further up the value chain. They also want to prevent profits from flowing abroad too quickly. The Ghanaian case, however, shows that taking a stake means weighing another risk: supporting a fragile company at the very moment it becomes a public-sector bet.
Asante, Bibiani, Chirano: how events unfolded
The case developed in stages. Asante Gold operates or is developing several assets in Ghana, notably Bibiani and Chirano, in the Western North Region. The Bibiani mine was acquired in August 2021, and Chirano joined the company’s portfolio in August 2022. The two sites are central to its presence in Ghana.
The MIIF then took a direct stake in Asante. The Fund’s public documents refer to an investment of about US$40 million, described as its first transaction in the listed sector. The case is also linked to Asante’s listing on the Ghana Stock Exchange, which was formalised on 29 June 2022. The listing opened up the company’s share capital to Ghanaian individuals and institutions.
The most recent developments confirm that the company is going through a difficult period. On 27 July 2026, Asante Gold announced that its chief financial officer, David Wiens, had resigned, effective 14 August 2026. The company said he was leaving to pursue another opportunity. His departure comes as Asante is also conducting an operational and strategic review of Bibiani and Chirano.
The company’s published results show the pressure it is under. For the quarter ended 31 March 2026, Asante reported revenue of US$300.4 million, up 111.6% year on year, driven by a record gold price and higher volumes. But the company also reported operational incidents, including a slope failure at Bibiani’s main pit, which delayed access to higher-grade ore.
At the same time, management has acknowledged financial strain. Asante delayed some payments to suppliers, secured an extension of about US$55 million related to its gold hedges and pledged to raise at least a further US$100 million by the end of August. It also deferred or cancelled US$50 million of planned investment in 2026.
What the crisis says about Ghana’s mining strategy
The Asante case is forcing Accra to confront reality. A public-sector stake can strengthen local value capture. It can also expose the state to a falling share price, dilution and financing needs that the market does not always meet. The risk is therefore not only operational. It also affects the state’s assets. The MIIF has not, so far, disclosed the current value of its holding or the returns it generates.
Ghana is not an isolated case. Across the continent, several governments want to turn mineral wealth into a financial asset, not just a source of budget revenue. This logic is understandable. It responds to strong expectations in producer countries. But it requires sound governance, a realistic understanding of commodity cycles and the ability to distinguish the role of regulator from that of shareholder. Without this separation, the state may find itself defending a stock-market valuation while weighing the public interest.
The importance of the gold sector adds to the stakes. Gold remains a pillar of Ghanaian exports and a sensitive economic policy issue. The MIIF says it wants to use its investments to capture more mining revenue for the country, while the authorities are also seeking to support local investment through the Accra stock market. In this context, the Asante case is a real-world test of Ghanaian mining finance.
For workers, suppliers and communities in the Western North Region, the stakes are even more tangible. If the company manages to recover, activity could stabilise, investment could resume and the local supply chain could benefit from a rebound. If financial strain persists, late payments, reduced purchasing and cuts to expansion projects will hit the real economy first, long before they show up on market dashboards.
The West African implications of a bet on gold
Across West Africa, this case speaks to many capitals. It is a reminder that a policy of mining sovereignty is not simply a matter of buying stakes. It also requires protecting public investment, monitoring corporate governance and planning for ways out of a crisis. Rising gold prices can mask weaknesses for a while. They do not make them disappear.
The next point to watch will be Asante’s ability to implement its recovery plan in the coming months, with Bibiani and Chirano as its core assets. The company is still targeting a medium-term ramp-up, but first it must stabilise its cash flow, financial leadership and operations. For Accra, the episode will probably serve as a reference point when assessing other equity investments in the extractive sector.
In a country where the question of locally captured value has become political, industrial and financial all at once, Ghana is testing an ambitious idea. The outcome will show whether the state can be an arbiter, partner and beneficiary at the same time without becoming trapped by the very risk it sought to share.