
 Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
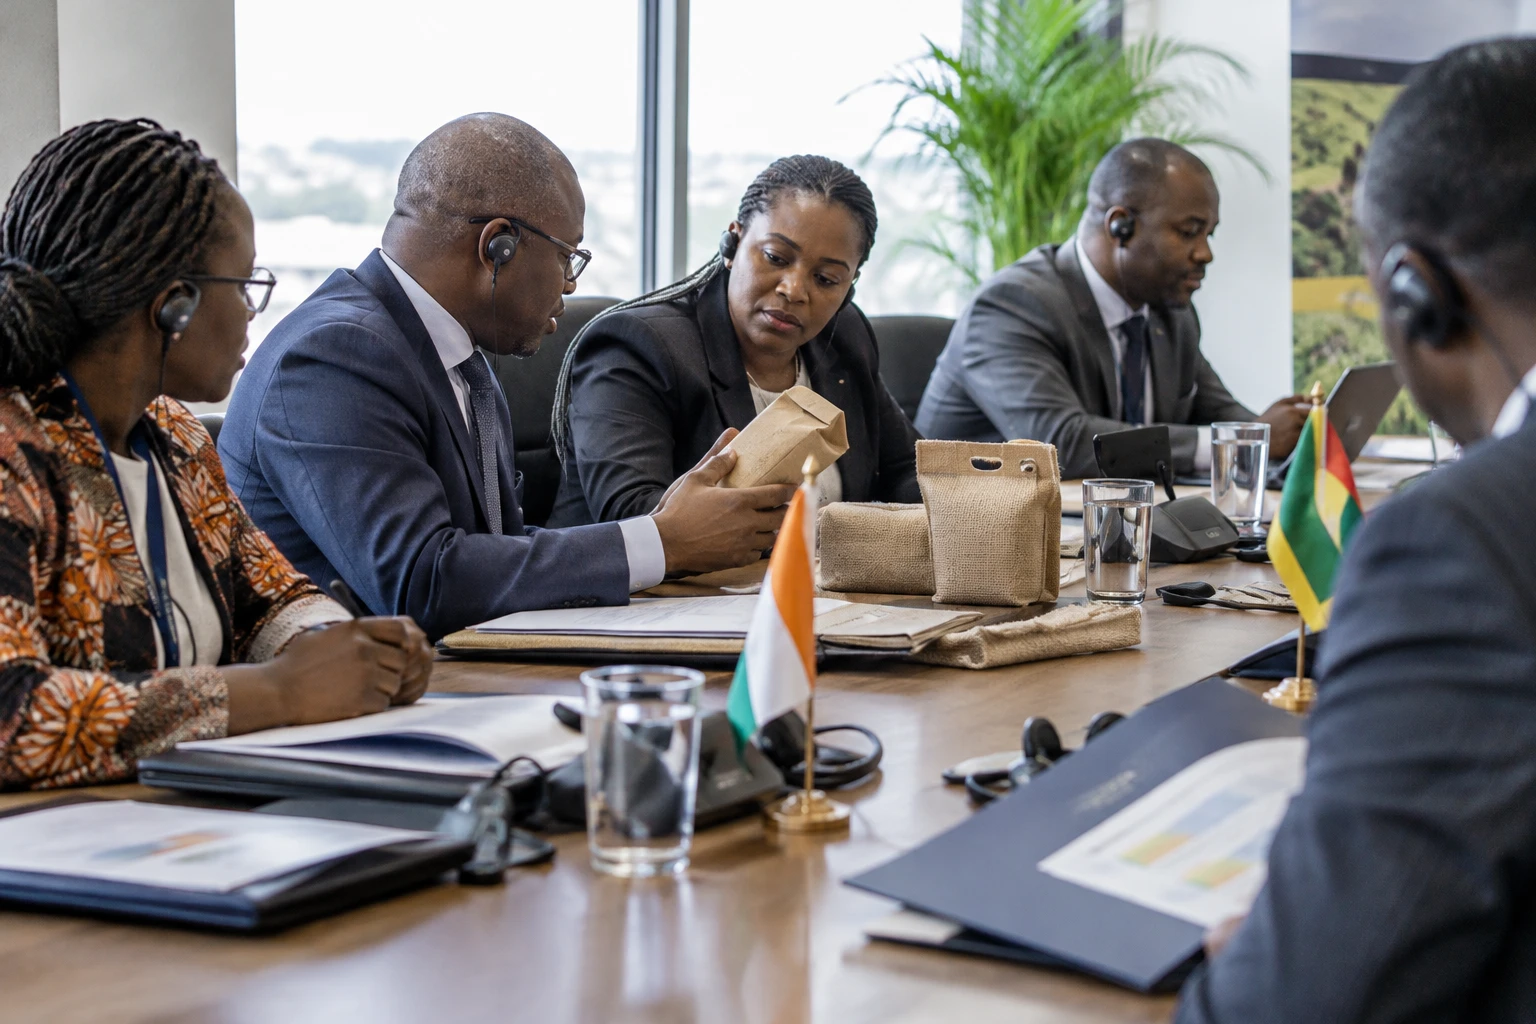
Higher orders are not always enough to turn a company around. In Côte d’Ivoire, FILTISAC is selling more packaging, but the cost of supplies and financing continues to weigh on its accounts. The contrast matters for an industry linked to agricultural campaigns and regional trade.
A company at the heart of agricultural value chains
Based in Abidjan, FILTISAC makes jute sacks for cocoa, coffee and cashew nuts, among other products, as well as synthetic packaging for other activities. Founded in 1965 to meet the packaging needs of Côte d’Ivoire’s exports, the company serves products moving between production areas, ports and markets across the sub-region.
This position links its results to several economic realities. Demand varies with agricultural campaigns. Commodity and transport prices affect costs. Finally, cash-flow needs rise when the company has to finance its stock and operations before collecting payment for sales.
FILTISAC is listed on the Bourse Régionale des Valeurs Mobilières (BRVM), the shared financial market for several countries in the West African Economic and Monetary Union (UEMOA). Its results therefore also give regional investors an indication of the health of an Ivorian industrial player. Côte d’Ivoire’s political capital is Yamoussoukro; Abidjan remains the main economic centre and the company’s headquarters.
Revenue accelerates as operations return to profit
In its activity report for the period ending on 30 September 2026, FILTISAC reported revenue of CFA francs 25.69 billion, against 18.37 billion in the first nine months of 2025. The increase was about 40%. Management attributed it mainly to sales of jute packaging.
Growth accelerated sharply in the third quarter. Subtracting first-half figures from the nine-month total gives quarterly revenue of CFA francs 9.25 billion, against 4.97 billion a year earlier. This calculation indicates growth of close to 86% over the period. It is an estimate based on cumulative figures, rather than a quarterly amount reported separately.
Operating profit, which measures business performance before financial charges and certain exceptional items, reached CFA francs 152 million. It was a loss of 230 million in the first nine months of 2025. The turnaround was pronounced in the third quarter: after an operating loss of 509 million in the first half, the company appears to have generated 661 million between July and September.
This improvement nevertheless remains fragile. Operating profit represents only 0.6% of cumulative sales. In the first quarter, the company had already reported strong demand for cocoa packaging, but also supply difficulties and rising input and freight costs. Higher revenue alone therefore does not guarantee a sufficient margin.
Financing absorbs some of the gains
The main pressure point is the financial result. It shifted from a surplus of CFA francs 87 million to a loss of 481 million year on year. Management linked the deterioration to an increase in the operating funding requirement, which led to higher financial charges.
The accounts reflect a squeeze: operations have returned to profit, but financing costs erode that gain. The result from ordinary activities showed a loss of CFA francs 329 million, against 143 million at the end of September 2025. Despite a positive result of 10 million from non-ordinary activities, the current pre-tax loss reached 319 million, against 216 million a year earlier.
The nine-month report does not give a net result. In the first half, the company’s accounts showed a net loss of CFA francs 770 million, against a profit of 105 million in the first half of 2025. This half-year figure should not be confused with the current result at the end of September: the periods and indicators differ.
Management said tensions in the Middle East had made supplies of jute and polymers more expensive. Price adjustments charged to customers offset only part of the increase. For buyers, particularly agricultural operators, passing on these costs can also put pressure on packaging spending. The published results do not, however, make it possible to measure precisely how the burden is shared between the company, its customers and producers.
The next agricultural campaigns will be decisive
For the remainder of the financial year, FILTISAC is counting on cocoa and cotton campaigns across the sub-region, as well as on optimising its costs. The challenge will be to turn demand into sustainable revenue while limiting purchasing costs and reliance on short-term financing. A recovery in volumes will not automatically ease pressure on margins.
Ivorian cocoa gives this issue significance beyond the company. Packaging is part of the logistics chain for a major industry, while cotton production and trade involve several West African countries. FILTISAC’s performance therefore depends on its customers’ business conditions, supply costs and the smooth flow of regional trade.
The report’s figures are cited in an independent financial analysis, which confirms the main amounts against available publications. The BRVM is the official access point for documents from listed companies; the page consulted lists FILTISAC publications but does not show the September report in the visible list. The nine-month figures should therefore be read as data reported by the company, not as an annual result already secured.
The next financial disclosure and the course of agricultural campaigns will show whether the commercial acceleration continues. The key signal to watch will not be sales alone, but also FILTISAC’s ability to reduce financial charges and generate a more robust operating margin.



