Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
A shortage of homes in a growing city
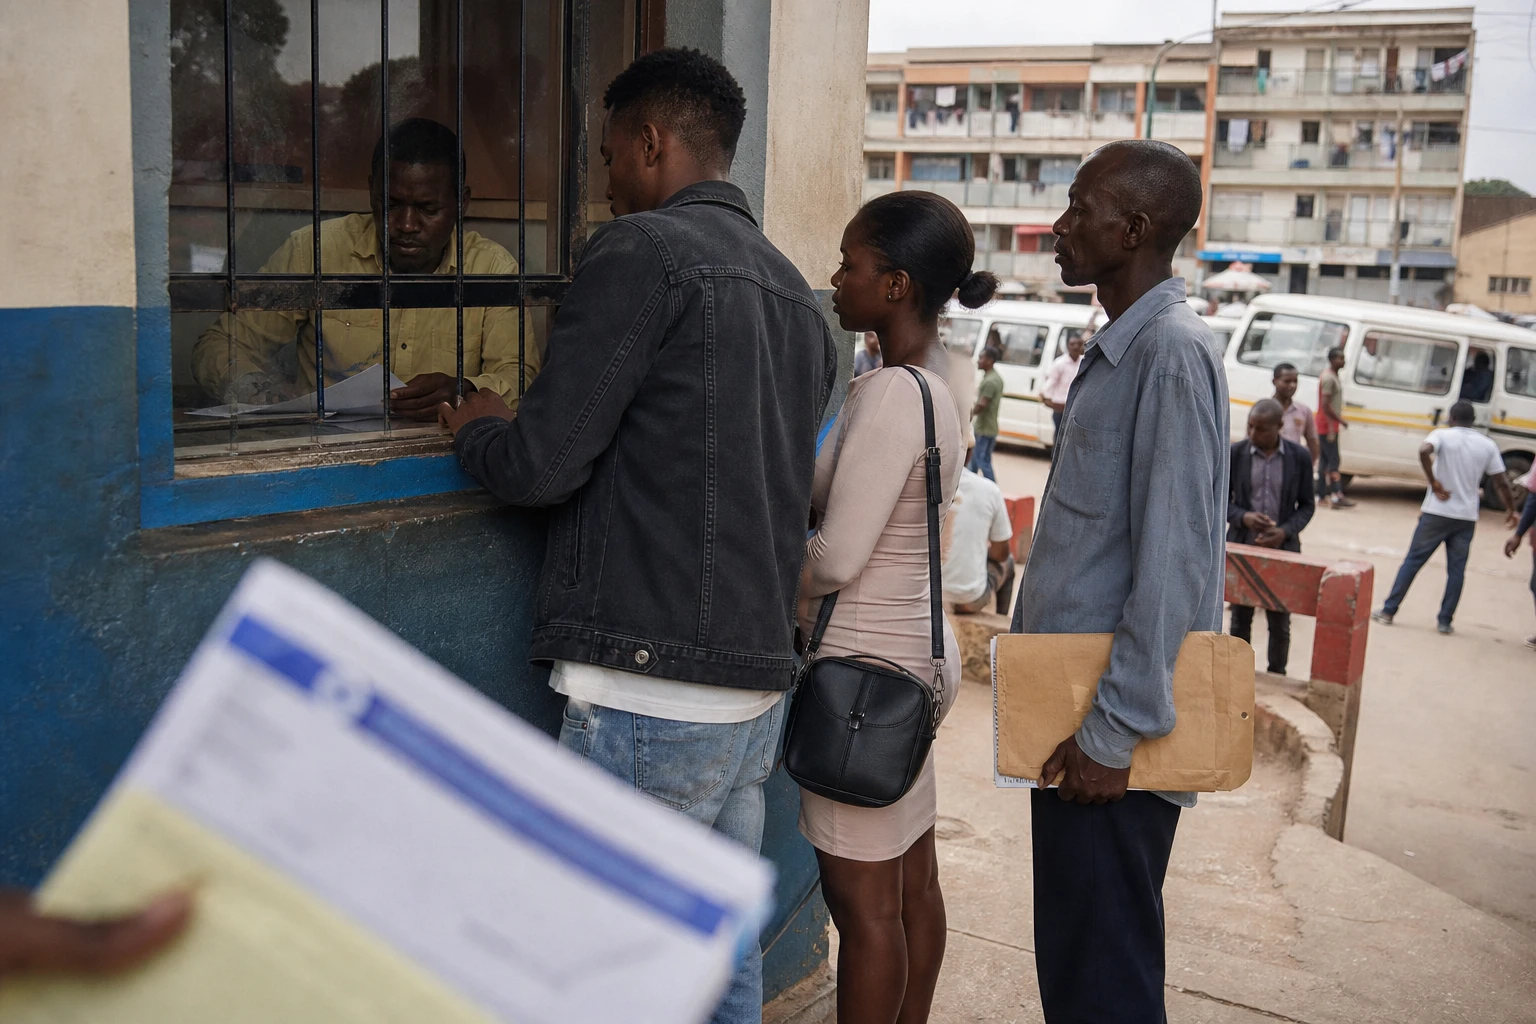
In Kinshasa, finding a home is already an obstacle course for low-income households. Across the rest of the Democratic Republic of the Congo, the problem is on a different scale: it involves rapid urbanisation, the cost of land and the lack of large-scale mortgage lending. The government now wants to treat the crisis as an economic policy issue, not just a social one.
On Friday 28 August 2026, in Kinshasa, Prime Minister Judith Suminwa Tuluka asked the ministers concerned to examine transforming the National Housing Fund, FONHAB, into a public housing bank. The aim is to give the state an instrument capable of financing housing over the long term, supporting mortgage lending and securing social housing programmes.
The heart of the problem: financing homes, not just building them
The issue is not new. Several assessments have converged over the years: the DRC has a housing shortfall of about 4 million homes, and around 250,000 to 265,000 units would need to be built each year to keep pace with demographic demand. In Kinshasa alone, estimates point to nearly half the national shortfall and more than 140,000 homes needed each year.
The International Finance Corporation, the private-sector arm of the World Bank Group, has estimated that around $132bn in investment would be needed over several years to close this gap. The figure gives a sense of the scale of the challenge: it far exceeds the Congolese state’s ordinary budgetary room for manoeuvre.
This constraint explains the government’s choice. In theory, a specialised public bank would make it possible to raise more stable funding, extend loan terms and better structure demand. In the DRC, mortgage lending remains limited because commercial banks favour short-term horizons and require guarantees that most households struggle to provide.
Why Kinshasa is under the greatest pressure
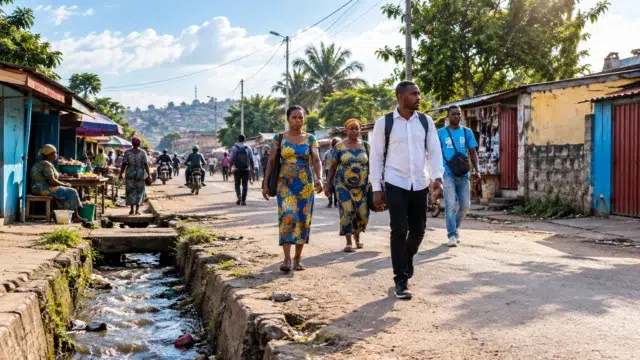
The Congolese capital is the focal point of demographic pressure. It attracts families from several provinces, young workers, civil servants and a large informal sector. This growth is driving up rents, rapidly expanding outlying neighbourhoods and often leading to homes being built through self-construction rather than formal channels.
The government also links housing to another undertaking: the availability of reliable data. In March 2026, the presidency stressed the role of the second general census of population and housing, RGPH-2, describing it as an essential tool for planning public policy. Without up-to-date figures, neither urban planning nor housing finance can be properly calibrated.
In this context, reforming FONHAB follows a simple logic: understand demand better, then create a financial vehicle capable of supporting it. The issue goes beyond construction itself. It also concerns access to home ownership, the formalisation of land, the legal security of title deeds and the state’s ability to make its programmes clear to private investors.
What a public housing bank could change
If it is established, a public housing bank could play several roles. It could refinance mortgages, lend over longer terms, support social housing developers and make better use of certain public property assets. In a country where most homes are still built outside the formal sector, such an institution could also bridge the gap between national savings, household needs and development projects.
But success will depend on major conditions. A clearer land framework, credible securitisation procedures, rigorous credit risk management and governance shielded from political interference will be needed. Without these safeguards, a public bank could lend too little, poorly or too slowly. The problem would then be not only financial but also institutional.
For households, the stakes are concrete. Many currently pay high rents without any prospect of buying a home. For the urban middle classes, longer-term and more accessible loans would change the picture. For low-income households, the impact will depend above all on the state’s ability to offer genuinely affordable homes, rather than products aimed only at a solvent minority.
A Congolese decision, but a regional signal
The issue extends beyond the DRC. Across Central Africa, several capitals face the same tension between urban growth, housing shortages and a lack of long-term credit. The public housing bank envisaged in Kinshasa is therefore part of a broader continental question: how can African urbanisation be financed without leaving the informal market to absorb demand on its own?
The timeline will show whether this announcement leads to genuine reform. The government will need to clarify FONHAB’s remit, its capital, its funding sources and how it will work with commercial banks, the land registry and land policies. The project’s credibility will be decided at this level, far more than by the name of the future institution.
For the DRC, housing is no longer just a matter of urban planning. It is a test of economic sovereignty, public organisation and the ability to support a population that continues to grow and urbanise. In Kinshasa, as in several of the country’s major cities, the response to this pressure will say much about how the state intends to manage growth.