Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
A new market, but not yet a stock exchange
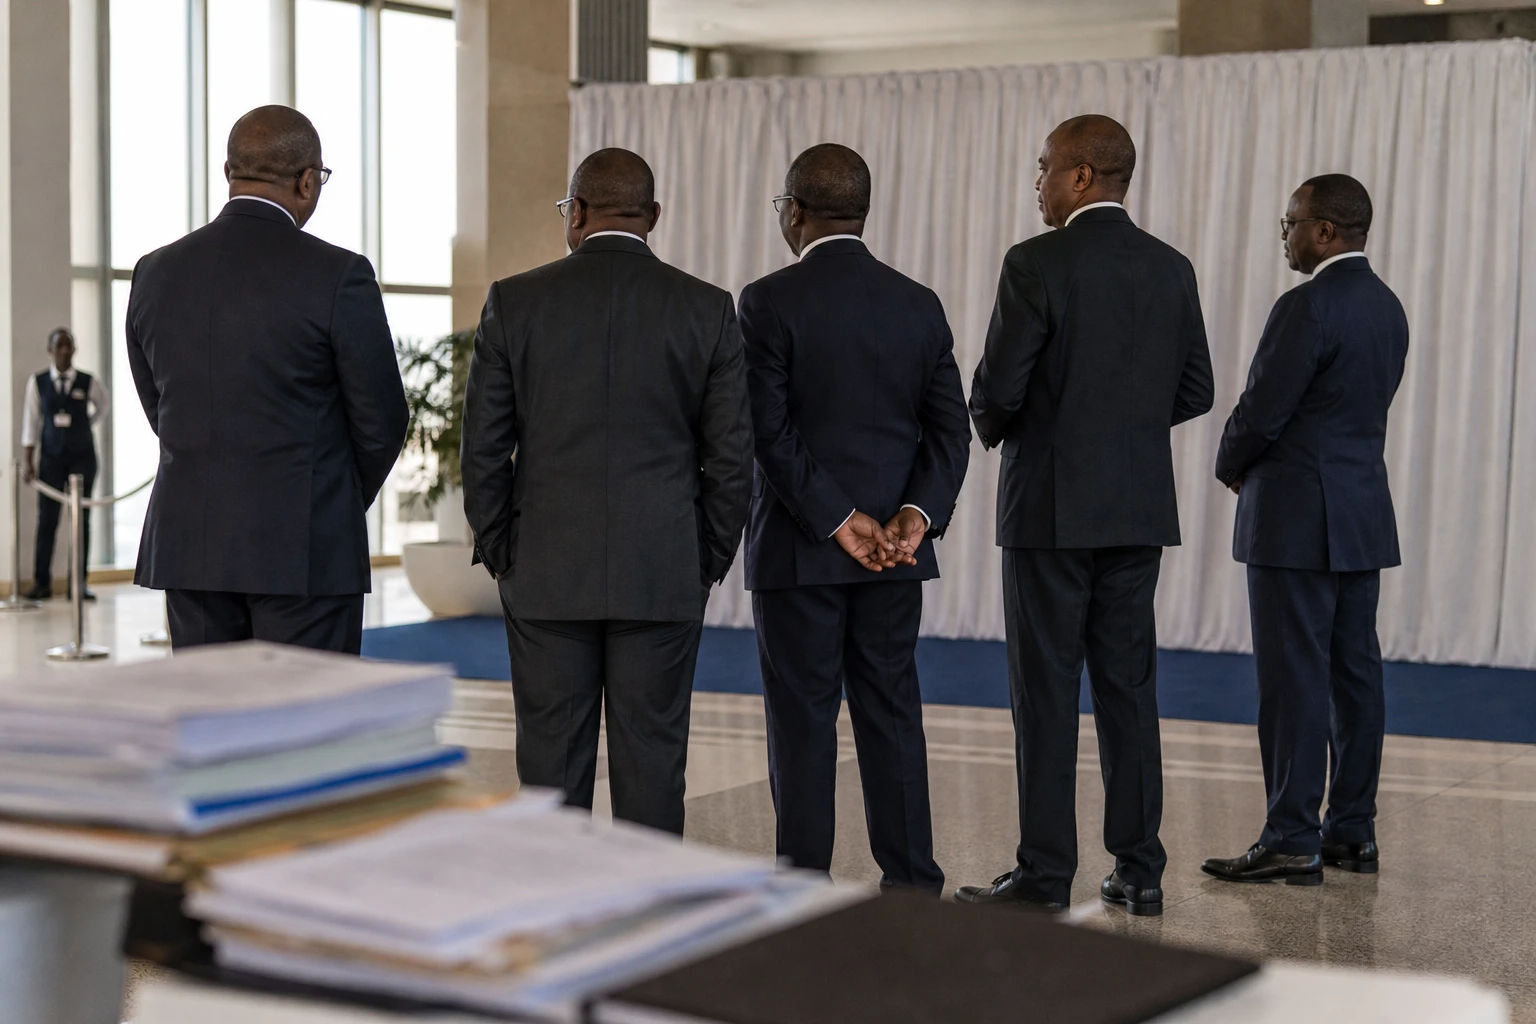
In the Democratic Republic of the Congo, the challenge is not simply to create a stock exchange. The key question is whether Congolese savings can finally circulate within a clear, supervised framework that helps finance the real economy. For now, the country is laying the foundations for a capital market that does not yet exist in practice.
This process is unfolding in a broader regional context. DR Congo belongs to both SADC and the East African Community, two blocs that each promote economic integration, the movement of capital and the harmonisation of rules in their own way. In the region, more established financial centres such as Johannesburg also show that a stock exchange is not a symbol. It is an infrastructure of trust, with rules, intermediaries and robust oversight.
What Congolese law provides for
The law on stock markets was promulgated by President Félix Tshisekedi on 25 August 2026, after being adopted by parliament. It sets out the rules for organising, financing, supervising and regulating stock markets in DR Congo. Its publication in the Official Gazette on 2 September 2026 provided a legal framework for a reform long in the making.
The government presents the law as a tool for mobilising resources. In theory, companies will be able to raise funds by selling shares or issuing bonds. The aim is to complement bank lending, which is often insufficient to finance long-term projects. The authorities want to attract large companies, as well as SMEs and start-ups. Mining is among the sectors considered a priority, in a country where mineral resources carry considerable weight in the economy and in investors’ perceptions.
What remains to be built
The law alone is not enough. Several institutional building blocks must be put in place before the first transaction. First, the committee responsible for operationalising the market must be established, the roadmap approved and the Financial Markets Regulatory Authority set up. Next, the general regulations must be adopted and the Kinshasa Stock Exchange licensed. Finally, technical tools still need to be created, including a central securities depository, settlement banks and a digital trading platform.
This explains why no shares are yet traded in Kinshasa. A stock exchange does not operate by decree alone. It depends on institutions’ ability to protect investors, track securities and ensure transparent transactions. This is precisely the weak point of many emerging markets in Africa: rules can be passed quickly, but trust takes time to build. The agreement with the International Finance Corporation, signed in June 2026, had already pointed in this direction, pledging technical support for the regulatory framework, infrastructure and training for market participants.
What impact could it have on the Congolese economy?
For the state, the reform could diversify funding sources in a country that has often relied on banks, sovereign bond issues or ad hoc solutions. For companies, it could open a route to longer-term capital that is sometimes less costly than conventional debt. For urban households, it could also broaden access to formal investment, provided that financial education keeps pace and products are easy to understand.
But the impact will not be the same for everyone. Large mining companies, banks and telecoms groups are better placed to enter the market first. SMEs, meanwhile, will need more support. In a country where the informal sector remains vast and trust in financial institutions must be earned, the stock exchange cannot rest on political announcements alone. It will have to win people over through simplicity, security and its ability to serve Congolese businesses, from Kinshasa to the provinces.
DR Congo is thus approaching a milestone that several African economies have already reached, each at its own pace. The continent’s experience shows that a strong financial centre is built over time, with clear rules and genuine market depth. In Kinshasa, first listings are now expected in 2027, according to several sources in agreement, but that timetable remains conditional on the establishment of the institutions provided for by law. The real question is no longer whether a Kinshasa Stock Exchange will exist on paper. It is when it will become a credible source of financing for the Congolese people and the regional economy.