
 Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
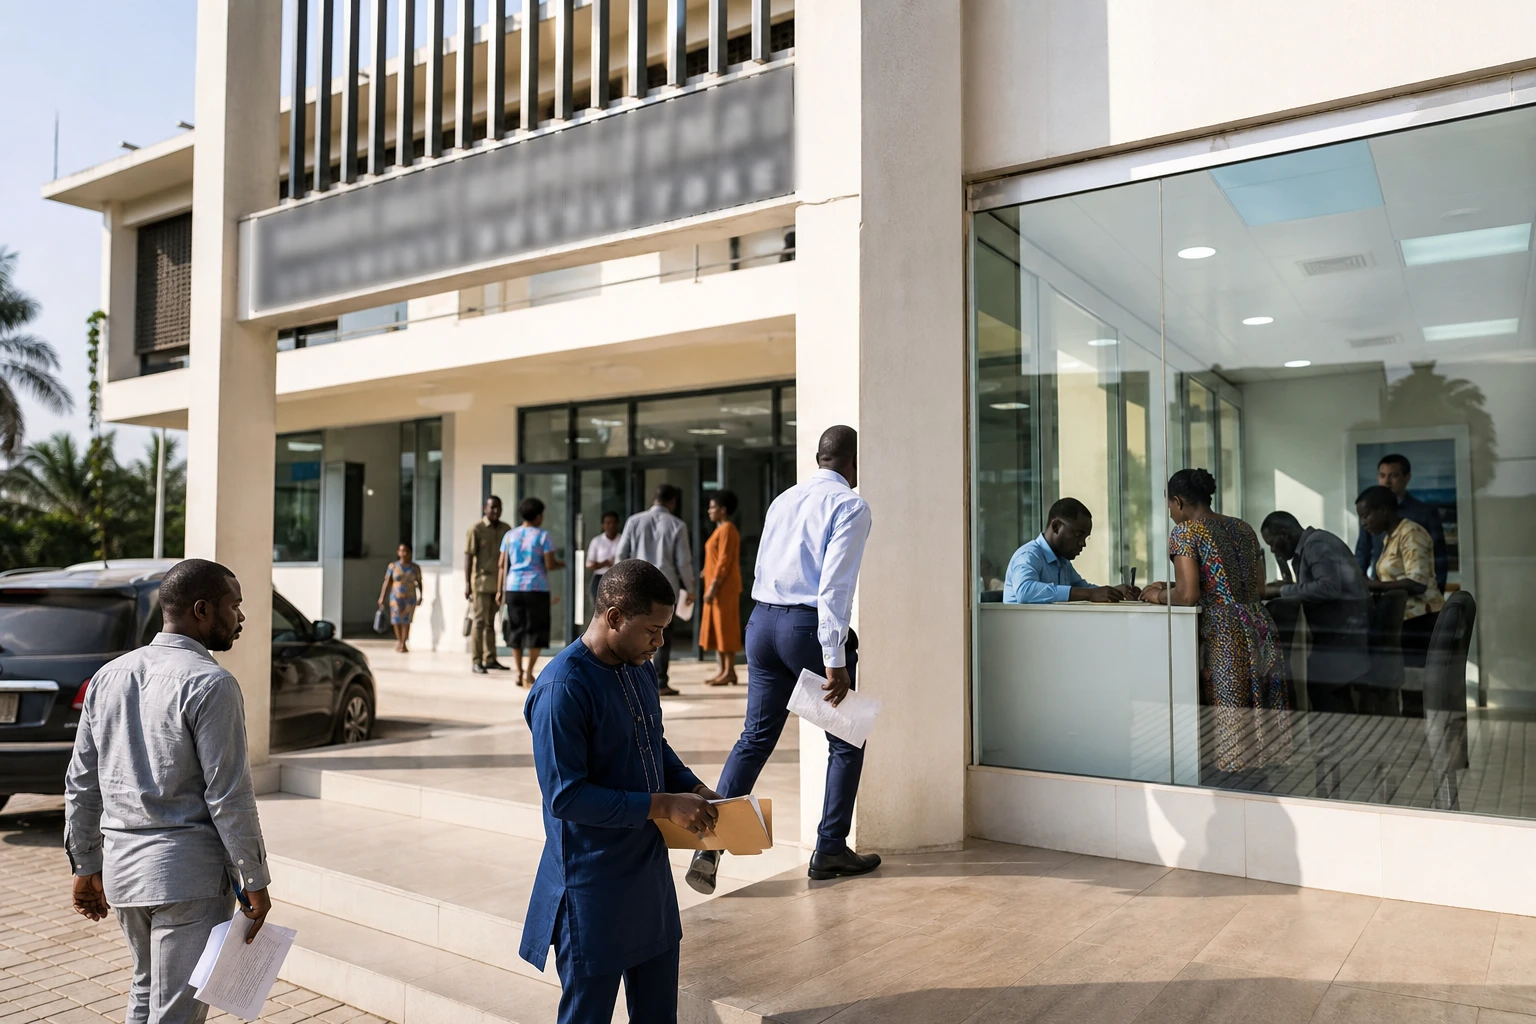
SME finance, a test of method for Cotonou
In Benin, the question is no longer just how many businesses are created. It is also which ones actually make the leap to growth, hire staff and export. In a country where the economy remains largely informal, access to credit is a decisive filter in turning a good idea into a sustainable business.
It is in this context that the European Bank for Reconstruction and Development, the EBRD, has launched its offer for small and medium-sized enterprises in Benin. The institution, which began operating in the country in July 2025, now intends to complement its infrastructure financing with more focused work on SMEs, local banks and advice for entrepreneurs.
A new framework, but familiar obstacles
Benin is not approaching this issue without tools. In May 2025, the Beninese government adopted a national policy for the promotion and development of SMEs for the 2025-2034 period. The Ministry of Small and Medium-Sized Enterprises and Employment Promotion is also overseeing several schemes, including a one-stop shop and mechanisms to support formalisation.
But the underlying difficulty remains the same. The country has a dynamic entrepreneurial base, but it is often poorly structured. The World Bank estimates that 90.1% of Beninese workers are employed in the informal economy, and that the financing gap for MSMEs remains enormous. In this landscape, bank credit does not naturally flow to very small businesses, especially when they lack reliable accounts, sufficient collateral or clear governance.
This is precisely where the EBRD wants to set itself apart. The institution does not just lend. It combines advice, financial structuring and risk-sharing with partner banks. In Cotonou, its management says the aim is to help businesses become “bankable” — able to present lenders with clear applications, stronger management, compliant financial statements and credible business plans.
Beyond credit, the question of capacity
This approach says something important about the Beninese market. Many entrepreneurs are not short of ideas. They often lack the time, tools, structure and networks to speak the language of banks. The EBRD is therefore focusing on practical support: bookkeeping, governance, formalisation, preparing applications, and then introductions to local financial institutions.
This approach aligns with, without replacing, Benin’s public strategy. The government wants to widen access to finance and support the formalisation of informal production units. It sees this as a lever for jobs and for upgrading the productive sector. The EBRD, for its part, is bringing instruments already tested in other regions where it operates, including guarantees on individual loans or portfolios, to free up bank capital and broaden credit distribution.
For Beninese businesses, the key point is that direct financing is not the only answer. An SME can receive a loan and remain fragile if its accounting is poor, its governance unclear or its market too narrow. Conversely, well-targeted technical support can help a company secure larger financing later and then enter a new phase of growth. It is this gradual progress that the EBRD is seeking to accelerate.
Agribusiness, light manufacturing and regional markets
The EBRD is not confining itself to a single sector in Benin. But agribusiness often comes up in its discussions with local stakeholders, alongside light manufacturing and information and communications technology. This choice fits the structure of the Beninese economy: adding more value to local production, processing more raw materials and creating value chains that retain more wealth locally.
Benin also has a clear geographical advantage: its immediate integration into the West African market. In an ECOWAS seeking to enable smoother movement of goods and services, a Beninese SME’s ability to sell beyond Cotonou depends as much on its financing as on its logistics, compliance and capacity to produce consistently. Regional trade is therefore part of the equation, not just a backdrop.
The impact is also social. Women entrepreneurs and micro-enterprises remain among those most exposed to a lack of finance. The World Bank recently noted that Benin is running several programmes to support women’s access to credit, training and mentoring. In this context, the EBRD could become a useful complementary player, provided it does not remain confined to businesses already close to the banking system.
What to watch in the coming months
The real test will not be the launch of the scheme, but its actual reach. How many SMEs will receive useful advice? How many will move from informality to usable accounts? How many loans will local banks actually grant with risk-sharing? And above all, how many Beninese businesses will move up a size bracket and become credible regional players?
For Cotonou, the stakes go beyond a simple financial programme. The country is seeking to consolidate a more diversified productive base, reduce its dependence on poorly protected jobs and turn growth into a denser business fabric. If the EBRD succeeds in connecting advice, finance and skills development, it will become part of that trajectory. Otherwise, it will merely add another service counter to a landscape already crowded with good intentions.



