
 Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
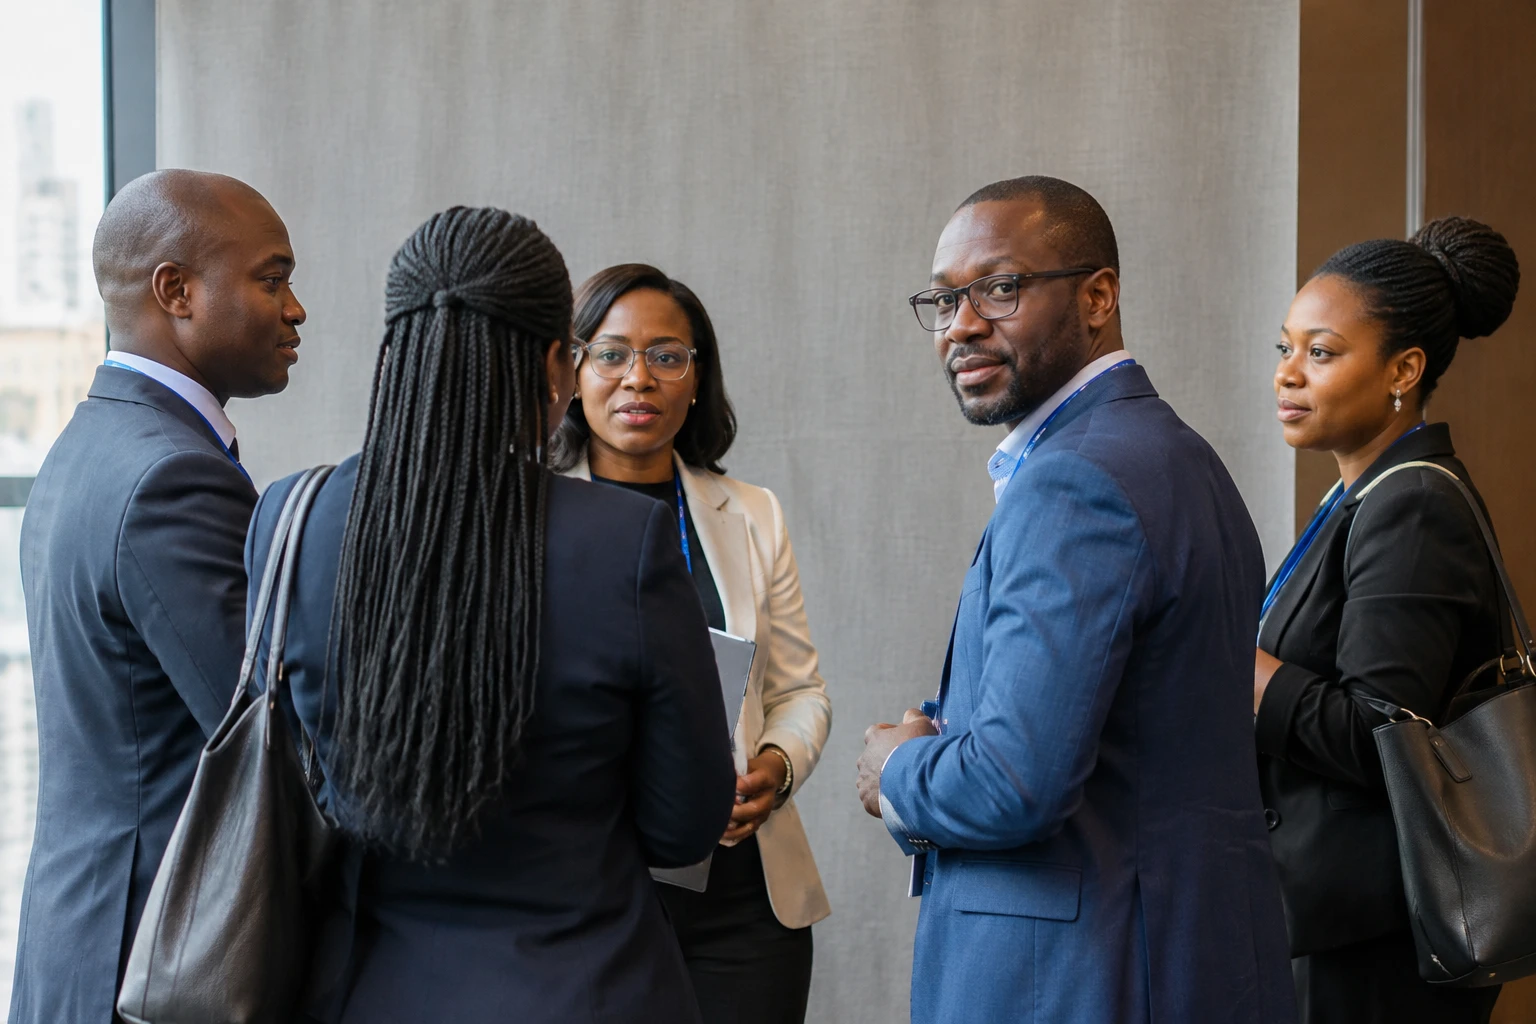
For someone managing their account by phone, a convenient app is not always enough. A blocked transfer, a late reply or a poorly coordinated branch visit can matter more than promises of innovation. It is this everyday reality that now shapes part of the trust between banks and customers in Côte d’Ivoire.
Banking customer relations are evolving across the West African Economic and Monetary Union (WAEMU), which brings together eight countries sharing, among other things, a central bank and a common monetary framework. Digital use is growing, but it does not replace branches, phone calls or human support. The Central Bank of West African States points to both the expansion of digital financial services and the challenges of access, security and service quality.
Customer relations at the heart of discussions in Abidjan
The Francophone Africa Customer Experience Days (JCXAF) were held on 22 and 23 October 2026 in Abidjan. The third edition brought professionals together to discuss the transformation of services and the balance between automation and human interaction, according to information published before and after the event.
On 23 October, Jean-Aimé Nobou, identified as head of Organisation and Customer Experience at NSIA Banque Côte d’Ivoire, took part in a panel devoted to a practical question: how can transformation ambitions be translated into everyday practices? The event programme confirms his presence among the speakers.
The bank champions a simple idea: the customer experience is not limited to a campaign or a new tool. It takes shape through a succession of interactions with customers, whether via the customer relations centre, digital services or the branch network. According to the institution, the complementarity of these channels can help make processes smoother and more accessible.
In a statement provided by the bank, Nobou said that the quality of the relationship is also built through repeated small gestures that can strengthen trust. This quotation expresses the institution’s position; on its own, it does not constitute an independent measure of customer satisfaction.
Digital services do not remove the need to address problems
The challenge extends beyond Côte d’Ivoire’s banking sector. Across WAEMU, phone-based payments, electronic money and other digital services are expanding the ways people can transact. The BCEAO says digital financial services continued to develop in 2024. It also notes the importance of electronic money to financial inclusion in the region.
This development does not mean that all customers have the same devices, skills or internet access. Nor does it guarantee that a digital service will resolve complex requests. A fast interface helps with a simple transaction; a dispute, payment error or identification problem may require a human response and clear follow-up.
For banks, the challenge is therefore to manage the hand-offs between phone, branch and adviser without making customers start their journey again at every step. For individuals, small businesses and traders, service quality is measured by concrete outcomes: understanding fees, getting an answer, tracking a complaint or completing a transaction within a predictable timeframe.
Côte d’Ivoire has also made financial inclusion a public policy priority. The national strategy presented by the authorities includes promoting digital finance, as well as customer protection and financial education. These goals are a reminder that innovation is not judged solely by the number of services available: how well people understand and can access them also matters.
Turning commitments into verifiable practices
NSIA Banque Côte d’Ivoire describes its participation in the JCXAF as an extension of its aim to put the customer at the centre of its activities. The institution says it draws on its teams, customer relations centre, digital tools and branches. These elements describe its set-up, but do not in themselves show response times, complaint resolution rates or differences in access between customer groups.
Several benchmarks would help assess progress: the average time taken to process a request, the proportion of complaints resolved, the availability of digital services and the ease of reaching a member of staff. Regularly publishing such indicators would make it possible to compare promises with results. It would also help distinguish visible improvements from general announcements.
This issue also affects users beyond the big cities. A journey designed around an app may be less suited to someone unfamiliar with digital tools or living far from a branch. Conversely, maintaining phone-based options and in-person service can improve access, provided staff have the necessary resources and cases are transferred properly between departments.
In Yamoussoukro, Côte d’Ivoire’s political capital, as in Abidjan and other regions, trust in financial services depends on this consistency. Commercial banks, electronic money services and WAEMU authorities share a responsibility: to develop accessible solutions without neglecting security, customer information and the handling of disputes.
The JCXAF thus highlighted a challenge shared by Francophone markets in West Africa: making digital transformation a tool that serves users, rather than an end in itself. The next step will not take place only on panel stages, but in how institutions turn these discussions into simpler customer journeys, reliable responses and public indicators of quality.



