Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
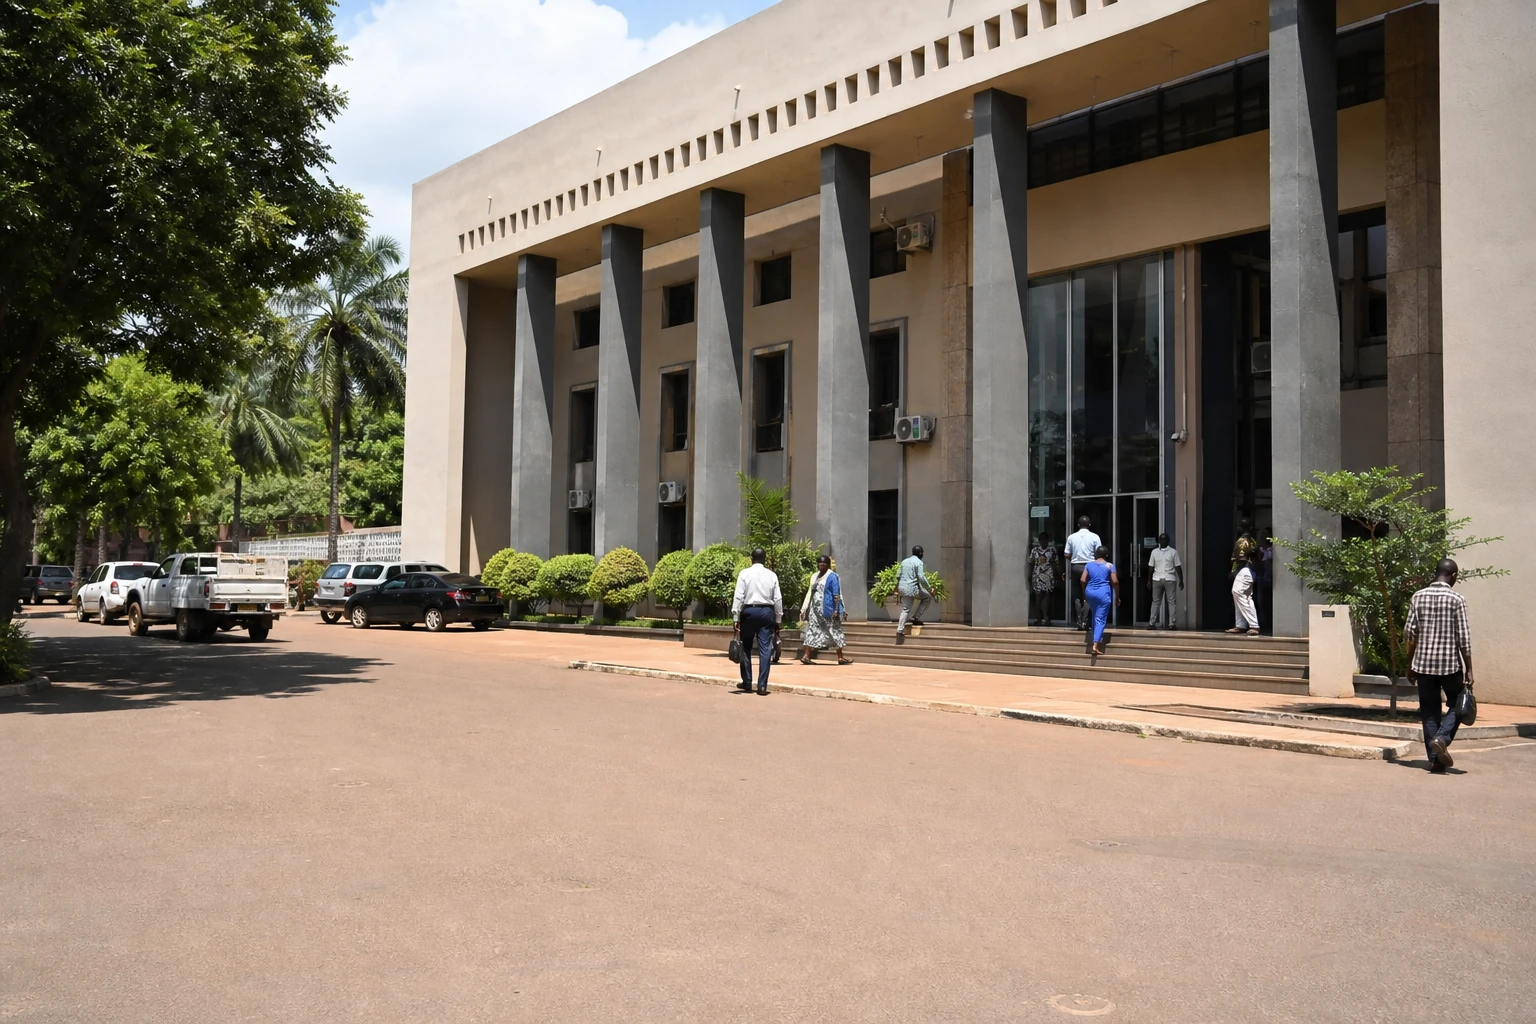
In Bangui, the arrival of a new insurer is about more than opening an office. It directly affects household protection, transport operators’ security and businesses’ ability to absorb a loss. In a still-narrow Central African market, Royal Onyx Insurance now wants to fill that space.
A second player in non-life insurance
Royal Onyx Insurance officially launched operations in the Central African Republic on Friday 2 October 2026, in Bangui. The Cameroonian company will be headed locally by Jules Anicet Backy, a well-known figure in the national insurance sector.
The company plans to offer insurance products known as IARDT. The acronym refers to cover for fire, motor, miscellaneous risks and transport. The offer is also expected to include professional and industrial risks, as well as comprehensive home insurance.
The policies will target individuals, businesses, transport operators, traders and public bodies. They are therefore aimed at several segments of the Central African economy, from household activity to institutional procurement.
“We are first and foremost here to support an economic ecosystem, with IARDT solutions tailored to the realities of businesses, transport operators, traders and households,” said Eudoxie Douya, managing director of Royal Onyx Insurance in Cameroon. She describes the company’s establishment as a long-term commitment to serving the real economy.
According to information available in the directory of the Federation of National African Insurance Companies, SUNU Assurances IARD Centrafrique had until now been among the players listed in the national market. With Royal Onyx Insurance, the Central African Republic now has two non-life insurance companies identified in this professional sector.
A market that remains underserved
The potential appears significant. According to data attributed to FANAF for the 2024 financial year, premiums written in life and non-life insurance represented 0.30% of Central African Republic gross domestic product. In other words, insurance premiums remain low relative to the wealth produced in the country.
This rate puts the Central African Republic among the least penetrated markets in the area studied. Chad recorded a lower level, at 0.19%, according to the same statistical base. The data should nevertheless be treated with caution, as economies where the informal sector plays a major role sometimes record insurance coverage below the level of activity actually carried out.
The market’s structure confirms the scope for growth. In 2024, the non-life segment reportedly accounted for about 90% of Central African premiums, compared with 10% for life insurance. This dominance is explained in particular by the weight of motor insurance and cover linked to property, transport and business activity.
Data reported for SUNU Assurances show 4.284 billion CFA francs in premiums written in 2024, down from 5.061 billion a year earlier. This points to a decline in the output of the main player listed before Royal Onyx Insurance’s arrival. On its own, it does not make it possible to measure potential demand or the proportion of policies actually renewed.
Competition alone will not be enough
The entry of a new operator can widen customer choice. It can also push insurers to improve their pricing, claims-processing times and quality of compensation. However, competition will have lasting effects only if policies remain affordable and easy to understand.
For households, the issue is first and foremost protection for their homes, vehicles and business assets. For companies, insurance can facilitate access to credit and safeguard investment. Transport operators need cover suited to road risks and the constraints of national routes.
Urban areas are not the only ones affected. An offer concentrated in Bangui would leave out traders, producers and transport operators based in other prefectures. Royal Onyx Insurance’s commercial success will therefore also depend on its distribution networks, local partners and ability to handle claims beyond the capital.
Trust will be just as important. In markets where insurance remains little used, customers judge it in practical terms: the speed of payouts, the clarity of exclusions and the availability of agents. Cover that is difficult to understand or claim against can discourage new policyholders, even when the need exists.
A sector regulated across Central Africa
The Central African market operates within the framework of the Inter-African Conference on Insurance Markets, or CIMA. This organisation harmonises the rules applicable in several African countries and, together with the Regional Insurance Supervisory Commission, oversees insurers’ practices and the protection of policyholders.
The National Insurance Directorate of the Central African Republic works with CIMA bodies. Its responsibilities include ensuring compliance with the regional code, supervising the market and safeguarding the interests of policyholders and beneficiaries.
This regional framework matters for Royal Onyx Insurance. The company is arriving from Cameroon, another CIMA member state. Its establishment can therefore draw on common rules, while still having to respond to the economic and administrative realities specific to the Central African Republic.
Closer ties between neighbouring markets could also facilitate cover for cross-border activities. Road transport, trade and regional projects require mechanisms capable of managing risks that extend beyond national borders.
What the market will need to watch
The coming months will show the real scale of this arrival. Observers will need to track the number of policies taken out, the company’s presence beyond Bangui and the share of small businesses in its portfolio.
The market will also need to monitor insurers’ ability to develop simple products suited to irregular incomes and the needs of informal activities. Digitalisation could reduce some costs, but it will not replace human support in a country where access to financial services remains unequal.
For the Central African Republic, the challenge is therefore about more than going from one non-life insurer to two. It is about turning low penetration into tangible economic protection. Competition will provide an impetus. Policyholders’ trust, the quality of regulation and a strong territorial presence will determine what comes next.