Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
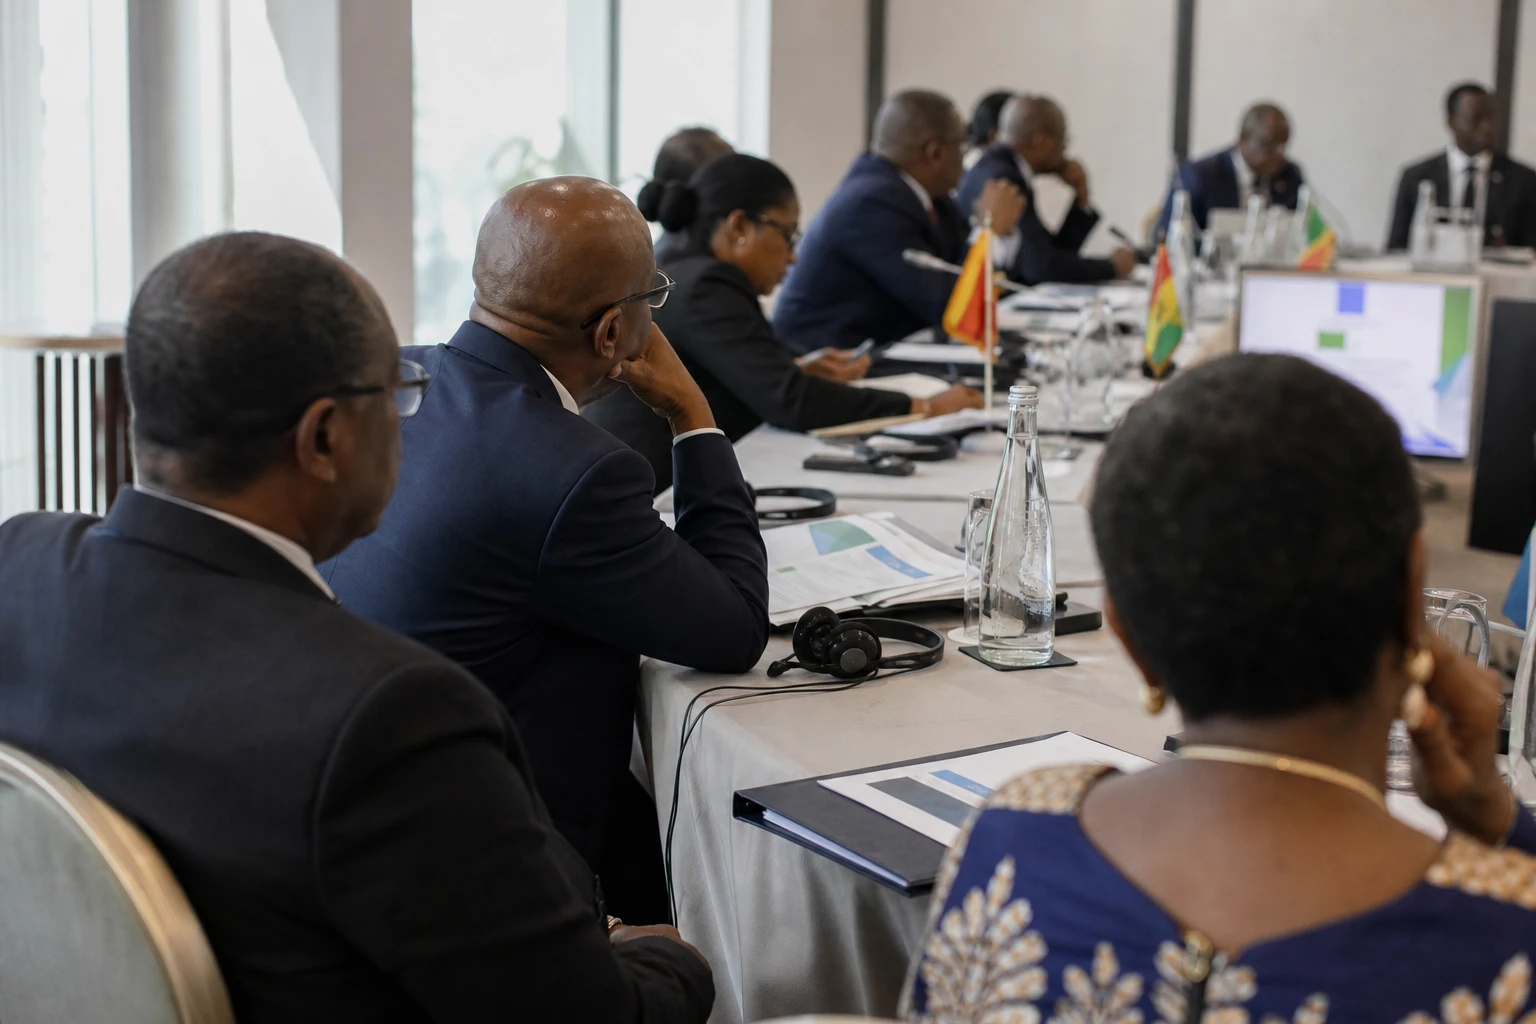
As banking changes, training must keep pace
In Abidjan and across the country, the jobs market increasingly demands more specialised skills than a diploma alone. In finance, the most sought-after roles centre on data, electronic payments, compliance, cybersecurity and information systems. The shift is clear. It is forcing training institutions to move beyond a rigid focus on courses and towards producing candidates with skills that businesses can actually use.
In Côte d’Ivoire, this pressure has particular resonance. The country has embarked on a far-reaching reform of technical and vocational education, including the drive to regulate private technical and vocational education institutions, the growing role of the National Council of Professional Branches and a stated commitment to bringing schools closer to businesses. The government has also announced plans to increase the share of learners in technical education to 10% by 2030 and build 100 new institutions.
A long-standing gap made more visible by digitalisation
The diagnosis is not new, but it has become more acute as financial services have gone digital. Ivorian banks want data analysts, digital marketing specialists, IT auditors, operational risk controllers, compliance experts and people able to work on electronic payments. The BCEAO has also launched the Interoperable Instant Payment System Platform, available 24 hours a day, seven days a week, with banks and financial institutions in the WAEMU asked to connect by 30 June 2026, before the deadline was subsequently extended. This confirms that the region’s financial infrastructure is changing rapidly, and that skills must keep pace.
Against this backdrop, the sectoral workshops held in Grand-Bassam form part of a process already established by the Ivorian state. In December 2025, the National Council of Professional Branches and its digital platform were launched to reduce the gap between training and employment. In March 2024, the Joint Steering Committee had already presented sectoral studies on the skills needs of several industries. Banking, insurance, microfinance and the stock market are central to this framework.
The breaking point is simple: Ivorian technical schools continue to produce graduates suited to traditional occupations, but the banking sector is increasingly hiring people with a hybrid skill set. It wants candidates able to read a database, secure a digital transaction, manage compliance risk or help a customer use a mobile service. Without this adjustment, young graduates face a labour market that cannot absorb their specialisations.
What this means for young people, banks and the Ivorian state
For young people, the stakes are immediate. The government has cited hundreds of thousands of job, internship and training opportunities in 2026 through the National Employment and Recruitment Fair, while the World Bank approved the SIRA programme in June 2026. The initiative, with $642 million allocated for its initial phase across several countries, is intended to help more than 900,000 young Ivorians access training better aligned with the jobs market, according to the World Bank. The message is clear: the issue is no longer just access to training, but its economic relevance.
For banks, the response is already under way. When a bank recruits digital, compliance or risk specialists, it is not just looking for people to carry out instructions. It wants employees able to protect sensitive data, automate tasks and support the growth of digital services. This is a way to safeguard the sector’s transformation, but also to work around a local skills shortage by training people in-country or hiring from outside the national pool.
For the state, the challenge goes beyond a simple update to the curriculum. It affects the entire chain: student guidance, course content, the role of businesses, certification, job placement and graduate tracking. The ministry responsible for technical education has already announced the revision or development of 25 diploma programmes in partnership with the CNBP. It has also stressed that the school-business approach is a pillar of the reform. In other words, the question is not how to train more people, but how to train them for the right jobs.
The implications extend beyond Côte d’Ivoire’s borders. In West Africa, digital banking is expanding rapidly, driven by WAEMU, the BCEAO and the growth of digital financial services. When a country such as Côte d’Ivoire reforms its courses to support this shift, it is in effect testing a regional model: technical training capable of supporting the industrialisation of services, not just goods. The next test will lie in concrete decisions: revised standards, partnerships with banks, courses covering data and cybersecurity, and the ability to turn workshops into useful qualifications.