Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
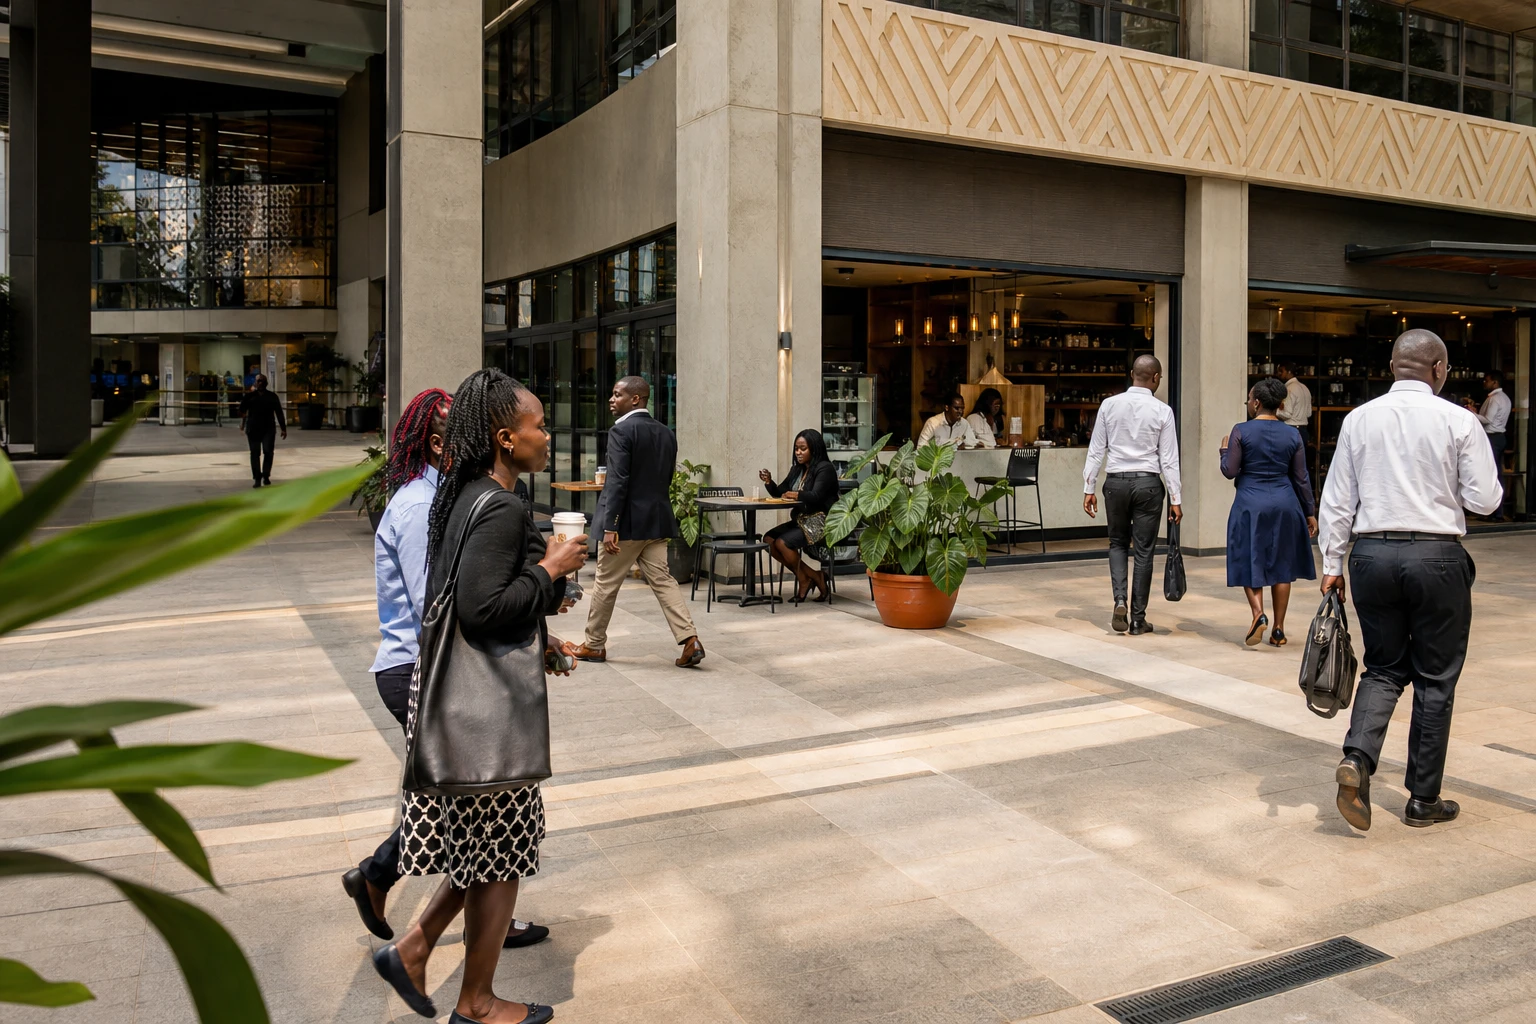
In Nairobi, coffee is no longer confined to hotel counters or international offices. It is becoming a place to work, meet and consume on a daily basis. The opening of a new venue in the Upper Hill business district illustrates this transformation of the Kenyan market.
Nairobi attracts brands betting on urban habits
On 1 October 2026, Italian chain Café Barbera opened its first outlet in Kenya, in the Altura Building in Upper Hill. The district is home to multinational companies, professional services firms, diplomatic missions and a working population with significant purchasing power. Reports published in Kenya on the opening state that the outlet operates every day from 7am to 11pm.
The brand serves coffee-based drinks as well as pastries, pizzas, pasta and several dishes inspired by Italian cuisine. Some of its offerings also draw on local specialities. The choice reflects a straightforward strategy: attract international customers without turning away from Kenyan food habits.
Nairobi is now the brand’s 23rd market worldwide. Its African network already includes outlets in Ghana, Somalia, Djibouti, Morocco and Mauritius. Café Barbera’s official list of locations also mentions a second outlet announced in Nairobi.
This expansion does not mean the market is a foregone conclusion. Rather, it shows that international chains see room in the Kenyan capital for hybrid formats. These venues combine fast food, speciality coffee, remote working and business meetings.
Domestic consumption remains low, but is rising
Kenya remains one of Africa’s major coffee producers. Yet only a small share of its output is consumed locally. The country mainly exports green coffee, while domestic consumption is growing more slowly than production and the reputation of its growing regions.
Data from the Agriculture and Food Authority nevertheless show steady change. Kenyan coffee consumption rose from 1,577 tonnes of green coffee equivalent in the 2019-2020 financial year to 1,656 tonnes in 2020-2021, and then to 2,062 tonnes in 2023-2024, according to figures published in national agricultural reports. Data from Kenya’s Agriculture and Food Authority document, in particular, the increase recorded at the start of this period.
Kenya’s coffee development and marketing strategy aims to accelerate this trend. It focuses on young people, students, hotels, tourist areas and urban cafés. The goal is to make coffee a product consumed more widely in the country, rather than a crop destined only for overseas markets.
The challenge remains considerable. The Kenyan agriculture ministry’s strategy document estimates per capita consumption at about 0.036 kilograms. This is far below the level in several other producing countries. Kenya’s coffee strategy links this low level to several factors: consumption habits, prices, access to outlets and limited local processing.
Recent changes are nevertheless visible in the major cities. Coffee shops are multiplying in business districts, shopping centres and university areas. They cater to increasingly diverse demand, driven by young professionals, entrepreneurs and a growing urban middle class.
An issue that goes beyond Nairobi’s cafés
For Kenyan producers, rising domestic consumption can create more value within the country. Coffee sold roasted, ground or served in a café generates more activity than a product exported only in raw form. This value chain involves roasters, transporters, baristas, processors and food-service workers.
However, the benefits are not automatically shared among all stakeholders. Growth concentrated in Nairobi’s wealthier districts would initially benefit property owners, major chains and consumers with spending power. To reach producing regions, links between cooperatives, local processors and distribution networks would also need to be strengthened.
This question is part of wider discussions within the East African Community, or EAC, the regional organisation that includes Kenya, Uganda, Tanzania, Rwanda and Burundi, among others. Member states produce coffee, but their markets remain fragmented. Smoother movement of processed products could support regional businesses and reduce dependence on overseas outlets.
The G25 Summit of African coffee-producing countries, held in Dar es Salaam on 21 and 22 February 2025, put this transformation at the heart of its discussions. Participants called for African consumption and value addition on the continent to increase. The declaration issued after the meeting aims, in particular, to raise Africa’s share of global coffee consumption from 12.3% to 30% by 2030. Official G25 Summit documents also identify job creation for young people and women as a priority.
Tanzanian and African media have confirmed that discussions also covered processing, research and investment in value chains. A report on the summit published in Tanzania highlights producing countries’ determination to gain greater control over the value created after harvest.
The next battle will be over local value
Café Barbera’s arrival in Nairobi gives international visibility to the rise of urban cafés. It is, however, only one link in a much broader shift. Kenya’s real challenge will be to connect this new demand with farmers, cooperatives and local processing businesses.
Market growth will also depend on whether brands can offer prices that suit the incomes of a broader customer base. A model confined to business districts could remain profitable, but would not fundamentally transform coffee culture in the country.
In the coming years, several indicators will therefore be worth watching: the number of cafés opening outside Nairobi, volumes of coffee roasted locally, income paid to producers and the share of young people in consumption. Kenya already has a recognised raw product. It is now seeking to build a stronger domestic market and a processing industry more firmly rooted in the regional economy.