Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
A mine restart that also depends on the balance sheet
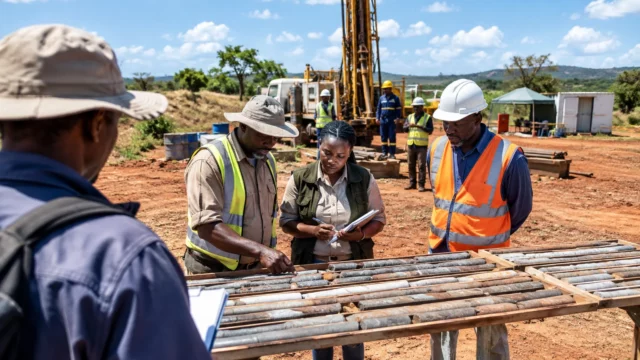
At Karonga, in northern Malawi, the return of a mine is measured not only in tonnes extracted. It is also measured by its ability to stick to a timetable, secure its inputs and convince financiers it can last. That is precisely the stage Kayelekera has reached, with the uranium project active again after a long period on care and maintenance.
The issue extends beyond the mine site. Malawi, a landlocked country and founding member of SADC, is increasingly looking to mining to diversify an economy still dominated by agriculture and foreign currency generated through exports. In this context, Kayelekera is not just another asset: it is one of the few large-scale industrial operations capable of generating revenue and jobs, and of increasing the state’s stake in the economy.
What Lotus is seeking to secure
On Thursday 23 July 2026, Lotus Resources detailed a financing package to support Kayelekera’s ramp-up. The structure includes an A$60.1 million share issue, an A$35 million bond issue and a US$30 million facility backed by an offtake agreement with Mercuria. The announced total therefore comes to about A$95 million before costs.
The move comes after several weeks of operational pressures. In the spring, the mine was hampered by a technical incident, followed by disruptions to supplies of sulphuric acid, a reagent essential to processing uranium ore. In June, Lotus even temporarily suspended production while it repaired equipment and secured the acid supply chain.
This vulnerability is not new. When operations restarted in 2025, the group was targeting a rapid ramp-up, with first production followed by a move to full production in 2026. Yet the group’s own half-year report shows that progress remains uneven: acid constraints have already weighed on production, while investment in the acid plant and connection to Malawi’s power grid remain central to stabilising costs.
Why the timetable has slipped
The problem comes down to a simple equation: producing more quickly requires reliable inputs, robust equipment and cash on hand. When sulphuric acid is in short supply, the entire chain slows down. When equipment fails, restarting operations takes time. And when working capital is tight, the project has to balance the pace of industrial activity against financial caution. Lotus acknowledges that completing the site’s upgrades still depends on finishing work on the acid plant and the electricity connection.
The group is nevertheless seeking to retain control over marketing. Under the agreement announced with Mercuria, the Swiss trader will finance part of the project and may market up to 3 million pounds of uranium over 30 months, but Lotus says it will retain control over the choice of end buyers. For the company, this matters as much as the amount raised: it secures outlets while keeping open its relationships with utilities already involved in the project.
The uranium market, meanwhile, is more favourable than it was a few years ago. Cameco put the long-term price at US$95.50 a pound as at 30 June 2026, compared with a spot price of US$85.00 on the same date. Lotus is relying on this improvement to argue that a well-funded restart can quickly create value. But a favourable market cannot make up for a plant that keeps stalling.
What Malawi stands to gain — and what it must monitor
For Lilongwe, the stakes are tangible. The government owns 15% of Kayelekera and receives a 5% royalty on revenue. The broader mining framework also provides for local benefit-sharing through community development agreements. On paper, Kayelekera could therefore contribute to the budget, foreign currency earnings and some benefits for the Karonga district.
But the benefits will be neither automatic nor evenly distributed. For the central government, the priority is to see the promised revenue and jobs materialise. For communities nearby, the main concerns are access to energy, roads and subcontracting opportunities, as well as social commitments that are honoured over time. For small local businesses, the challenge is gaining access to the supply chain of a project that needs transport, maintenance, security and specialist services.
The precedent set in July 2024 is a reminder that industrial announcements are not enough. At the time, the Malawian government was already presenting mining as a lever for economic transformation, with promises of jobs and foreign currency. A year later, the focus is no longer on the inauguration, but on consolidation. For the country and for African and international investors, the real question is now this: can Kayelekera move from being a symbolic restart to becoming a sustainably productive asset?
The answer will matter beyond Malawi. In SADC, where several states are seeking to capture more of the value added from their resources, this case illustrates a clear trend: mining projects are no longer judged solely by their geology, but by the strength of their supply chains, financing and benefit-sharing agreements. In the short term, the next steps to watch are the effective implementation of the financing, followed by the mine’s ability to maintain its promised pace without another disruption.