Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
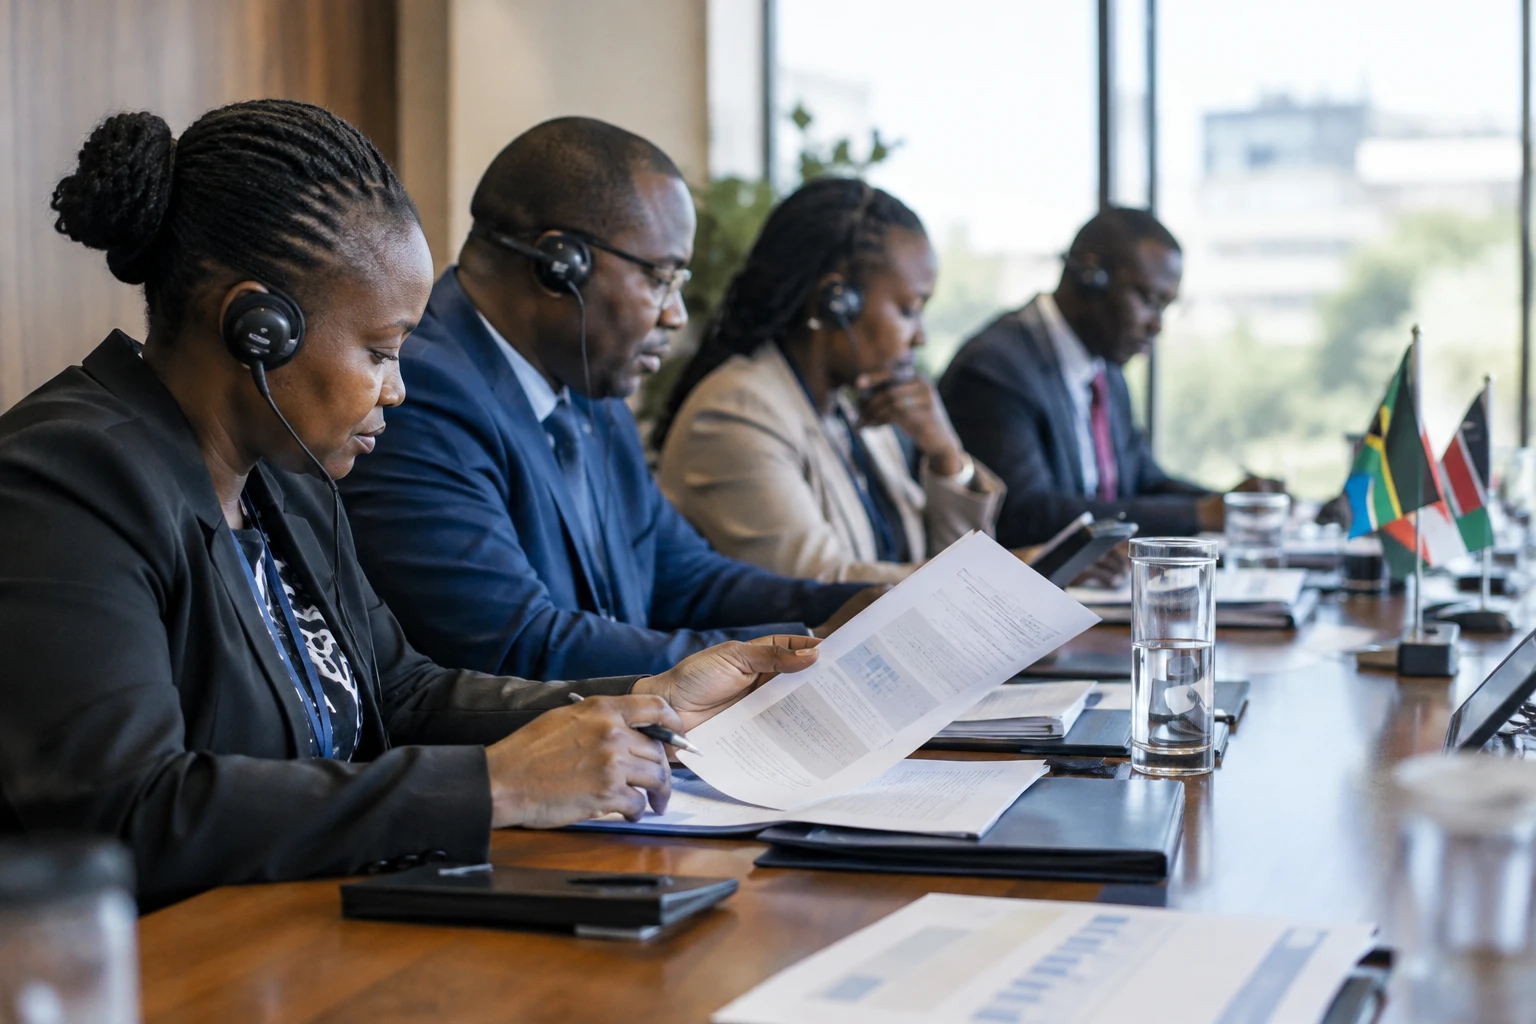
When a multinational declares profits in several countries, the question is simple: where is the corresponding tax actually paid? In Kenya, a new regulatory step gives the tax authority a way to claim a share of the minimum tax on profits made in the country.
Nairobi seeks tax due on local profits
On 18 September 2026, Kenya published regulations setting out how its minimum top-up tax will apply. The companies concerned must notify the Kenya Revenue Authority (KRA), Kenya’s tax authority, of their status by 17 November at the latest. This 60-day deadline is for an initial notification, not payment of the tax.
The measure applies to Kenyan entities belonging to a multinational group with consolidated revenue of at least €750 million in at least two of the previous four financial years. The threshold therefore targets large groups, not Kenyan businesses as a whole.
The rule provides for a top-up tax when a group’s effective tax rate on its profits in a jurisdiction is below 15%. It does not replace Kenya’s ordinary corporate income tax. Rather, it seeks to limit situations in which deductions, incentives or profit shifting push effective taxation below this floor.
Kenya’s parliament enshrined this principle in the 2024 Finance Act, with implementation scheduled to begin in 2025. The 2026 regulations set out the practical details, including notifications and returns. Filing and payment deadlines come later and are separate from the 17 November deadline.
A global reform, national choices
Kenya is part of the second pillar of the international tax agreement developed under the auspices of the OECD and the G20. Designed for groups with revenue exceeding €750 million, the mechanism aims to establish a minimum effective tax rate of 15% in every jurisdiction where they operate.
But implementation depends on national laws. For Nairobi, the challenge is to collect locally the top-up tax due on profits made in Kenya, rather than leave another jurisdiction to claim that revenue under international rules. This choice strengthens the KRA’s role, but also requires detailed accounting data and an administration capable of checking complex group structures.
The timetable comes as Kenya seeks to strengthen domestic revenue and finance spending without increasing its reliance on borrowing. The practical implementation will determine the measure’s yield, however: the minimum rate alone does not guarantee that every group will pay more. The calculations set out in the rules take account of several factors, including covered taxes and certain exclusions linked to substantial economic activity.
Balancing public revenue and economic appeal
For the state, more effective collection could expand the resources available for public services and investment. For the companies concerned, the reform adds compliance obligations: identifying group entities operating in Kenya, consolidating tax information by country, and meeting notification and filing deadlines.
The government must also balance two objectives. It wants to curb strategies that artificially shift profits while preserving Kenya’s appeal as an investment destination. The effects will therefore depend on the calculation rules, the KRA’s oversight and how existing tax incentives interact with the top-up tax. It would be premature to present the reform as revenue already secured.
For the population, the impact will be neither immediate nor uniform. Any additional revenue would feed into the public budget, but its effect would depend on the amounts actually collected and spending decisions. Multinational groups are directly targeted; small local businesses do not fall within the measure’s revenue threshold.
A shared issue in East Africa
The reform comes amid regional economic ties across East Africa, where economies are linked by trade and investment. Kenya is a member of the East African Community (EAC), which brings together several countries in the region. Tax coordination matters, since significant differences in rules can influence where groups report their profits and invest.
The debate goes beyond the EAC, however. African organisations and tax justice networks have repeatedly highlighted the cost of illicit financial flows and tax base erosion practices. These estimates cover a range of phenomena and should not be confused with revenue lost solely to multinational tax avoidance. The figure of $23.2 billion in annual losses for Africa, sometimes cited for this component, is based on separate estimates and methodology.
Kenya’s measure thus highlights a central question for the continent: how can countries ensure that profits generated by economic activity also contribute to the revenue of the country where that activity takes place? The next test will be practical: whether groups report correctly, whether the KRA can verify the calculations, and how much revenue is actually collected. The notification due by 17 November 2026 will open this phase, but will not in itself prove that the measure is generating revenue.
Kenya’s parliament documented the introduction of the top-up tax as part of the 2024 Finance Act. The 2026 implementing texts then set out its scope and notification timetable. The parliamentary report on the 2024 Finance Bill and the analysis of Kenya’s 2026 regulations help put these two steps in context.