Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
A still-narrow market, but already strategic
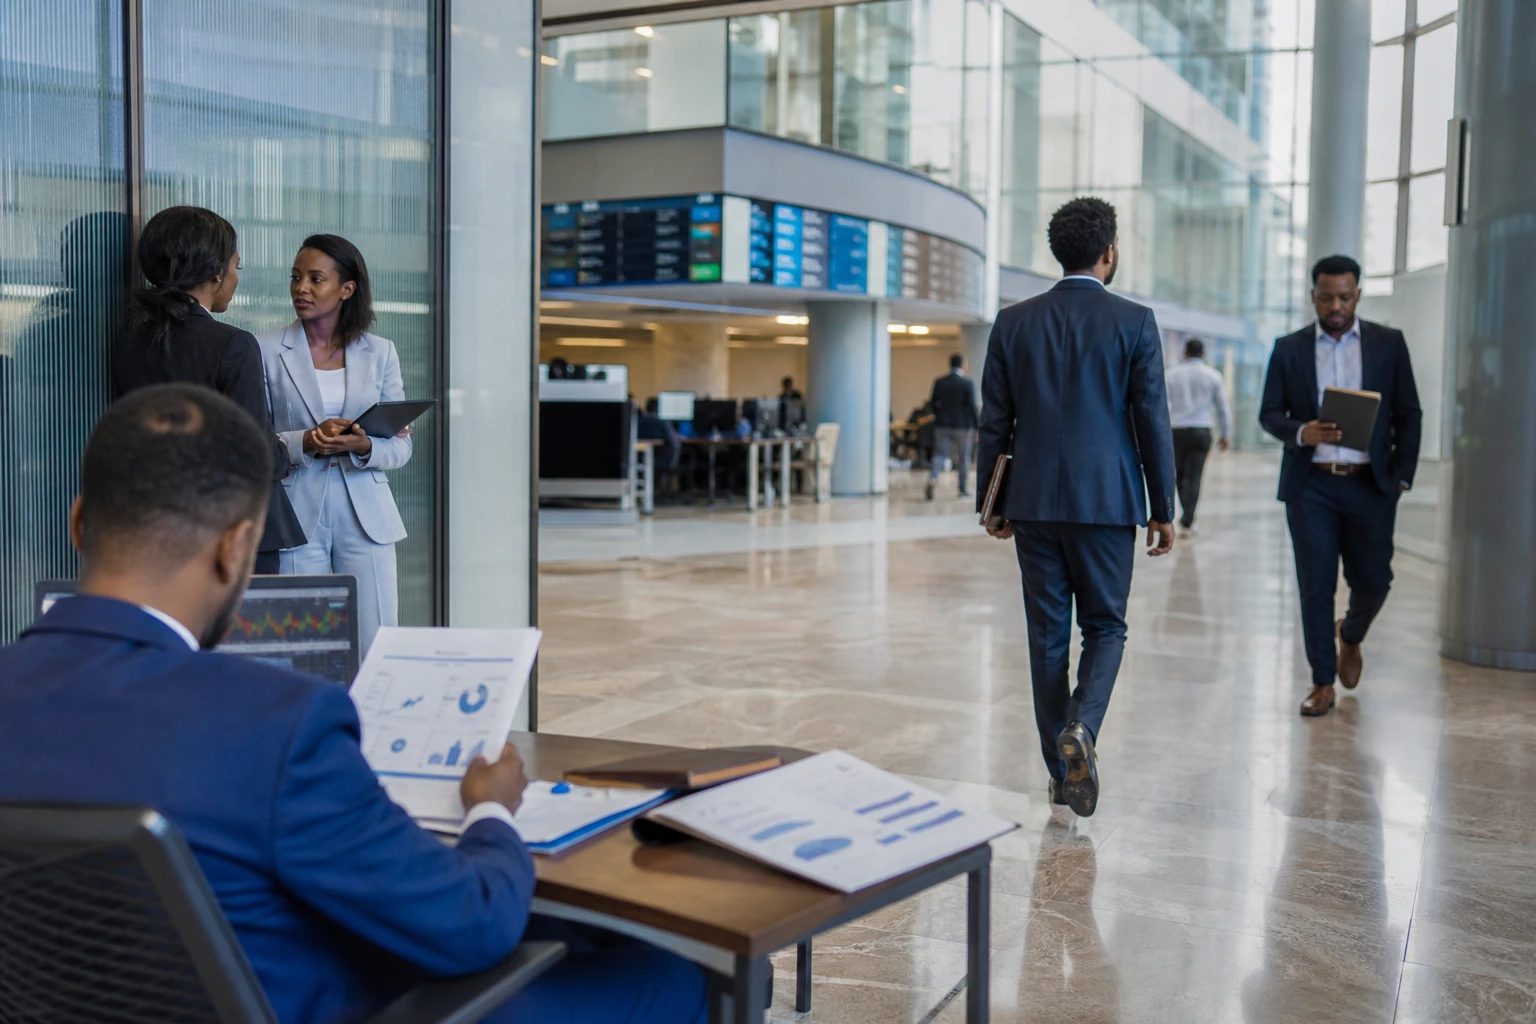
In Addis Ababa, Ethiopian finance is changing its face without much fanfare. The new Ethiopian Securities Exchange, based in the capital, has not merely reopened a trading floor. Above all, it has brought a simple question back to the fore: how can more businesses be financed in a country where bank lending has long remained virtually the only route?
The return of a stock exchange to Ethiopia is part of a broader series of reforms launched since 2024. The government has opened the banking sector to foreign investors, while the National Bank of Ethiopia has eased several foreign-exchange rules to develop the currency market. The ESX is therefore less an isolated event than an instrument of this financial modernisation.
The country was not starting from scratch. The former stock exchange disappeared with the nationalisations of the Derg regime in 1974. The new market, officially launched in Addis Ababa, now aims to play a role that many East African countries have already explored: providing an alternative to conventional bank financing and widening access to capital.
From launch ceremony to first trades
On 10 January 2025, the ESX was launched in Addis Ababa. Wegagen Bank became the first listed company. According to the exchange’s official register, the listing date for Wegagen was 10 January 2025, with listed capital of 6,218,635,000 birr and 14,549 shareholders. Gadaa Bank was then listed on 13 June 2025, with 31,136 shareholders.
On 11 July 2025, the market took another step forward with the opening of trading in government securities and shares. The Ethiopian Capital Market Authority described the day as the official opening of the country’s capital market. The ESX, for its part, noted that it had already been supporting the interbank money market since 2024.
In practice, the launch remains cautious. Official documents show that the ecosystem is still small, with a limited number of listed companies and market members at the start of the operational phase. The exchange also acknowledged in its 2024-2025 annual report that technical capacity and training still needed to be scaled up to support new participants.
This caution is hardly surprising. Capital markets cannot simply be decreed into existence. They are built through listing rules, trained intermediaries, clear financial reporting and a sufficiently broad investor base. This is precisely the foundation the authorities are seeking to establish, with support from public- and private-sector players.
What the exchange changes for the state, banks and businesses
For the Ethiopian state, the stakes are clear. An active exchange allows public and private sources of financing to be diversified. Treasury bills can be traded more widely, helping the government raise funds without relying exclusively on the banking system. The market thus becomes a tool for budget financing, as well as a signal of confidence to investors.
For businesses, the benefit is even more tangible. A stock market can provide long-term capital, whereas banks often favour shorter-term loans. This is crucial for private banks, large service companies and, eventually, industrial or logistics groups able to publish accounts and meet transparency requirements.
But the benefits will not be immediate for everyone. In an economy where most activity remains informal, listed finance will initially be relevant to structured businesses, banked employees and urban savers. In Addis Ababa, the signal is strong. In the regions, access to information, bank accounts and investment services remains more limited. The access gap could therefore be replicated if financial education does not keep pace.
The authorities are aware of this. In 2026, the National Bank of Ethiopia reiterated that foreign-exchange reform was intended to develop the currency market and facilitate transactions by authorised banks. This matters for the exchange because a capital market cannot thrive in an environment of acute foreign-currency scarcity and overly rigid administrative allocations.
An Ethiopian reform with implications beyond the country
The Ethiopian case is of interest across East Africa. Ethiopia is already a demographic and economic heavyweight in the region, and Addis Ababa is also home to the African Union headquarters. When a country of this size finally establishes a modern stock market, the significance extends beyond the local financial centre. The development is being closely watched across the IGAD region, which encompasses the Horn of Africa and the Rift Valley.
Its continental significance is twofold. First, the ESX shows that a capital market can emerge in an economy long centred on the state and banks. Second, it is a reminder that African financial integration advances not only through major treaties, but also through very tangible infrastructure: central securities depositories, electronic platforms, clear regulation and trained intermediaries.
The most important question remains whether the market can scale up. Future listings, a larger number of intermediaries, the quality of financial information and public participation will show whether the ESX becomes a genuine financing market or merely a symbol of reform. For now, Addis Ababa has mainly laid the foundations for a new financial architecture. The work is only just beginning.