Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 Zambia
 Zimbabwe
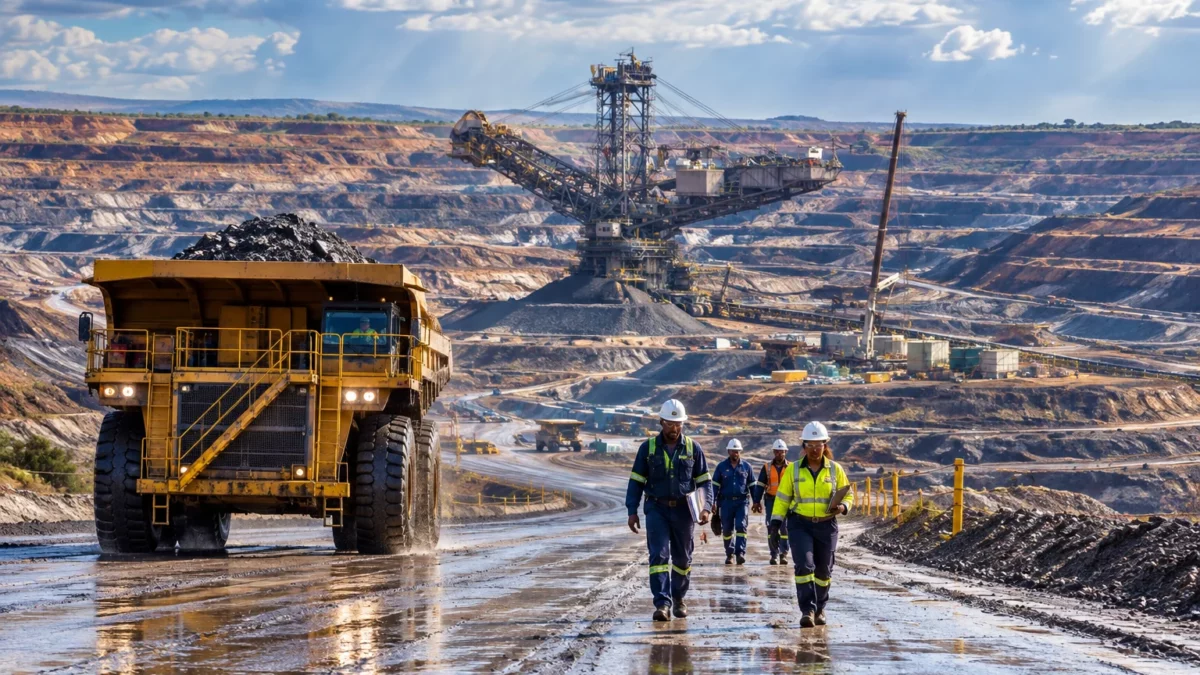
A metal can be plentiful on the market one year and scarce the next. For platinum, this expected reversal shows how dependent southern African mines have become not only on factories and motorists, but also on investors’ choices.
A region at the heart of global supply
South Africa dominates platinum mine production. It accounted for around 70% of global output in 2024, according to the United States Geological Survey. Zimbabwe is also an important producer. Together, the two countries place a significant share of supply in the Southern African Development Community, or SADC, a regional organisation bringing together the states of southern Africa. SADC highlights the economic weight of minerals produced in the region and their importance for employment. USGS data on South African platinum production and the role of minerals in the SADC economy shed light on this regional issue.
Platinum is used to make catalytic converters, which limit certain emissions from combustion-engine and hybrid vehicles. It is also used in jewellery and industrial activities, including chemicals, refining and glass production. Purchases of bars, coins and investment funds add financial demand, which can sometimes tip the market’s annual balance.
Investors driving the forecasts
In its first projections for 2027, published on Wednesday 18 November 2026, the World Platinum Investment Council (WPIC) forecasts a global deficit of 279,000 ounces. A troy ounce is equivalent to about 31.1 grams. A deficit means expected demand would exceed new supply, requiring market participants to draw on existing stocks.
The contrast with 2026 is stark. The WPIC now estimates that the market could post a surplus of 468,000 ounces this year, up from the 265,000 ounces forecast in September. The council says the revision is mainly due to larger-than-expected investment outflows. The September analysis had already linked the expected surplus to weak investment and jewellery demand. The forecasts published by the WPIC on 18 November and Reuters’ report on the September estimate make it possible to track how these projections have changed.
For 2027, the WPIC expects investors to return as net buyers, purchasing 513,000 ounces, after forecast net sales of 398,000 ounces in 2026. Purchases of bars and coins would rise by 55% to 448,000 ounces. The council attributes this expected move to the prospect of higher prices and improved product availability. It remains a forecast, however, not an observed decision.
Projections for physical demand are less uniform. The WPIC forecasts a 4% increase in industrial demand to 2.66 million ounces, notably driven by chemicals and refining. By contrast, automotive demand is expected to fall by 5% to 2.813 million ounces, while jewellery demand is set to continue declining. The growth of fully electric vehicles reduces the need for catalytic converters, although combustion and hybrid engines remain a major market.
Constrained mines, stocks under pressure
The expected rise in purchases and industrial demand would not be matched by a comparable expansion in extraction. The WPIC forecasts total supply to increase by only 1% in 2027, while global mine supply would fall by 1%. Recycling would therefore make a greater contribution to the market balance. Mine estimates nevertheless vary according to the countries and periods considered: national figures should not be confused with the global total or with a revisable annual forecast.
In South Africa, expected additional volumes from Northam and Platreef, Ivanhoe Mines’ project, would not be enough to fully offset declining output from older mines. Platreef’s expansion also depends on new infrastructure: the company plans to complete the processing plant for its second phase in the fourth quarter of 2027. This is an industrial milestone, not a guarantee of immediate full-capacity production.
In Zimbabwe, the WPIC’s scenario depends in particular on the processing of material already mined but still awaiting treatment at Zimplats. These two trajectories are a reminder that supply is not simply a matter of how much ore lies underground: the age of facilities, processing capacity and investment schedules also matter. For producers, higher prices can support revenues, but they do not remove technical constraints or the time needed to bring new capacity on stream.
The forecast deficit would bring above-ground stocks down to 1.813 million ounces, or just under three months of global demand at the end of 2027, according to the WPIC. This reserve acts as a buffer when production and purchases do not coincide. But, the council says, the expected surplus in 2026 would not be enough to rebuild stocks, which are considered already low after several years of deficits. Stock levels are market estimates, not a comprehensive physical inventory.
A signal to watch for Pretoria and SADC
For South Africa, whose capital is Pretoria, the stakes go beyond international prices. Platinum supports an economic chain encompassing mines, processing, suppliers and associated jobs. A price recovery could boost producers’ revenues, while a sustained decline in automotive demand or operational difficulties would weigh on sites and their communities. The effects would therefore differ for mining groups, employees, contractors and areas dependent on the industry.
Across SADC, the platinum market illustrates the exposure of exporting economies to global cycles and to decisions by investors who may be far removed from mining areas. It also raises the question of how much value is created in the region: increasing extraction is not the only answer when processing capacity and end-use markets are changing. The transition to electric vehicles is reducing some outlets, while industrial uses could open up others.
The scenario remains conditional. The WPIC assumes, in particular, that tensions in the Middle East will ease, potentially calming inflation and expectations of higher interest rates that have weighed on investment in precious metals. The next checkpoint will be the council’s revised 2027 forecasts, due on 3 March 2027. Until then, investment flows, recycling and progress at Platreef will help determine whether the forecast deficit materialises.