Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
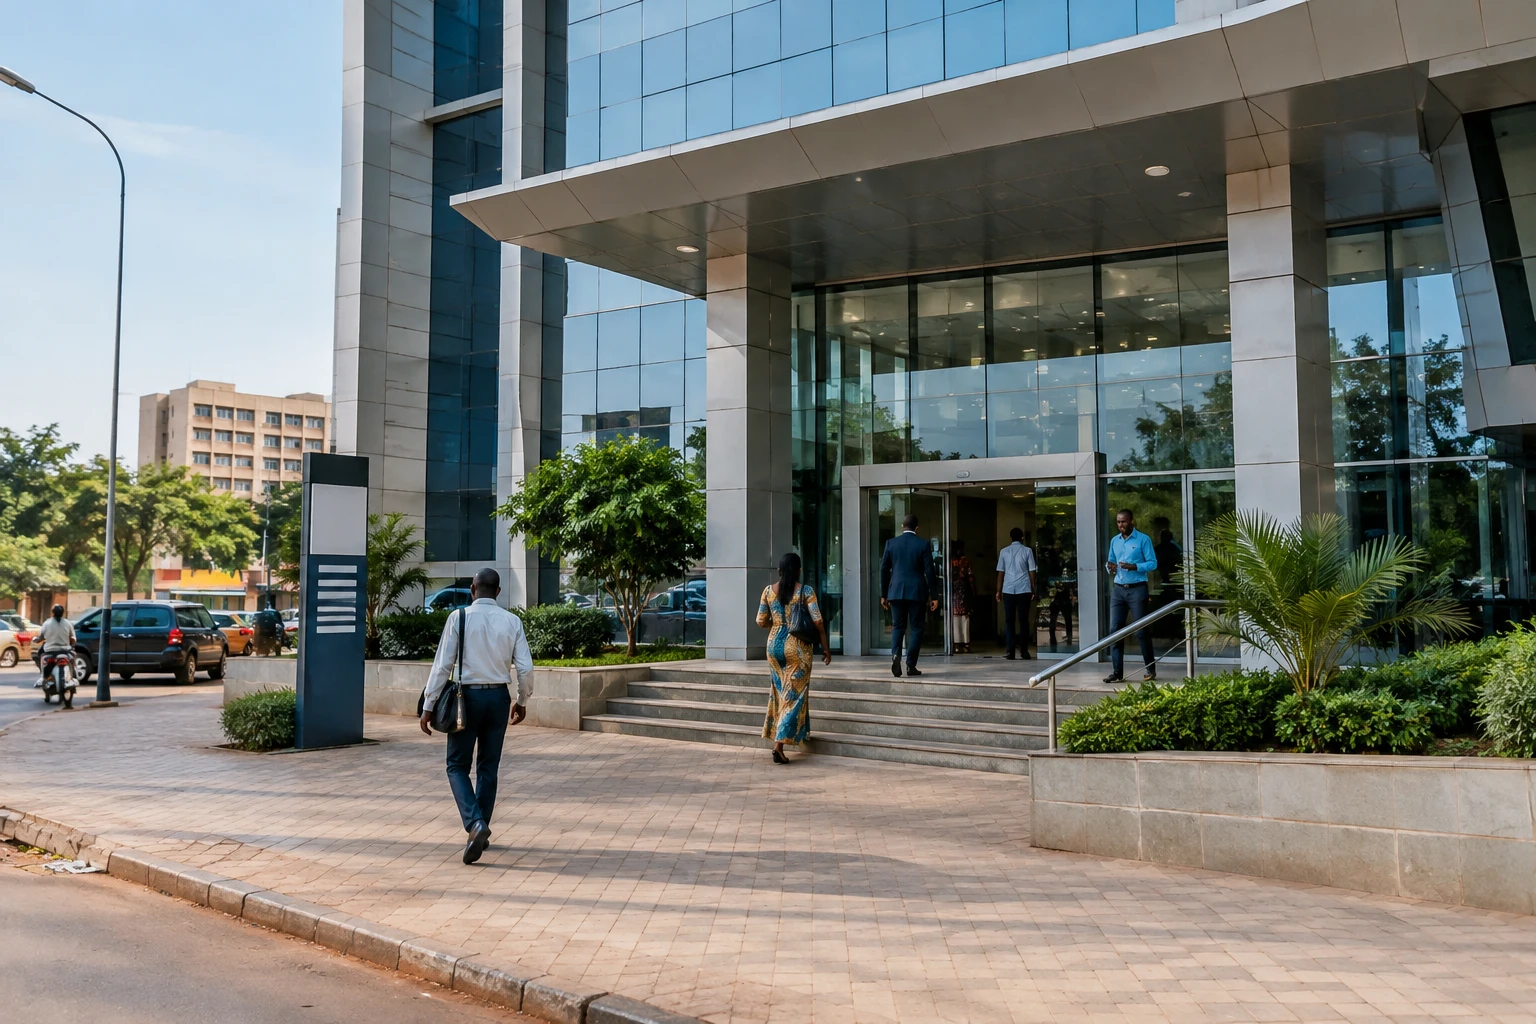
A bank can report rising profits while collecting far more savings than it converts into loans. This is one of the points to watch in the results published by Coris Bank International Burkina Faso for the first nine months of 2026.
A Burkinabè bank at the heart of a regional market
Based in Ouagadougou, Coris Bank International Burkina Faso is listed on the Regional Securities Exchange (BRVM), the common market for countries in the West African Economic and Monetary Union (WAEMU). Its results are therefore of interest to savers and investors far beyond Burkina Faso.
The banking sector operates in a region where deposit mobilisation, access to credit and business financing are major economic issues. A bank’s figures do not, however, show on their own what proportion of financing reaches small businesses, households or activities outside the formal sector. Rather, they offer a guide to the institution’s performance and the way it mobilises its resources.
In Burkina Faso, the bank’s activity also takes place against a national backdrop of public- and private-sector financing needs. For customers, rising deposits may reflect increased deposit collection. For businesses and individual borrowers, the pace of lending is a separate indicator, from which access-to-loan conditions cannot be inferred on its own.
Deposits surge as loans lag behind
As at 30 September 2026, Coris Bank International Burkina Faso’s net profit stood at 62.34 billion CFA francs, according to the bank’s activity report published on 29 October. This represents a year-on-year increase of 17.8%. Net banking income (NBI), meaning revenue from banking activities after interest expenses, reached 116.37 billion CFA francs, up 14.9%.
Pre-tax profit rose more quickly, gaining 23.9% to reach 71.9 billion CFA francs. The bank attributes its revenue growth in particular to improved interest margins and commissions. These developments are reported by the institution; the available data do not make it possible to isolate precisely the contribution of each activity.
Customer deposits reached 2,372.15 billion CFA francs, 26.4% higher than a year earlier. Net loans, meanwhile, rose by 15.2% to 1,386 billion CFA francs. In value terms, the bank said it had collected nearly 496 billion CFA francs in additional deposits, compared with an increase of 183 billion in its loan portfolio.
The ratio of net loans to deposits consequently fell from 64.1% to 58.4%. This ratio describes the share of deposits represented by net loans on the balance sheet; on its own, it does not measure loan quality or the ability of each category of customer to obtain financing. Its decline nonetheless makes it worth monitoring how collected funds are used and the bank’s management choices.
Asset sales complicate the picture on profitability
Another factor calls for caution: Coris Bank mentions financial income from the sale of stakes in some subsidiaries, without specifying the amount for the nine-month period. Such gains can support results, but do not necessarily represent recurring income from banking activities.
The half-year accounts offer a reference point, but do not resolve the uncertainty. At the end of June, the bank had recorded net gains of 6.44 billion CFA francs on fixed assets, compared with 69 million a year earlier. This line accounted for about 13.6% of half-year pre-tax profit. However, it would be inaccurate to attribute all these gains to stake sales: the published breakdown does not allow for this.
Management also reports an improvement in portfolio quality and in the coverage of impaired loans. But the information available as at September does not include detailed ratios that would make it possible to measure the extent of this change. To assess profitability over the long term, investors will therefore need to distinguish growth in recurring income from proceeds linked to asset transactions, while also examining credit risks.
Market prices in strong growth
At the close of trading on 29 October, Coris Bank International Burkina Faso shares were worth 31,900 CFA francs. The BRVM’s official bulletin confirms a 195.92% rise since the start of the year. By comparison, the BRVM Composite index had gained 52.8% over the same period, according to figures released with the results. The price-to-earnings ratio displayed by the BRVM was 15.59.
This stock market surge reflects expectations for the bank, but does not guarantee that profit growth will continue at the same pace. A share price also depends on expectations, trading activity and investors’ assessment of risk. It is not a direct measure of lending activity or its impact on Burkinabè businesses.
The next important assessment will focus on Coris Bank’s ability to sustain recurring income, manage the gap between deposits and loans, and publish more detailed indicators on impaired loans. Across WAEMU, these results also highlight the role of the BRVM: making the performance of companies operating in several economies accessible to regional investors, while requiring sufficiently detailed information to distinguish sustainable growth from one-off gains.