Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
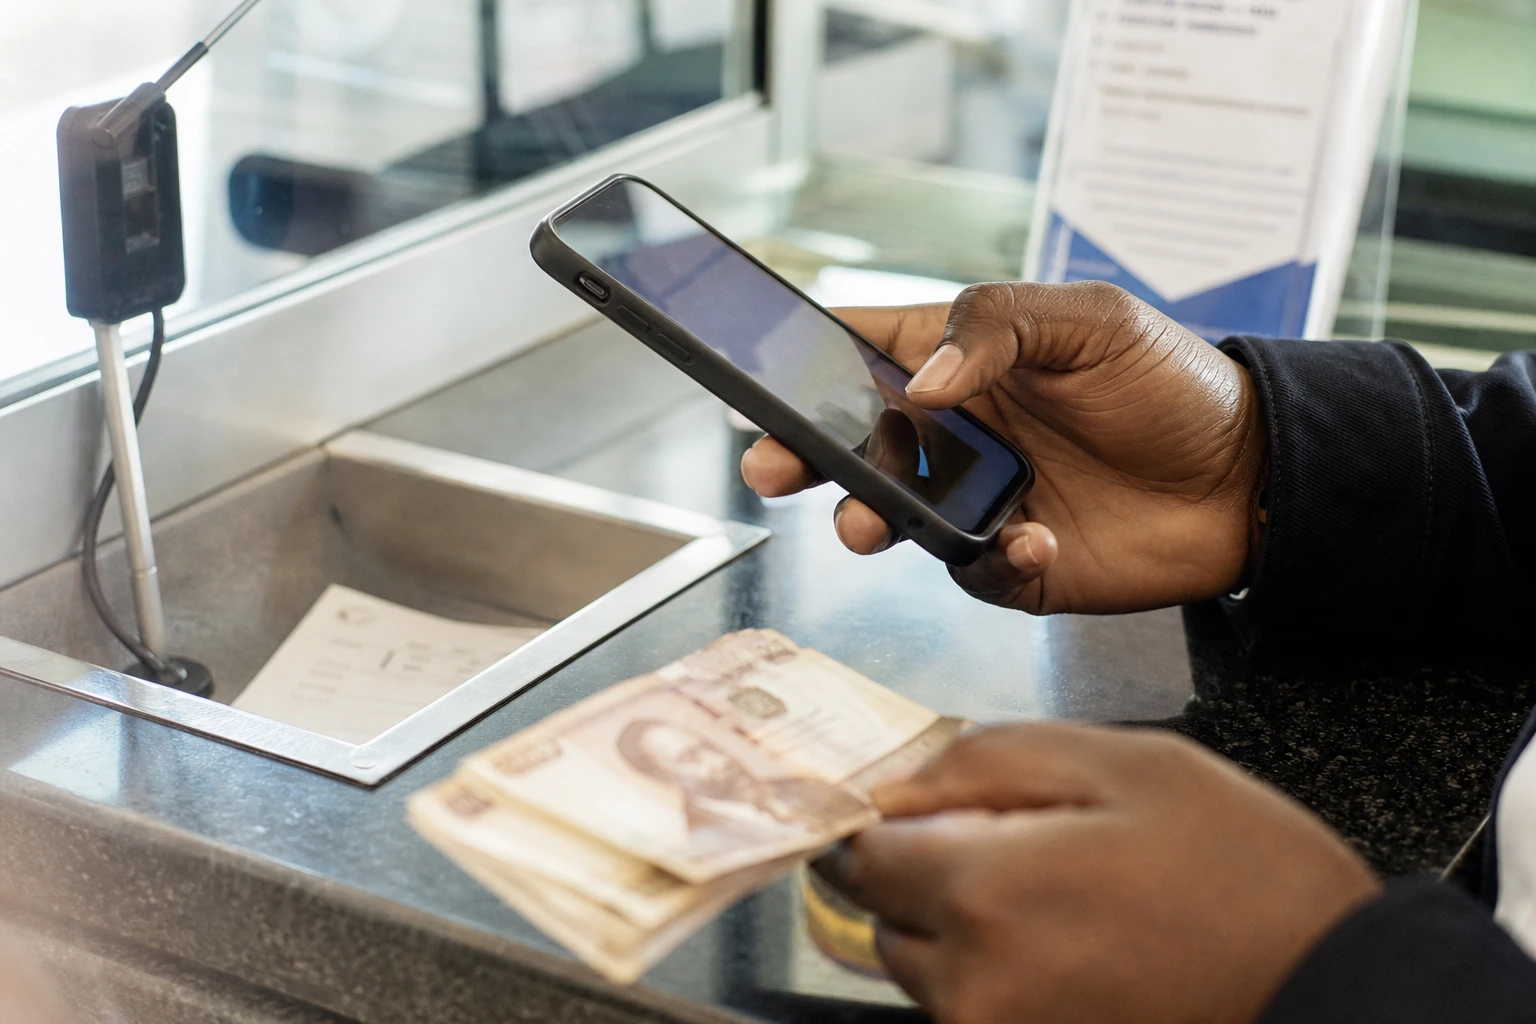
In Kenya’s banks, competition is as much about proximity as it is about digital services
In Nairobi, a bank branch is no longer just a place to meet customers. It is also a commercial foothold, a trusted point of contact and often a gateway to credit for small businesses. In a market where mobile payments have changed how people bank, institutions looking to gain ground must combine a physical presence, digital tools and control over the cost of deposits.
It is against this backdrop that Stanbic Bank Kenya is refining its strategy. The bank, based in Nairobi and part of South Africa’s Standard Bank Group, wants to expand its retail network, strengthen digital distribution and make greater use of agent banking, a widespread model in East Africa in which partner businesses carry out everyday transactions on behalf of customers.
A shift that forms part of Standard Bank’s continental strategy
The move is not starting from scratch. At group level, Standard Bank set out a 2026-2028 strategy in March 2026 based on annual revenue growth of 7% to 10%, a targeted return on equity of between 18% and 22%, and strict capital discipline. The group says it wants to focus its resources on its most dynamic African markets, while supporting a less capital-intensive business through fees, payments and value-added services.
Kenya has a particular place in this strategy. Stanbic Bank Kenya already has a strong base in corporate and investment banking. But the Kenyan market is now pushing major institutions to do more in retail banking, small and medium-sized enterprises and wealth management. This shift is strategic, because retail deposits often cost less than wholesale funding, while fees from cards, transfers and cross-border payments boost non-interest income.
Joshua Oigara, who leads Standard Bank’s East African operations, said Stanbic’s Kenyan network of 40 branches was set to double by 2029. He also set a 2028 target for the subsidiary to become one of the country’s leading private-sector banks. Stanbic Holdings also reported net profit of 13.7 billion Kenyan shillings for the year ended 31 December 2025.
Pressure on margins in Kenya accelerates the race for fee income
The timing is far from incidental. The Central Bank of Kenya kept its benchmark rate at 8.75% at its meeting on 9 June 2026. In recent statements, it has also indicated that the monetary environment remains affected by adjustments to the cost of credit and by international pressures that could weigh on supply chains. For banks, gradual rate cuts and competition for deposits are squeezing net interest margins.
In this context, growth no longer depends solely on the volume of lending. It also depends on the number of active customers, how often they use their accounts and the ability to generate revenue from related services. Private banking, asset management, cards and international transfers are therefore becoming more valuable sources of income. Stanbic clearly wants to position itself across this full chain, from account opening to wealth advice.
The strategy also reflects the realities of the Kenyan market. Major local groups dominate retail banking and remain highly advanced in mobile banking. In a country where financial inclusion has been transformed by agent networks and digital services, foreign and regional banks must prove they can serve customers spread across the country, rather than relying solely on Nairobi’s business districts. Agent banking, in particular, makes it possible to extend that presence without excessively increasing fixed costs.
What this repositioning says about Kenya and East Africa
For urban households, the issue is ease of access. For small businesses, it is the speed of deposits, withdrawals and working-capital credit. For the bank, it is a balance between proximity, technology and profitability. Stanbic’s bet is that a bank can remain competitive by combining physical branches, partner agents and digital tools, rather than pitting these channels against one another.
The regional context matters just as much. Kenya is one of the financial centres of the East African Community, where capital, goods and services circulate. A player such as Standard Bank is seeking a foothold there to connect Nairobi, Kampala, Dar es Salaam, Kigali, Juba and other regional centres. The growth of cross-border payments and business services reinforces this logic. In this framework, Kenya is not just a national market: it is a regional base.
The forthcoming publication of Standard Bank Group’s half-year results will make it possible to assess East Africa’s actual contribution to consolidated performance. This is an important indicator, as it will show whether Stanbic’s expansion in Kenya is a promise of sustainable growth or merely a tactical adjustment in a tighter banking environment. For Nairobi, the stakes extend beyond a single bank: they concern how pan-African groups reinvest in African markets that combine urban density, financial innovation and intense local competition.