Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
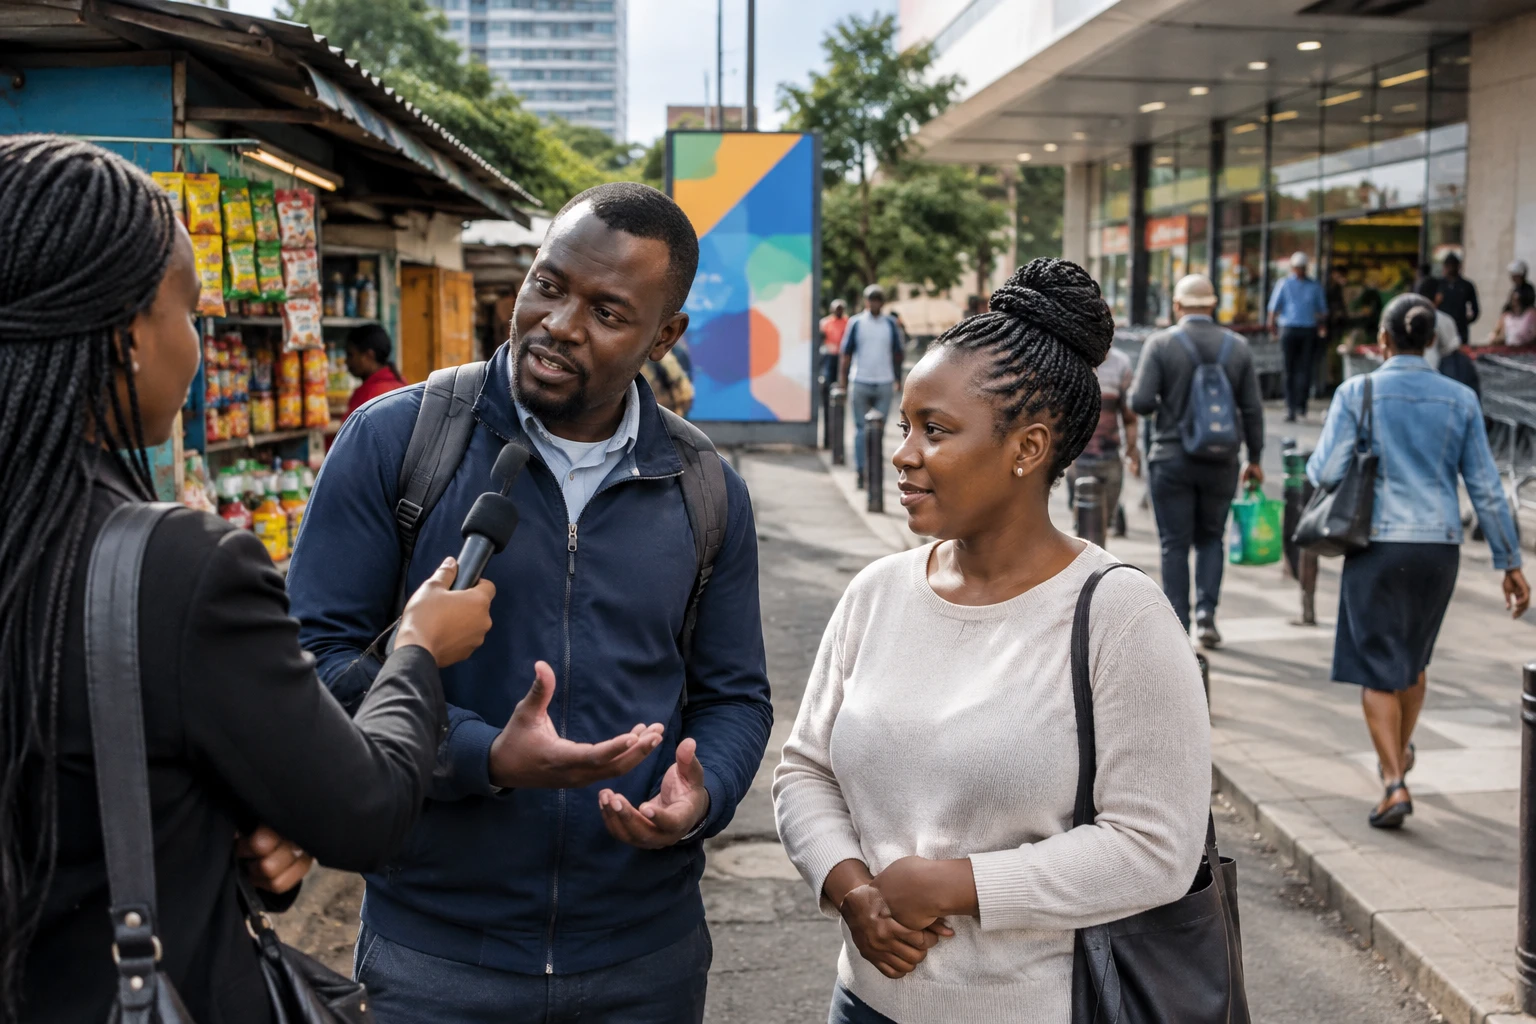
In Nairobi and Kenya’s secondary cities, the chain people shop at also tells a story about changing consumption habits. Quickmart wants to expand its network. But in a market where neighbourhood shops remain essential, opening more stores does not guarantee regular customers or balanced accounts.
A growing market that has not left neighbourhood shops behind
Large chains are competing for a growing share of modern food retail. They do not, however, represent Kenyan commerce as a whole: small grocers, kiosks and open-air markets remain major places to shop. An analysis by the Access to Nutrition Initiative notes that the informal sector still dominates the country’s food market, while supermarkets continue to expand. The assessment of food retail in Kenya thus highlights the importance of distinguishing large-scale retail from the market as a whole.
This distinction also matters when interpreting market shares. According to estimates by Sagaci Research cited in Quickmart’s IPO prospectus, Naivas accounts for 31% of modern food retail, Quickmart 15% and Carrefour 14%. These figures describe a particular segment, not all food purchases made by Kenyans. Other studies produce different estimates depending on their scope and methodology. The market data cited by Khusoko detail this concentration around three chains.
Quickmart targets 125 stores, but the offer will not fund its expansion
On 6 October 2026, Quickmart chief executive Peter Kang’iri set a target of 125 stores over the next four years, up from 72 currently. The company is also targeting annual revenue of $1bn. For the current financial year, it expects sales of about 60bn Kenyan shillings, or nearly $462m, according to information provided by its chief executive.
The announcement comes as the public offer for sale opens, having been launched on 5 October. Quickmart is offering two billion existing shares at 7.50 shillings apiece. The offer is due to close on 30 October, with trading scheduled to begin on 12 November on the Nairobi Securities Exchange, subject to regulatory changes. This is a sale of shares held by a shareholder, not the issue of new shares: the proceeds go to the seller, not directly to Quickmart to build stores. The official Quickmart offer website confirms these terms.
The listing will therefore open up the shareholding to new investors without, in itself, creating a fund to finance expansion. This distinction matters: the company will have to fund its growth from its resources and operations, while meeting shareholders’ expectations. According to its prospectus, Quickmart had 68 stores as at 30 June 2026, then opened four more in July and August, taking its network to 72.
Naivas retains the lead as Carrefour focuses on larger stores
Quickmart faces a larger market leader. Naivas recorded revenue of 113.5bn shillings for the financial year ended in June 2025, according to figures cited in the company’s documentation. Its main shareholder, Mauritius-based IBL Group, said the chain had 114 stores in Kenya as at 31 March 2026, up from 109 a year earlier. IBL’s financial update confirms this growth in the network and in business activity.
Carrefour is pursuing a different model. Operated in Kenya by UAE-based Majid Al Futtaim, the chain has fewer outlets, but its stores are generally larger. Quickmart and Carrefour recorded similar revenues in 2025, according to figures provided in Quickmart’s IPO documentation. A comparison of total sales alone therefore does not tell the whole story: store size, location and operating costs also affect results.
For customers, this competition could widen choice and bring stores closer to new neighbourhoods. Its effects will not be the same everywhere. Locations in urban centres and peri-urban areas offer different prospects from those in secondary cities. And households that prefer to buy in small quantities or shop frequently will often continue to rely on neighbourhood stores.
Cash flow, the key test of expansion
Opening a store requires funding stock, rent, wages and fit-out costs before sales cover these expenses. Quickmart says it sells its stock in less than a month and pays suppliers after 60 days. This gap would allow it to collect some sales revenue before paying for the goods. The chief executive estimates the cost of an opening at between 100m and 150m shillings, with a return on investment expected in 18 to 36 months. These figures and timelines are company estimates, not a guarantee that every store will be profitable.
The sector’s recent history is a reminder of the risks of poorly funded growth. Nakumatt, once a major Kenyan chain, was liquidated after serious difficulties paying its creditors and suppliers. In January 2020, its debt was reported at about 38bn shillings. Business Daily Africa’s report on its liquidation documents the scale of the sums owed. The precedent does not predict Quickmart’s fate, but it underlines the importance of sound cash flow and well-managed supplier payments.
The next stage will therefore play out as much in the accounts as in the aisles: Quickmart will have to maintain rapid stock turnover, choose locations capable of generating sufficient sales, and balance investment with dividends. The 12 November listing will offer a gauge of investor appetite. Across East Africa, the development of Kenyan retail is also of interest to members of the East African Community, where goods, capital and businesses circulate. It remains to be seen whether the expansion of large chains will sustainably strengthen supply without displacing the network of shops that continues to serve much of the population.