Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
Results that extend beyond Kenya’s banking sector
In Nairobi, the half-year results of a major banking group never tell only the story of a company. They also shed light on how quickly credit is flowing, household confidence and the role neighbouring markets play in Kenya’s economic balance. In Equity Group’s case, the picture is even clearer: the group’s centre of gravity remains in Kenya, but an increasing share of its momentum now comes from East Africa and the Democratic Republic of the Congo.
This shift matters for Kenya, but also for the East African Community, the regional platform that organises a large share of the bloc’s trade, capital flows and integration ambitions. In a context in which East Africa remains one of the continent’s most dynamic sub-regions, the performance of an institution such as Equity shows where demand, margins and risks are concentrated.
Results driven by deposits, loans and the region
In the first half of 2026, Equity Group reported net profit of 45.5 billion Kenyan shillings, up 32% year on year. Profit before tax rose 39% to 57.8 billion shillings. Net banking income increased 25% to 124.9 billion shillings. These figures come from the interim financial statements published in Nairobi on 19 August 2026.
Growth was driven first by net interest income, up 17% to 69.3 billion shillings. Non-interest income also made up a larger share of the total, at 44.5% of net banking income, compared with 40.8% a year earlier. In other words, the group is becoming a little less reliant on the traditional business of turning deposits into loans. It is generating more income from commissions, services and related activities.
The balance sheet also grew. It stood at 2.16 trillion shillings, up 20%. Customer deposits rose 21% and the loan book 19%. At the same time, non-performing loans fell to 9.5%, from 13.7%, while the cost-to-income ratio improved to 48.6%. Together, these figures suggest a larger business that is also more disciplined.
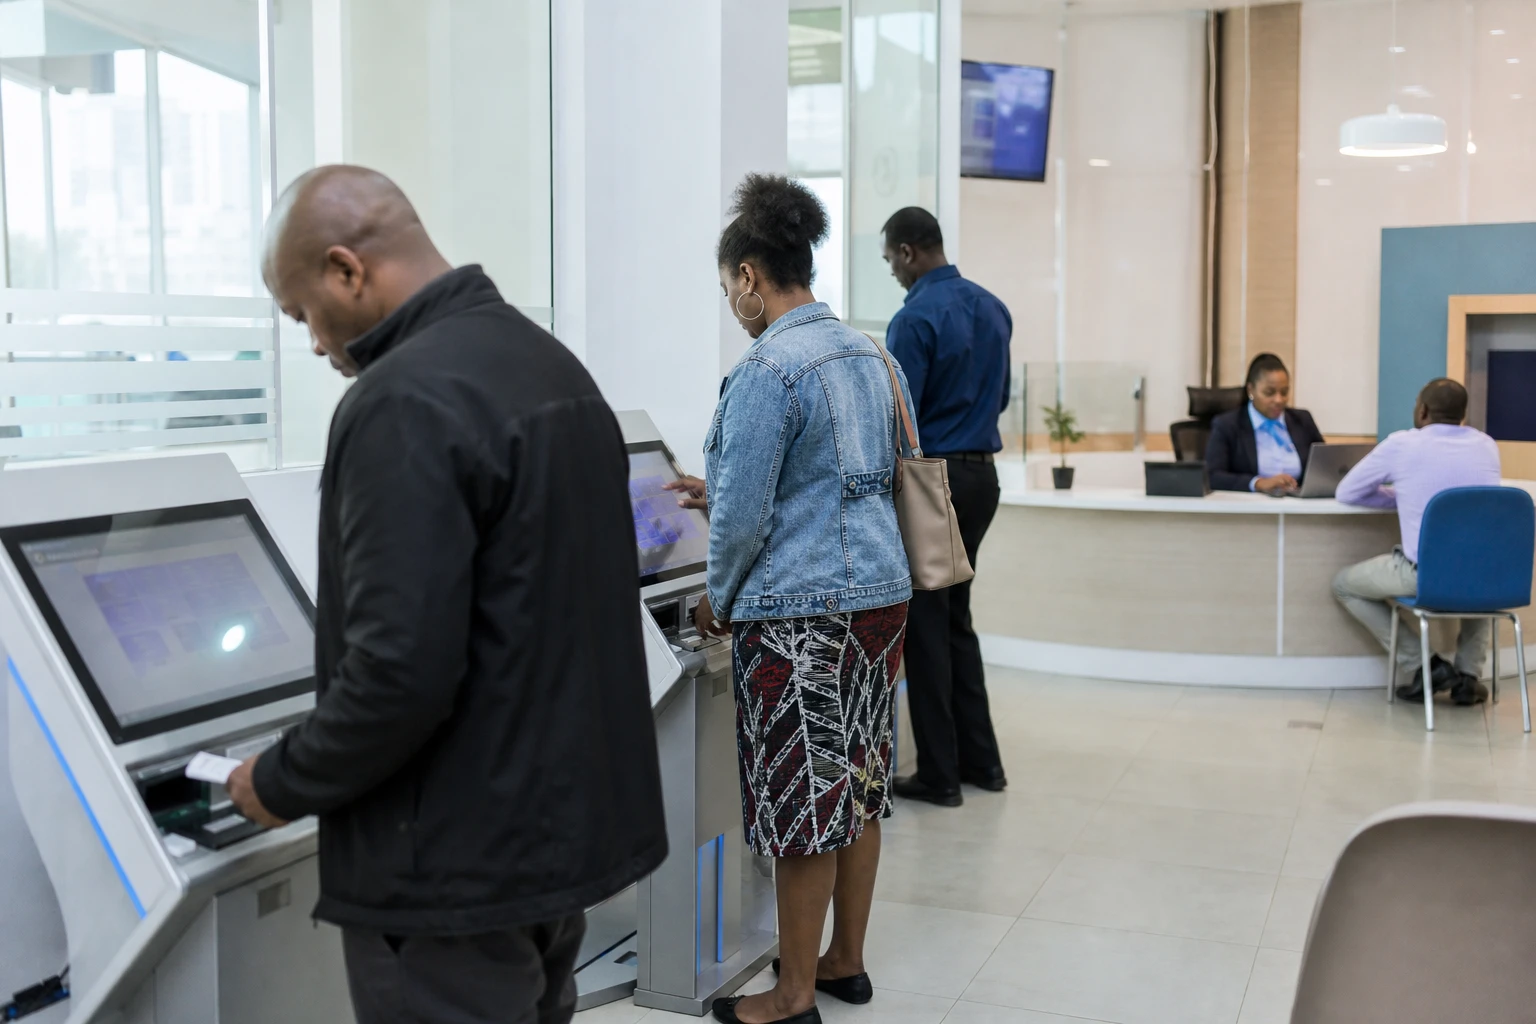
The group is also highlighting a digital shift that is now well advanced. According to its communications, 98.3% of transactions take place outside branches and 89.7% are conducted through digital channels. For an institution with a strong presence in retail banking and among small businesses, this changes its cost structure and processing speed. It also affects access to services for customers far from major urban centres.
The growing weight of regional subsidiaries
The real change, however, is evident in the geographical distribution of profits. Regional subsidiaries accounted for 42% of the group’s banking profitability and 47% of its banking revenue over the period. They also represented 51% of deposits, 54% of loans and 52% of the group’s banking assets. This is a major strategic shift for a bank founded in Kenya and long seen as highly domestic.
The differences between markets are striking. In the Democratic Republic of the Congo, Equity BCDC’s net profit rose 30% to 11.8 billion shillings. In Tanzania, it climbed 82% to 2 billion. In Rwanda, net profit increased 12% to 2.9 billion. Uganda and South Sudan are also part of this network, enabling the group to spread its revenue across several economies rather than rely on a single national cycle.
This diversification has a clear regional rationale. East Africa and neighbouring countries continue to record growth rates above the African average. The ECA estimates that East Africa remains one of the continent’s fastest-growing sub-regions, with growth of around 5.8% in 2026, while the AFDB says the region can maintain this trajectory if financing is better directed towards productive investment. The IMF, for its part, forecasts 4.9% growth for Kenya in 2026.
What this says about Kenya and the regional economy
For the Kenyan authorities, these results have implications beyond the banking market alone. They confirm that some of the growth of domestic financial groups now comes from their ability to support regional trade, cross-border SMEs, insurance and digital payments. Nairobi’s economic fabric no longer operates in isolation. It extends towards Kampala, Kigali, Dar es Salaam, Goma, Juba and beyond.
For customers, the stakes are more tangible. Digitalisation reduces queues, widens access to services and can lower some costs. But it also increases reliance on technological infrastructure, network quality and cybersecurity. A more digital bank is faster. It is also more vulnerable to technical disruptions and processing errors. Equity says it has invested in AI and core systems; this puts competition on the ground of reliability as much as on price.
The group also stresses its focus on small and medium-sized enterprises. It says it has strengthened its leadership in SME financing in Kenya. This is central in a country where small businesses account for a large share of urban and informal employment. When credit flows more freely, stocks, transport, supplies and wages are often the first to benefit.
A continental trend to watch closely
Across Africa, the Equity case illustrates a broader trend: the continent’s financial groups are building regional models that combine banking, insurance, payments and digital services. This movement is accompanying the economic integration advanced by the African Continental Free Trade Area, although logistical, regulatory and monetary obstacles remain significant. Regional champions are seeking to capture growth where it is generated, not only where their headquarters are located.
What happens next will depend on two key factors. First, Kenya’s ability to sustain solid growth without undermining purchasing power or private-sector credit. Second, the stability of the markets where Equity has established a presence, particularly Tanzania, the DRC and Rwanda. If these economies maintain their momentum, the group could continue shifting its growth centre away from Nairobi, while keeping its decision-making, regulatory and financing base in the Kenyan capital.