Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
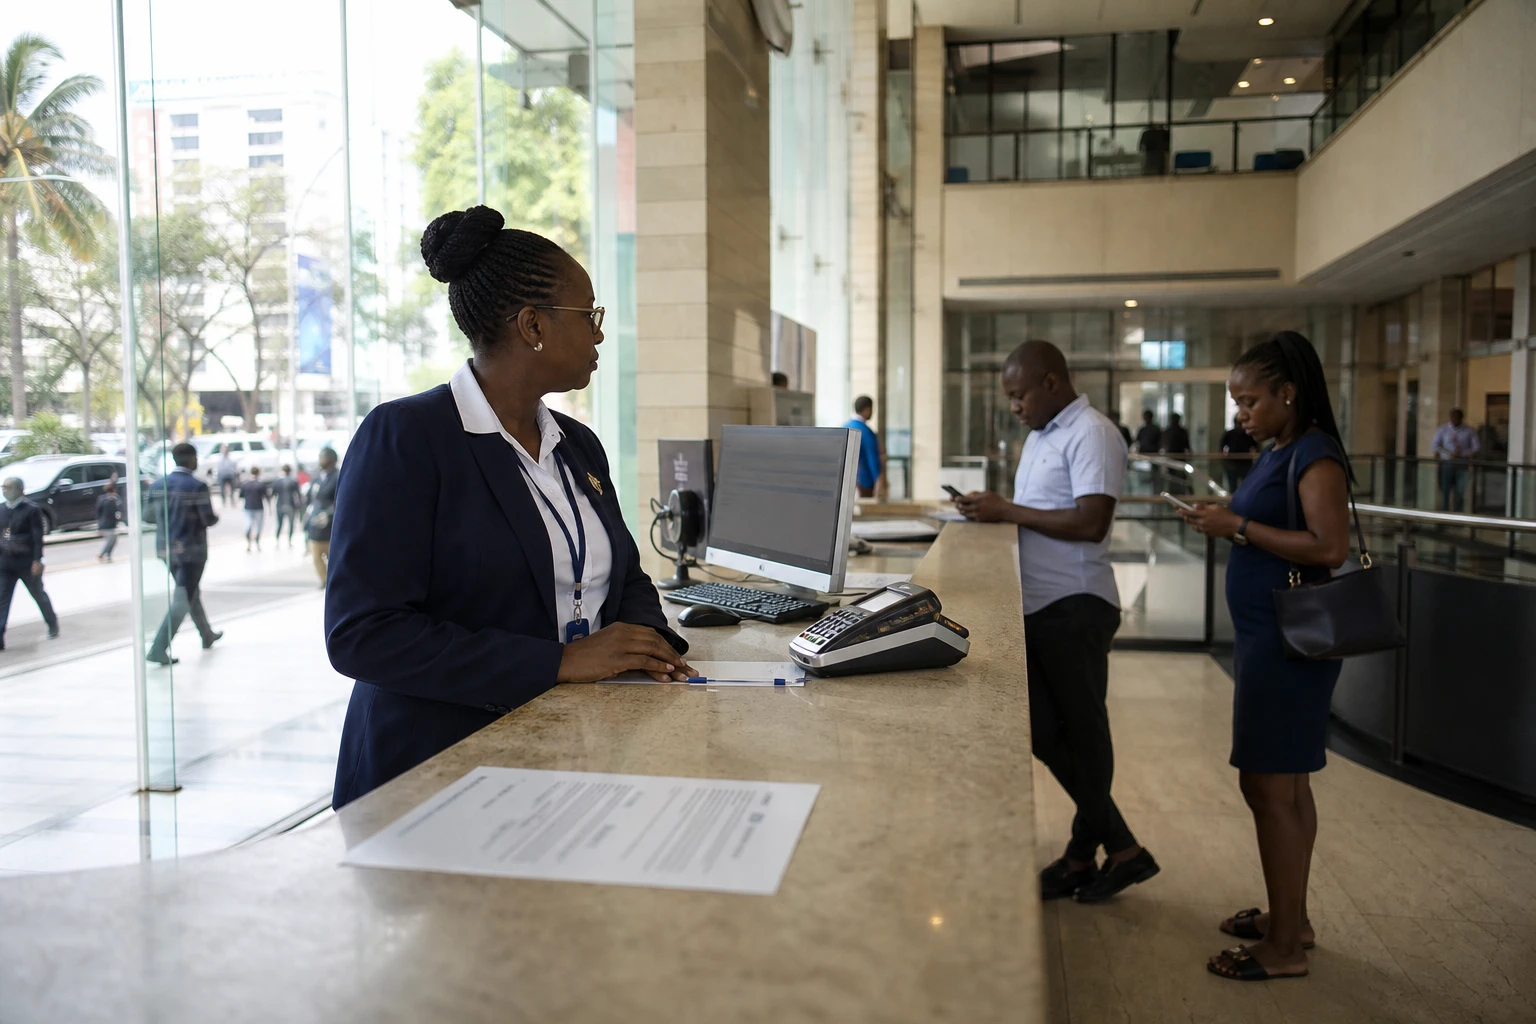
In Nairobi and in more remote counties, the mobile phone remains a central financial tool. Yet the 2025 figures point to an intriguing shift: subscriptions and agent networks are growing, while transactions carried out through agents are falling sharply. Kenya’s mobile money is not disappearing. It is changing form.
Fewer transactions, not less digital use
The Central Bank of Kenya says the average monthly volume of mobile money transactions fell from 309.3 million in 2024 to 217.6 million in 2025. The decrease was 30%.
The value of transactions fell more slowly, however. It stood at 722.5 billion Kenyan shillings in 2025, compared with 753.5 billion in 2024. The decline was therefore 4%. These figures mainly concern deposits and withdrawals carried out through agents.
This difference between the number and value of transactions is the clearest sign of the change under way. Kenyans are making fewer small transactions through agents, but the average amounts transferred remain high. Mobile money is not necessarily losing its economic importance. It is primarily losing some of its traditional uses.
Figures published by the Central Bank confirm this trend. In December 2025, Kenya had 473,536 active agents, compared with 381,116 a year earlier. The network grew by 24%. The number of mobile money service subscriptions also increased, from 42.3 million to 51.4 million, a rise of 22%.
The number of mobile subscriptions also rose, from 71.4 million in December 2024 to 78.4 million in December 2025. Kenya therefore had more phones, accounts and service points, but fewer transactions carried out at agents’ counters.
M-Pesa’s historic model enters a new phase
Launched in 2007 by Safaricom, M-Pesa helped transform payments in Kenya. The service enabled millions of people to send, receive and store money using a mobile phone. It also reduced reliance on conventional bank branches.
This model relied heavily on agents. They converted cash into digital balances, then carried out the reverse operation when customers made withdrawals. This network remains essential in rural areas, markets and neighbourhoods where access to bank branches is still limited.
But Kenya’s financial ecosystem has diversified considerably. Banks now offer their own apps. Merchants are making greater use of direct payments. Businesses can pay suppliers or employees digitally, without routinely depositing or withdrawing cash.
The Central Bank of Kenya’s statistical database also shows that the number of registered accounts and the agent network continue to grow. This suggests that the slowdown seen in 2025 does not reflect a general loss of interest in digital services.
Rather, it reflects a shift in how transactions are made. Some users are moving directly from the payer’s account to the merchant’s or recipient’s account. In such cases, the transaction remains digital but does not necessarily involve a deposit or withdrawal through an agent.
Small transactions are more exposed to costs
Taxation is another element of the debate. Kenya levies excise duty on fees charged for certain money transfer services. The tax framework has evolved over the years, with an increase in the rate applied to mobile network operators, notably following the 2023 reform.
A document from the Kenya Private Sector Alliance, the umbrella organisation for Kenya’s private sector, notes that the rate applied to cellular operators’ transfer services was raised to 15% in 2023. The document also highlights businesses’ concerns about the impact of this charge on users.
Taxation alone is not enough to explain the decline in 2025. The Central Bank’s report does not establish a direct link between tax and the fall in volumes. It is therefore more prudent to describe it as a possible factor among a wider set of changes.
For low-income households, fees weigh more heavily on small sums. Sending a few hundred shillings can represent a significant cost in proportion to the amount. Some users may therefore combine transfers, opt for a direct payment or temporarily return to cash.
The impact varies across regions. In Nairobi’s urban neighbourhoods, merchant payments and banking apps offer many alternatives. In rural areas, the agent often remains the most accessible point of contact. The national average decline may therefore mask very different situations depending on county and income.
A transformation extending beyond Kenya
Kenya remains a major testing ground for digital financial services in East Africa. Its evolution is of direct interest to the East African Community, or EAC, which brings together several countries pursuing regional trade and financial integration.
Kenya’s trajectory shows that a mature market can no longer be measured solely by the number of transactions carried out by agents. It is also necessary to track business-to-business payments, merchant settlements, transfers between bank accounts and digital wallets, as well as cross-border use.
This shift nevertheless raises a social question. If transactions move towards apps and direct payments, agents will need to adapt their businesses. They could provide more services related to credit, savings, insurance or commercial payments. Conversely, less well-equipped agents risk being hit by a drop in commissions from deposits and withdrawals.
The next step will therefore be to distinguish the decline of traditional mobile money from the overall growth of digital payments. The data available for 2025 already show that Kenya is not abandoning mobile finance. It is entering a phase in which tools, intermediaries and payment habits are being reshaped.