Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
A milestone reached, but the story is not over
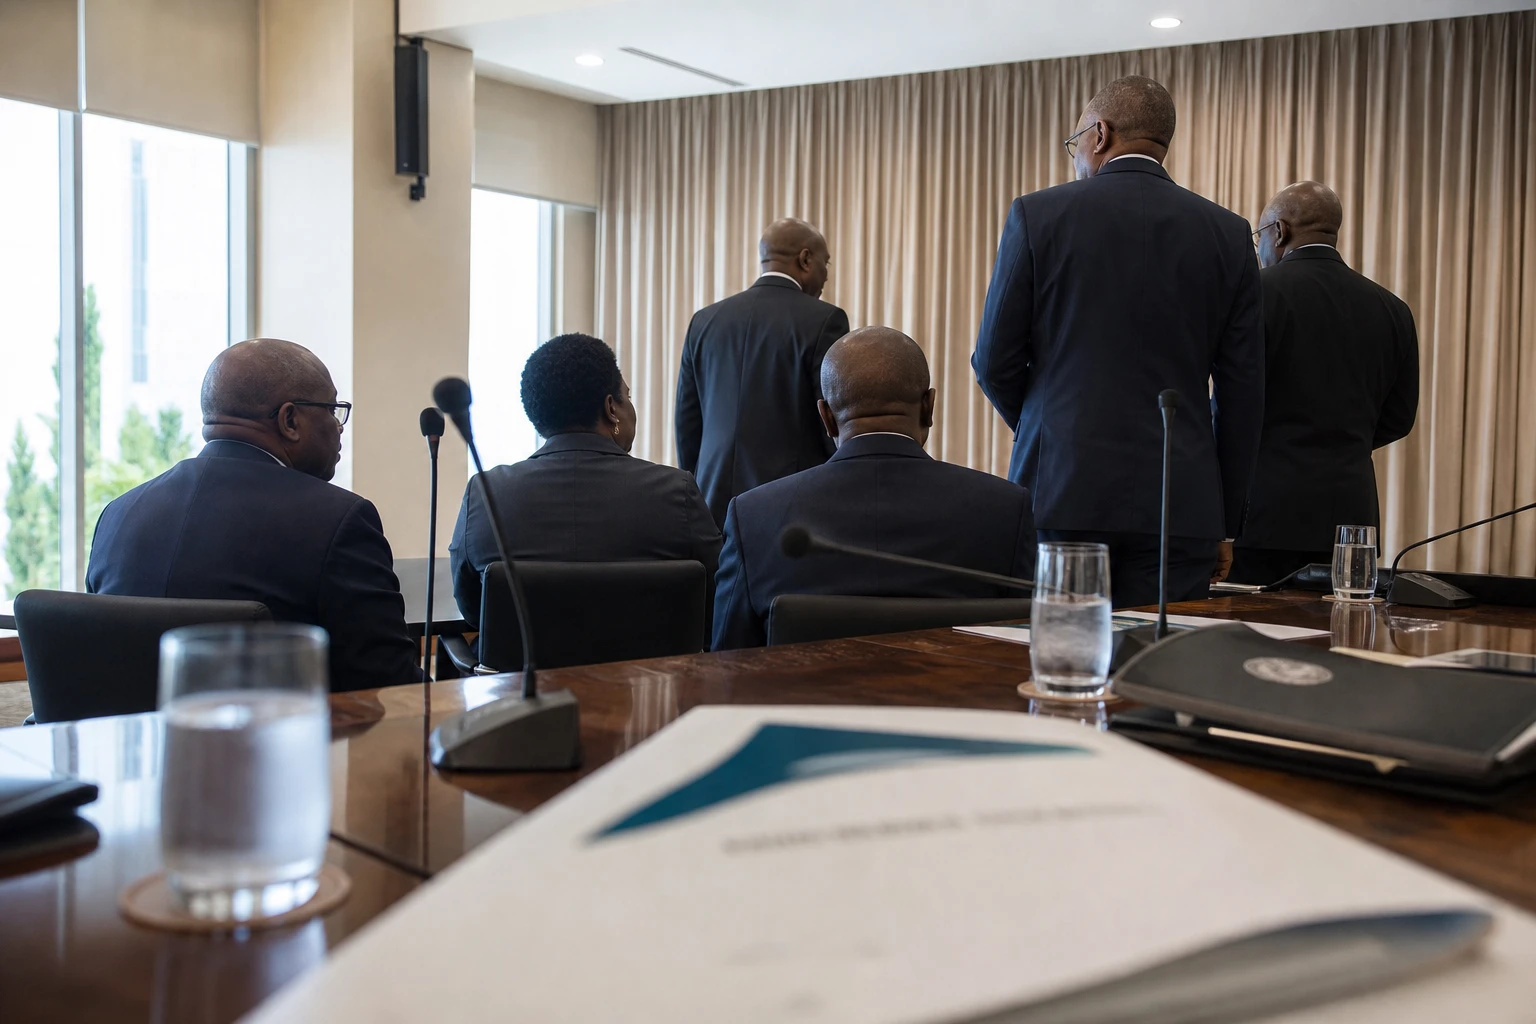
In Accra, the end of an International Monetary Fund programme is never just a technical ceremony. For Ghanaian households, it means something very tangible: the cost of an acute crisis is beginning to stabilise, but the price of returning to balance remains high. Ghana has gained greater macroeconomic visibility; it must now turn this respite into stronger, broader-based growth.
The country is not alone in this situation. In West Africa, several ECOWAS states have had to contend in recent years with rising global interest rates, pressure on currencies, debt and more expensive imports. Ghana’s case is therefore being watched beyond Accra, as it tests a simple question: can a country exit IMF support without losing the gains it has made, while retaining room to finance jobs, infrastructure and public services?
What the IMF approved, and what it means
On 27 July 2026, the IMF Executive Board completed the sixth and final review of Ghana’s programme under the Extended Credit Facility. The decision paves the way for a final disbursement of about $371m. It brings total funding disbursed under the agreement, launched in May 2023, to nearly $3bn. The Fund judged the programme’s performance to be broadly satisfactory.
This milestone did not come about by chance. In May 2026, IMF staff and the Ghanaian authorities had already reached a staff-level agreement on the programme’s final review and on a request for a Policy Coordination Instrument, a policy coordination tool that provides no direct financing. Ghana’s Ministry of Finance had confirmed at the time that the country was entering a transition phase, moving from financial support to a framework for monitoring reforms.
The signal is clear. Ghana is no longer seeking a fiscal safety net. It is now seeking to show that its policies remain credible without fresh IMF funding. This is an important distinction. In practice, the PCI serves as a guide: it does not provide cash, but it can reassure creditors, investors and donors about the course the government is following.
Visible progress, but significant vulnerabilities remain
The indicators cited by the IMF and the authorities point to a genuine recovery. Inflation fell to 5.3% in June 2026, according to the Ghana Statistical Service. International reserves have been rebuilt. In its May statement, the IMF also highlighted a marked improvement in fiscal performance, with the primary surplus exceeding its target in 2025, and a substantial fall in the public debt ratio.
These gains have tangible effects. For the state, they reduce the urgency of refinancing in a panic. For the Bank of Ghana, they provide some monetary breathing space. For importing businesses, they limit volatility in the cedi, even as prices remain sensitive to external shocks. For households, however, relief is not automatic: when inflation falls, it does not bring back yesterday’s prices. It merely slows their rise.
The IMF nevertheless stresses several areas requiring vigilance. First, the Bank of Ghana’s independence must be preserved. Second, quasi-fiscal activities must end — that is, spending or operations by state-owned entities that bypass the conventional budget. Finally, the central bank’s recapitalisation must be completed by 2032. These recommendations speak to a central debate in Ghana: how to consolidate stability without weakening the institutions that made it possible.
Debt restructuring remains the other sensitive issue. The IMF says about half of official bilateral creditors have already agreed to provide debt relief, while progress continues with other official and commercial creditors. In other words, most of the work has been done, but financial normalisation is not yet complete. Confidence is returning, but it remains conditional on fiscal discipline and transparency around public commitments.
An issue for Ghana, West Africa and the continent
Ghana has often been held up as a West African model of institutional continuity and democratic foundations. Its recent economic trajectory nevertheless shows that political stability alone does not protect against debt, currency and balance-of-payments shocks. The crisis that began in 2022 exposed the vulnerability of economies heavily reliant on imports, international financial markets and commodity price movements. The current recovery, conversely, shows that a rapid correction is possible if reforms are sustained.
The next test will be consolidation. The IMF estimates that from 2027, a primary fiscal surplus of 0.5% of GDP would remain consistent with debt sustainability, provided reforms to public financial management and state-owned enterprise governance continue, and quasi-fiscal risks are controlled. In other words, the debate is shifting: the task is no longer just to put out the fire, but to stop it from reigniting in the foundations.
For ECOWAS and, more broadly, African economies facing the same combination of high debt and limited fiscal space, Ghana’s case will be studied as a model. The PCI must now serve as a bridge between stabilisation and recovery. If it works, it will show that a country can exit an emergency programme without immediately falling back into financial dependence. If it disappoints, it will be a reminder that macroeconomic improvement is sustainable only if it translates into productive capacity, stronger domestic revenue and credible fiscal institutions.