Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
Commercial strength is not enough when the loan book deteriorates
At first glance, the signal is reassuring. A major African banking group can still grow its revenue and maintain business volumes. But in banking, the real question is not simply whether the numbers are rising. It is also what remains once risk has been absorbed, especially in Nigeria, where banks remain heavily exposed to oil cycles, naira fluctuations and the Central Bank’s prudential decisions.
Ecobank’s case illustrates this tension. The group reported net banking income up 15% to $1.3 billion and pre-tax profit of $423 million for the first half of 2026, an increase of just 6%. The gap between the two rates says it all: commercial activity continues to advance, but provisions and impaired assets are holding back the conversion into profit.
Nigeria, the balance sheet’s sensitive point
Nigeria remains a strategic market for the group, both because of its economic weight and its exposure to the oil and gas sector. Yet this is precisely where asset quality has taken its toll. The Central Bank of Nigeria ended prudential forbearance measures, forcing banks to reclassify some vulnerable exposures, particularly in energy. The measure is intended to clean up balance sheets, but it comes at an immediate cost to the institutions concerned.
Ecobank is not an isolated case in a Nigerian banking system still under pressure. In June 2025, the Central Bank asked banks operating under forbearance regimes to suspend dividends, defer executive bonuses and avoid new offshore ventures. This approach makes a clear priority: strengthen capital buffers before rewarding shareholders.
In the first quarter of 2026, the group had already shown that its core businesses remained robust. It reported pre-tax profit of $195 million, up 21%, on net revenue of $636 million, up 23%. The first half therefore confirms the momentum, but also reveals the vulnerability of the shift from revenue growth to growth in the bottom line.
Revenue rises as the cost of risk eats into margins
The picture is even clearer when looking at risk metrics. The group’s non-performing loan ratio rose to 9.4%, from 6.7% previously, while reserves for expected credit losses stood at $1 billion at the end of March, or 8.1% of outstanding loans. For a bank operating in 34 sub-Saharan African countries, this level of provisioning is not insignificant: it protects the balance sheet, but reduces distributable profits.
The Nigerian subsidiary was hit hardest. At the end of 2025, it reported a pre-tax loss of $31 million, with impairment charges almost four times higher, at $82 million. The message is clear: the Nigerian market continues to generate returns, but it also requires more capital, more provisions and much finer management of exposures.
This sequence is unfolding against a still challenging macroeconomic backdrop. The International Monetary Fund noted in May 2026 that the Central Bank of Nigeria had cut its policy rate to 26.5% in February, while maintaining a still-restrictive policy. The same report highlights the Nigerian economy’s sensitivity to exchange-rate shocks, energy prices and inflation. For banks, this means high interest margins, but also a greater risk of default among some customers.
Digital transformation continues to drive growth
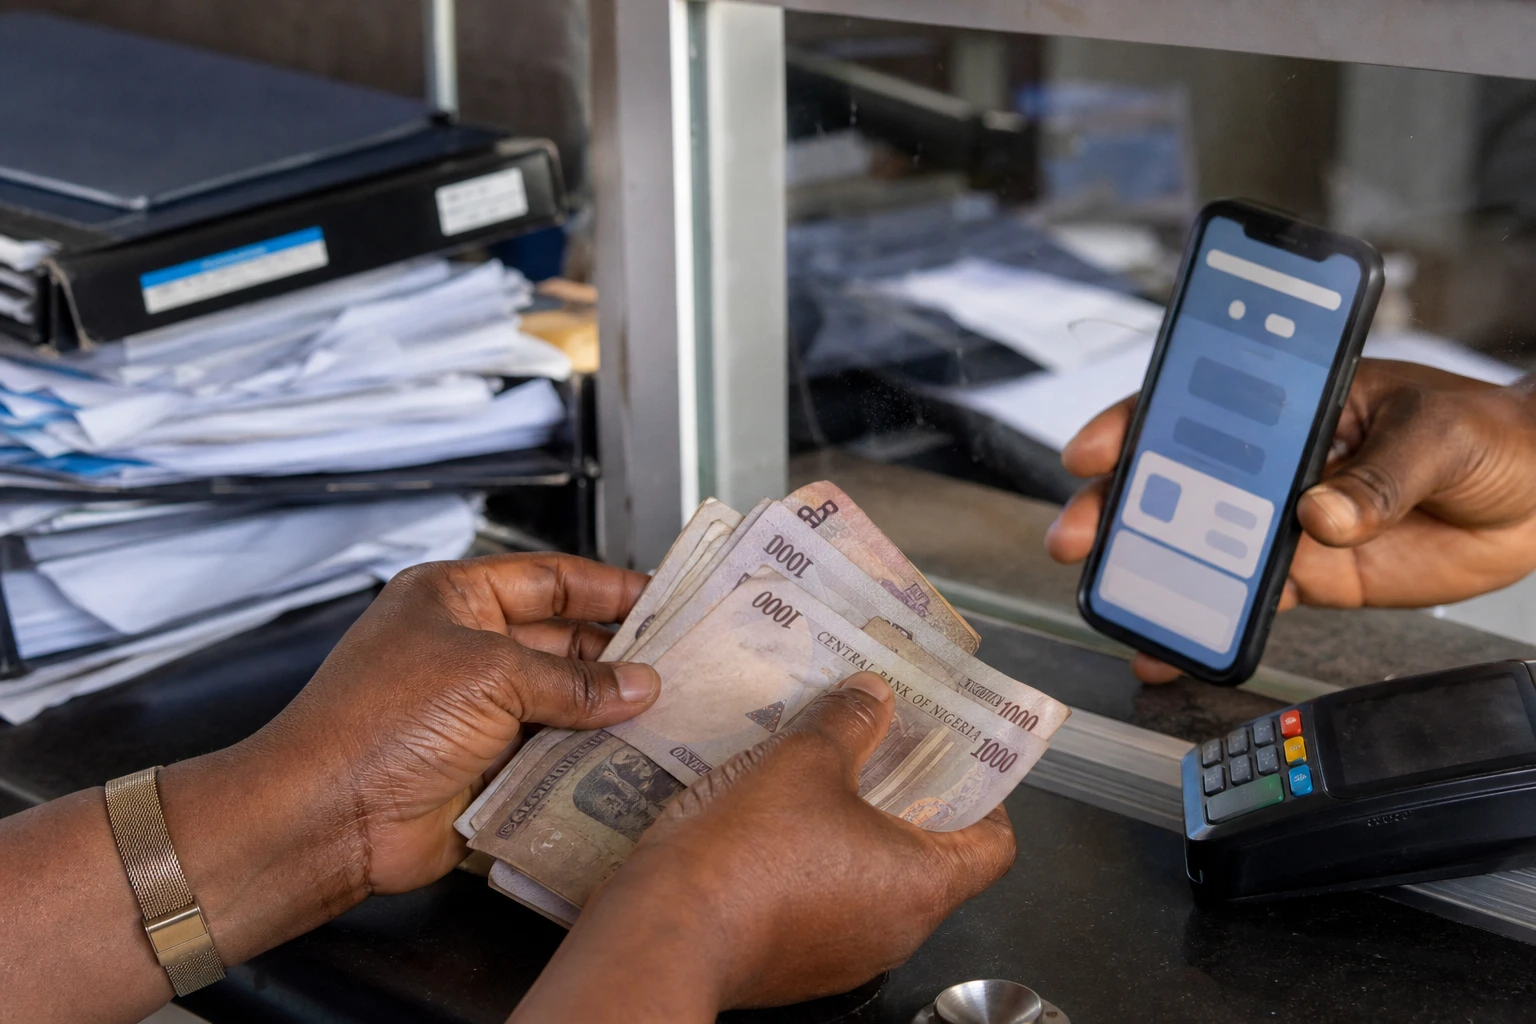
Despite this pressure, Ecobank is continuing its transformation. Payments remain one of the pillars of its strategy. In the first half, revenue from this activity rose 10% to $156 million, while the value of digital transactions jumped 33% to $78.5 billion. On a continent where transfers, merchant payments and mobile usage are growing rapidly, this segment is taking on an increasingly important role in the banking model.
This focus is not merely cosmetic. It responds to a distinctly African reality: banking revenue no longer comes solely from traditional lending, but also from fees, digital flows and transactional services. Ecobank complements this with a more flexible technology architecture based on cloud computing, application programming interfaces and mobile, enabling it to capture part of the growth off balance sheet.
The group has also strengthened its funding by raising $450 million in London through a nature bond, which was nearly four times oversubscribed, according to the London market. Such an operation matters beyond the balance sheet alone: it improves refinancing, diversifies the investor base and establishes African banks in international sustainable finance, without waiting for external players to validate their presence in this field.
A banking story that goes beyond one group’s performance
The significance of this report extends beyond Ecobank. It says something about the trajectory of West African banking. On the one hand, pan-African networks are expanding their reach, customer base and digital capacity. On the other, asset quality remains dependent on the real economy, hydrocarbons, monetary policy trade-offs and regulators’ decisions. Nigeria, the region’s largest market, concentrates part of this paradox.
The strategic repositioning is also visible in the shareholder base. In June 2026, the WAEMU Banking Commission approved the entry of Bosquet Investments, the investment vehicle of Cameroonian financier Alain Nkontchou, which brings its stake to at least 24.05% of the capital, ahead of Qatar National Bank. This is not a minor detail: it shows that a pan-African group can continue to reshape itself from within the continent, at the crossroads of Lomé, Abidjan and Lagos, and regional markets.
In the short term, the central question is straightforward: can Ecobank sustainably clean up its Nigerian exposure without derailing its dividend trajectory, restored in 2026 after several years of suspension? The current strategic plan ends this year, and its real test will depend less on gross growth than on the group’s ability to absorb the cost of risk while retaining its place in a new generation of pan-African banking.