Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
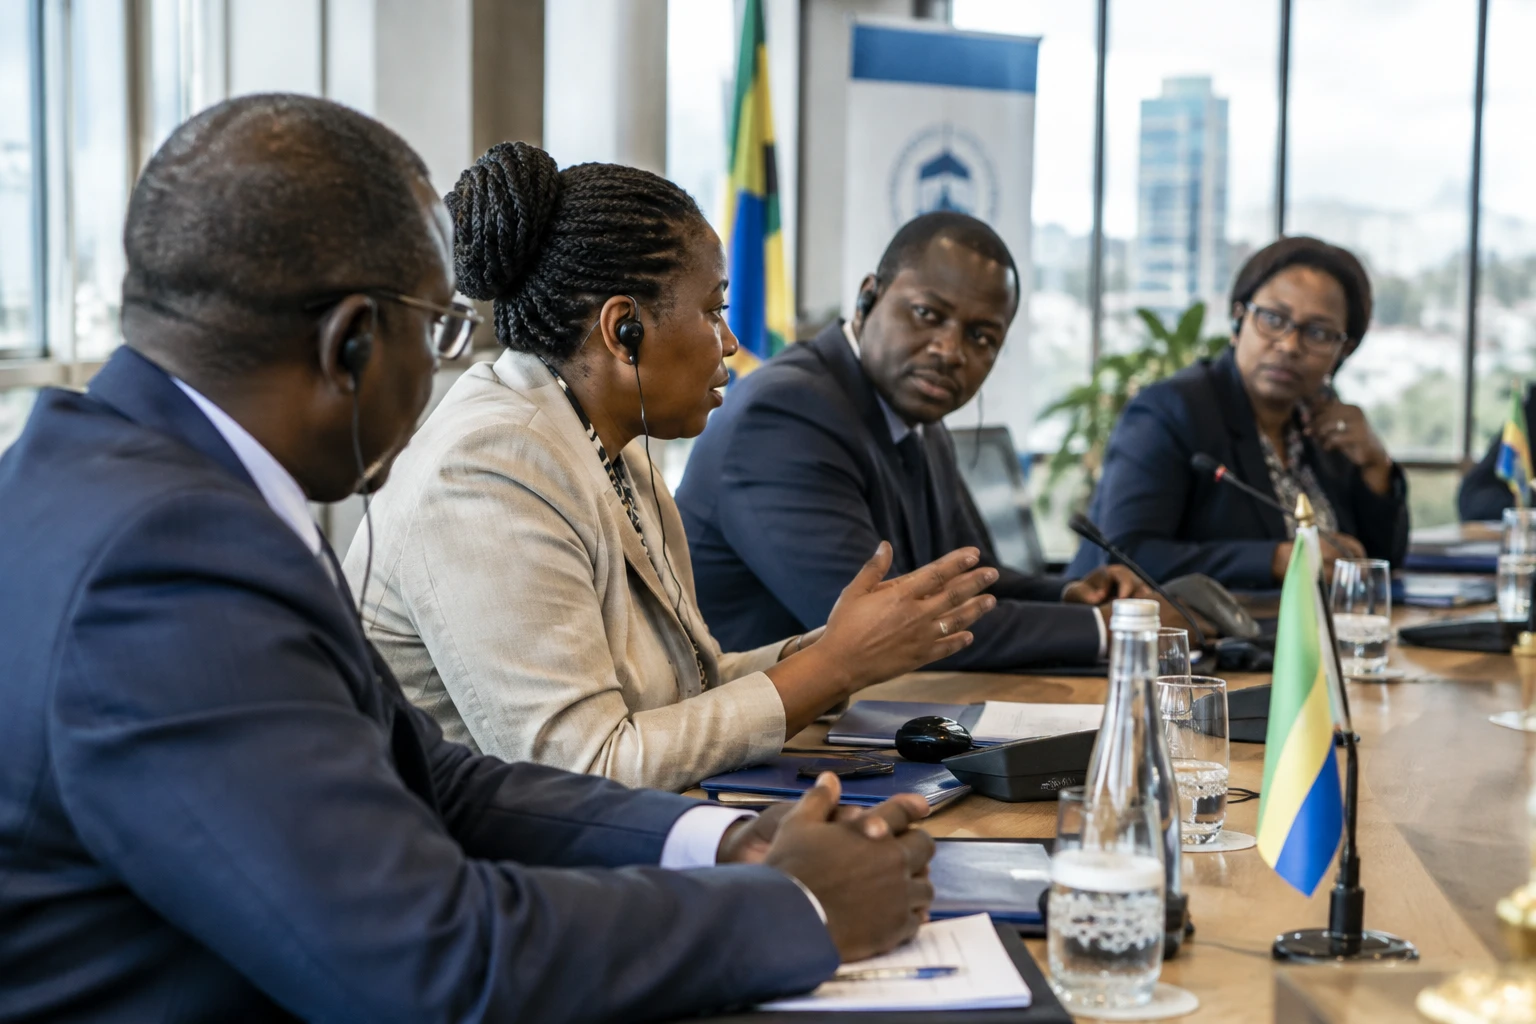
For a company in Libreville, the rate quoted by the bank does not tell the whole story. Application fees, commissions and other costs can add to the bill. In the second quarter of 2026, the average overall cost of credit in Gabon was significantly higher than in Cameroon, despite the two countries sharing a currency and central bank.
In CEMAC, a common currency does not mean credit costs the same
Gabon and Cameroon belong to the Economic and Monetary Community of Central Africa (CEMAC), which brings together six countries around the Central African CFA franc and the Bank of Central African States (BEAC). The BEAC sets regional monetary policy. Yet the terms offered by banks vary from one national market to another.
This difference comes as the average cost of credit in the community fell in the second quarter of 2026. The regional trend did not therefore translate into a uniform decline. In Gabon, the average rate instead rose year on year, while Cameroon recorded a lower level. Gabon’s situation comes against a backdrop in which business financing remains a challenge for economic activity and investment.
The figures must, however, be read carefully. The BEAC report is the reference for the period, but reports based on its data give slightly different figures for Cameroon and the regional average. The Cameroonian rate is reported at either 8.22% or 8.31%. These differences in published figures do not change the overall picture, but they are a reason to avoid false precision in the comparison.
Total cost matters more than the interest rate alone
According to data reported from the BEAC’s monitoring, the average effective global rate (TEG) in Gabon reached 21.51% between April and June 2026. The TEG combines interest and fees included in the cost of credit. In Cameroon, the publications consulted put the average at around 8.2%. In other words, the indicator for Gabon is more than twice as high.
A comparison of national averages does not mean that every borrower in Gabon pays exactly this rate, or that every loan in Cameroon costs less. The amount borrowed, the term, collateral and the client’s financial situation all affect the terms negotiated. The composition of loans granted in each country can also push averages up or down.
The share of fees deserves particular attention. Data published on the report indicate that nominal interest and fees contribute differently to the TEG in Gabon and Cameroon: commissions and other charges are said to account for a larger share of the total cost in Gabon. The TEG thus gives a more complete picture than the nominal rate alone. However, it cannot by itself identify which fees a particular bank charges each client.
Businesses and households face different obstacles
High financing costs reduce the room for manoeuvre of businesses that need to invest, replace equipment or cover day-to-day expenses. Small and medium-sized enterprises can be particularly sensitive to collateral requirements and the time taken to process applications. Larger companies often borrow bigger sums and have different risk profiles. A general average is therefore not enough to describe the conditions each faces.
Individuals are affected in other ways: consumer credit and vehicle or housing finance can become harder to manage when fees are added to interest. In urban centres such as Libreville, where access to banking services is more concentrated, formal offers are more visible. For residents of other cities and rural areas, access to branches, collateral and credit products can also shape the options available. The average data do not break down these geographical differences.
The share of public-sector claims in banks’ portfolios is another element of the context. Data published by the financial press, attributed to the professional association of credit institutions in Gabon, indicate that banks had significant exposure to the state at the end of June 2026. This raises a question about how resources are divided between public financing and business financing. This finding does not in itself prove that sovereign exposure explains the high TEG: borrower risk, collateral and banking costs also matter.
An indicator to watch beyond Gabon
The fall in the regional average therefore masks different national trends. In CEMAC, rate gaps can influence investment decisions and businesses’ ability to grow. They also show the limits of a common monetary policy: the BEAC influences monetary conditions across the zone, but the rates actually charged also depend on banks and the risks specific to each market.
For people in Gabon, what happens next will depend on the trend in upcoming figures and the transparency of fees associated with loans. The figures published for the second quarter of 2026 do not say whether the gap with Cameroon will persist. Above all, they are a reminder that assessing a loan requires looking at its total cost, not just the advertised rate.
Period data and differences between countries are reported in the BEAC publication on lending rates in CEMAC and cross-checked against reports by Sika Finance and EcoMatin.