Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
Credit, a weak link in Tanzania’s growth
In Tanzania, a business can have customers, orders and even an exportable idea, yet remain stuck on one question: who will finance the first delivery, the purchase of raw materials or the leap into a foreign market? This is often where the difference lies between an activity that survives and one that grows. Small and medium-sized enterprises remain at the heart of the Tanzanian economy, with more than 3 million units recorded in a report by the African Development Bank and more than 5 million associated jobs.
This issue goes beyond banking alone. In Dodoma, the Tanzanian authorities have included financial inclusion and financing for micro, small and medium-sized enterprises in their 2023-2028 roadmap. The Bank of Tanzania says this national framework aims to expand access to financial services, with an emphasis on digital innovation and SME lending. At the same time, the East African Community, headquartered in Arusha, Tanzania, is pushing for greater trade integration and the movement of goods across the region.
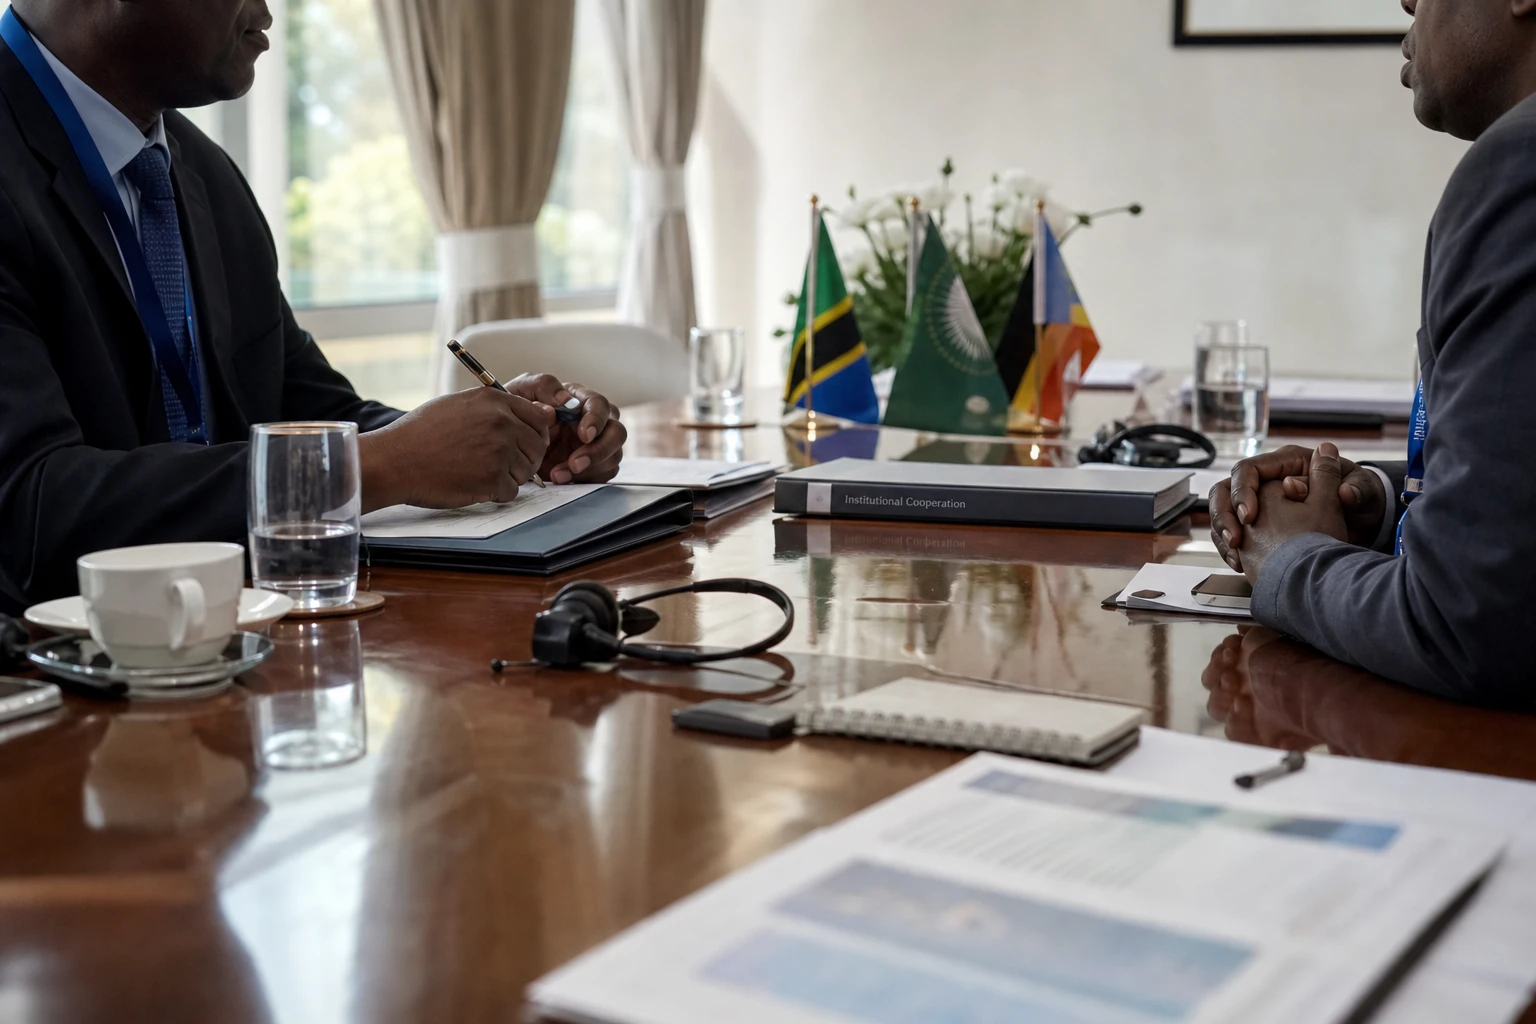
Against this backdrop, the announcement on 17 September 2026 has practical significance. Afreximbank and Azania Bank Tanzania have concluded a $10 million financing agreement to support Tanzanian SMEs. The programme is part of the Export SME Development Programme, known as ESDP. It is intended to enable the local bank to provide working capital and medium-term financing to eligible businesses. The goal is clear: to help these companies buy, produce, store, transport and export with less pressure on their cash flow.
What the partnership actually finances
The money is not just for lending. It is designed as a lever for the wider business ecosystem. According to Afreximbank, the programme combines financing with non-financial support: export readiness, financial management advice, business matchmaking and assistance with digitalisation. In other words, the pan-African bank is not simply injecting liquidity. It is also seeking to address weaknesses that are costly for African SMEs: weak bankable proposals, limited understanding of standards, restricted access to buyer networks and an inability to sustain longer production cycles.
The targeted sectors convey the scale of the ambition: agriculture, manufacturing, trade, technology, logistics and high-value-added exports. This choice matters. In Tanzania, most businesses operate in segments that are vulnerable to cash-flow shocks and transport costs. The problem is therefore not just producing more. Producers must also be connected to ports, warehouses, regional markets and foreign buyers. This is where value chains become a major economic issue, not a slogan.
The partnership also speaks to a broader agenda: African integration. Afreximbank places this type of initiative within its strategy for intra-African trade, industrialisation and export development. The institution says it launched its Export SME Development Programme in 2022 to support export-oriented businesses. In 2024, it said it had already supported thousands of SMEs through workshops, accelerators and training. This new agreement in Tanzania extends that approach: making SMEs a practical vehicle for the African Continental Free Trade Area (AfCFTA), which aims to facilitate trade between African countries.
Expected impact, but real constraints remain
For SME leaders, the announcement could ease a longstanding bottleneck. In Tanzania, difficulties accessing credit, logistics costs and infrastructure gaps remain regular obstacles to small-business growth. The World Bank has for several years identified access to finance as one of the major constraints facing Tanzania’s private sector. The new agreement will not remove these obstacles, but it could help cushion their impact, particularly for businesses that already have a market, basic accounts and export potential.
For employees and young entrepreneurs, the stakes are more immediate. If SMEs gain access to more flexible credit lines, they can buy earlier, produce more regularly and better withstand payment delays. This could support employment, particularly in agrifood, processing, logistics and digital services. But the impact will depend on how beneficiaries are selected. Well-targeted financing can strengthen the productive fabric. If it is too concentrated, however, it could benefit only a handful of businesses that are already well-established.
For the Tanzanian government, the bet is strategic. The country is seeking to broaden its industrial base, increase higher-value-added exports and better connect its SMEs to EAC markets and the continental market. The agreement between Afreximbank and Azania Bank therefore forms part of a wider sequence: financial inclusion, credit reform, digital payments and the upgrading of local production. In Dodoma, this equation matters as much for growth as for urban employment, in cities where SMEs account for a decisive share of formal and informal activity.
The signal is just as clear at regional level. Tanzanian businesses are not only being encouraged to sell more at home. They are being urged to position themselves in East African value chains and, ultimately, across the continent. This is precisely the kind of transition the AfCFTA aims to accelerate: moving from trade dominated by a few large operators to a broader base of businesses able to produce, process and export. The next indicator to watch will therefore be less the amount signed than the number of SMEs actually financed, the quality of the sectors selected and how quickly the loans translate into regional sales.