Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
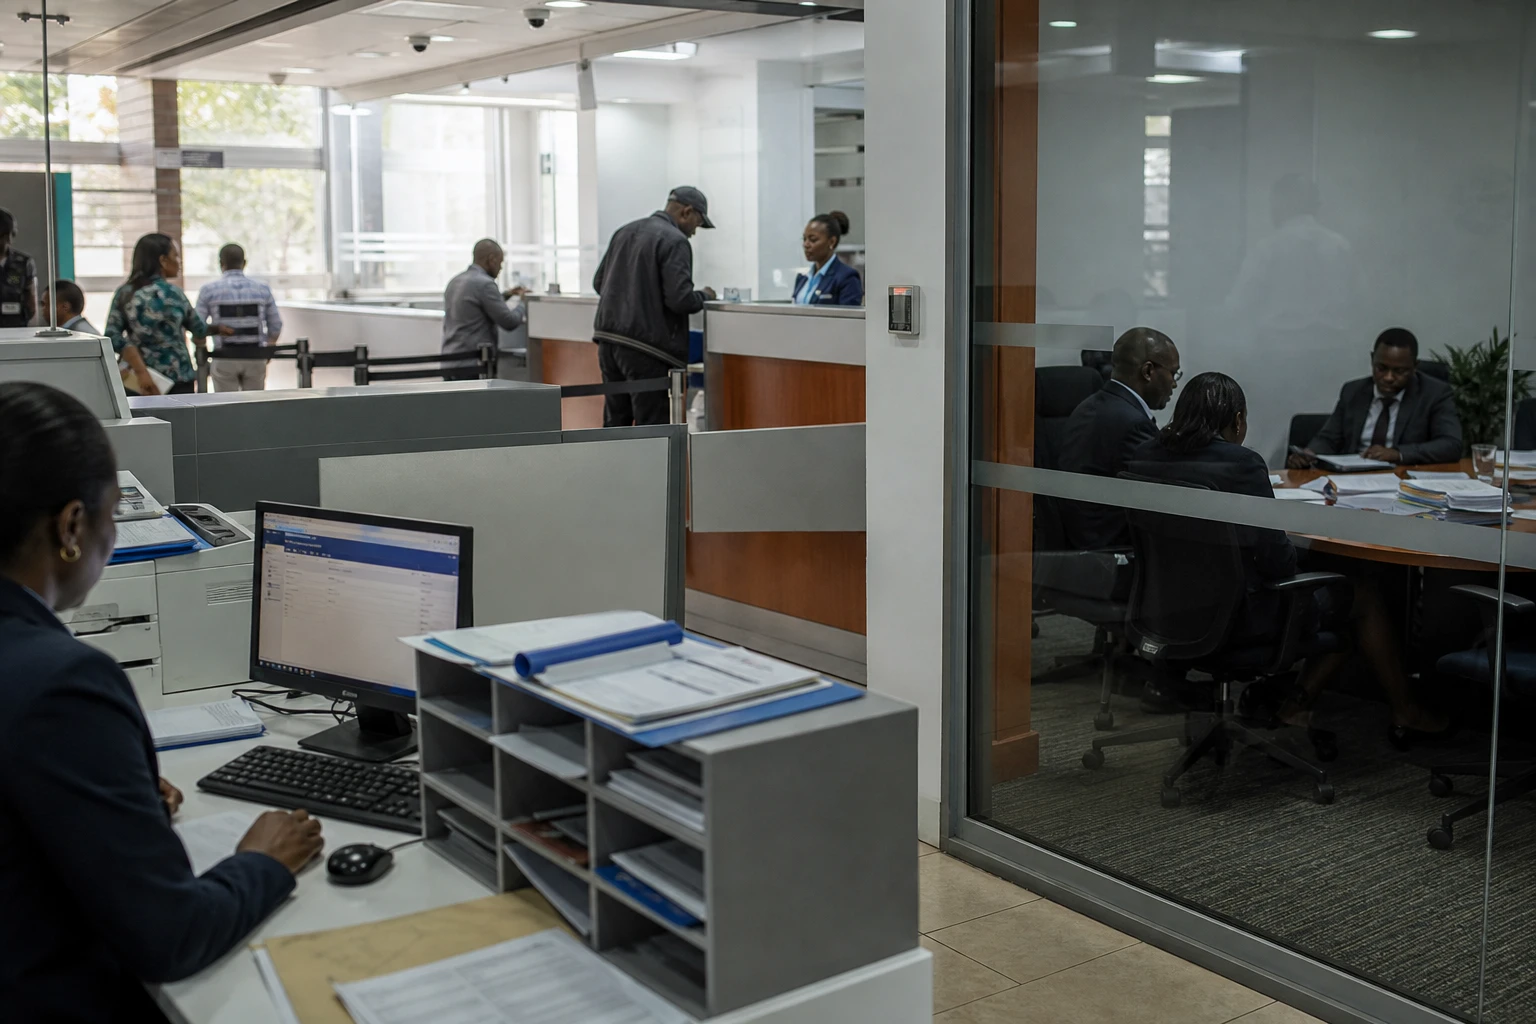
When a major group falters, the whole market feels the tremor
In Kenyan finance, the real question is not simply whether a bank is profitable. It is what happens if it suddenly stops operating. In Nairobi, the Central Bank of Kenya is seeking to prevent a major institution from taking depositors’ confidence, businesses’ payments and part of the credit supply to the real economy down with it.
The debate is not theoretical. Kenya’s banking sector remains concentrated. The largest groups account for a substantial share of the system’s deposits, profits and assets. The central bank has already noted in recent reports that the sector has continued to show resilience despite several shocks, while also remaining exposed to credit, liquidity, cybersecurity and funding risks.
What the regulator in Nairobi is preparing
On 10 September 2026, the Central Bank of Kenya opened a public consultation on a new framework for domestic systemically important banks, or D-SIBs. The idea is simple: to identify each year the institutions whose size, interconnectedness, complexity and role in the Kenyan economy could make their failure dangerous for the entire system. The regulator says it wants to align the country with international best practice and the approach that emerged after the 2007-2009 global financial crisis.
The proposal is also part of a broader trend. In April 2025, the central bank had already published new guidelines on the liquidity coverage ratio, the net stable funding ratio and leverage, with the stated aim of making the sector more robust and resilient. The new text extends that approach, but targets banks whose failure could have a domino effect.
The framework under consultation provides for an assessment system based on indicators such as size, interconnectedness with other institutions, substitutability of activities, operational complexity and domestic importance. Banks classified as D-SIBs would then face additional common equity tier 1 (CET1) capital requirements of between 0.5% and 2.5% of risk-weighted assets. The document also provides for stricter liquidity requirements, enhanced disclosure obligations and, if necessary, restrictions on certain activities that pose systemic risks, such as excessively rapid regional expansion or the launch of new products.
The text goes beyond capital buffers alone. The central bank wants more frequent supervision, including enhanced inspections, closer monitoring of governance and quarterly stress tests. The banks concerned will also have to prepare recovery and resolution plans: detailed scenarios for surviving a crisis without seeking an improvised public bailout.
Why the reform is coming now
Kenya still remembers its recent domestic banking crisis. Between 2015 and 2016, Dubai Bank, Imperial Bank and Chase Bank were affected by successive failures or placed under receivership, disrupting the interbank market and undermining depositors’ confidence. The central bank’s annual supervision report and communications from the Kenya Deposit Insurance Corporation confirm this sequence. Dubai Bank was placed under receivership over capital and liquidity problems. Imperial Bank and Chase Bank later revealed deeper irregularities.
The period left a lasting lesson: a bank does not necessarily have to be huge to cause significant damage if it is highly connected to the rest of the system. It is precisely this risk of contagion that the new framework seeks to contain. In the regulator’s terms, the aim is to reduce the likelihood of failure, limit the impact of a potential crisis and avoid forcing the public sector to rescue an institution that has become too important to fail.
Market observers believe several major groups could fall within the framework: Equity, KCB, NCBA, Co-operative Bank and I&M. This is no coincidence. The structure of Kenya’s banking system shows a high concentration of deposits and profits among the largest institutions. According to the 2023 supervision report, large banks accounted for about 77.4% of the sector’s total deposits. This means the health of the biggest players weighs heavily on overall stability.
What this means for banks, businesses and households
For the major groups, the reform is not just a constraint. It could also become a competitive advantage. Higher capital and liquidity requirements encourage better risk management, stronger governance and greater investment in internal controls. The most robust institutions may see this as a way to secure their expansion, particularly in East Africa, where banking is becoming increasingly regional.
But the cost will be real. More capital tied up means less room to distribute dividends or pursue multiple high-risk operations. More oversight also means higher compliance costs. For shareholders, the message is clear: growth remains possible, but it will need to be better capitalised. For senior management, the era of rapid expansion without safeguards could be drawing to a close.
For households and small businesses, the stakes are different. A sound bank protects deposits, ensures the continuity of transfers and supports everyday lending. In a country where digital payments, domestic transfers and SME financing rely heavily on banks, a failure that is not contained would have a very tangible cost. The new framework is therefore intended to protect the everyday economy, not just the balance sheets of major groups.
The framework also raises a regional question. Several of Kenya’s largest groups already operate across borders in the East African Community. Tighter rules in Nairobi could therefore influence how these banks balance regional growth, available capital and risk appetite. This matters for East African financial integration, because the strength of a major Kenyan player can affect its neighbouring subsidiaries, for better or worse.
A test for Kenya’s banking sector and, beyond it, East Africa
This reform says something broader about the maturity of Kenya’s financial market. The country is no longer seeking only to develop banking intermediation. It is seeking to make the system resilient to shocks. This is a familiar step for financial centres as they grow in importance: the more central a system becomes to payments, savings and credit, the more it needs specific safeguards.
Across the continent, the signal is clear. Kenya is following a path already taken by other regulators facing banks too interconnected to be treated as ordinary institutions. In East Africa, where financial groups are increasingly expanding across several markets, consolidated supervision and additional capital buffers are becoming a shared concern. The consultation opened in Nairobi will therefore provide a useful indication of how the region’s authorities intend to regulate the next phase of banking expansion.
The next steps will be the comments received by the central bank, followed by its final decision on the text. If the rules are adopted as drafted, Kenya will move towards a stricter approach to systemic risk prevention. If they are softened, the regulator will have to show it can preserve the balance between banking expansion, competition and stability. In a country where finance directly supports the activity of households, SMEs and large businesses, the choice will matter far beyond Nairobi.