
 Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
A market still underserved, but more structured than it appears
In Cameroon, insurance remains a form of protection that is still used too little by a large share of households, artisans and informal-sector workers. Samb’a Assurances Cameroun wants to position itself in this space with a microinsurance offer designed around lower entry premiums and digital distribution. The project is entering a country where the market is growing, but coverage remains uneven between conventional products and everyday needs.
Cameroon is no arbitrary choice. In the CIMA zone, which regulates insurance in several countries in Central and West Africa, access to the market is governed by common rules. The Ministry of Finance in Yaoundé acts as the national link in this regional framework. Any company seeking to operate must therefore comply with regional rules as well as local requirements for compliance and licensing.
Licensing application enters decisive phase
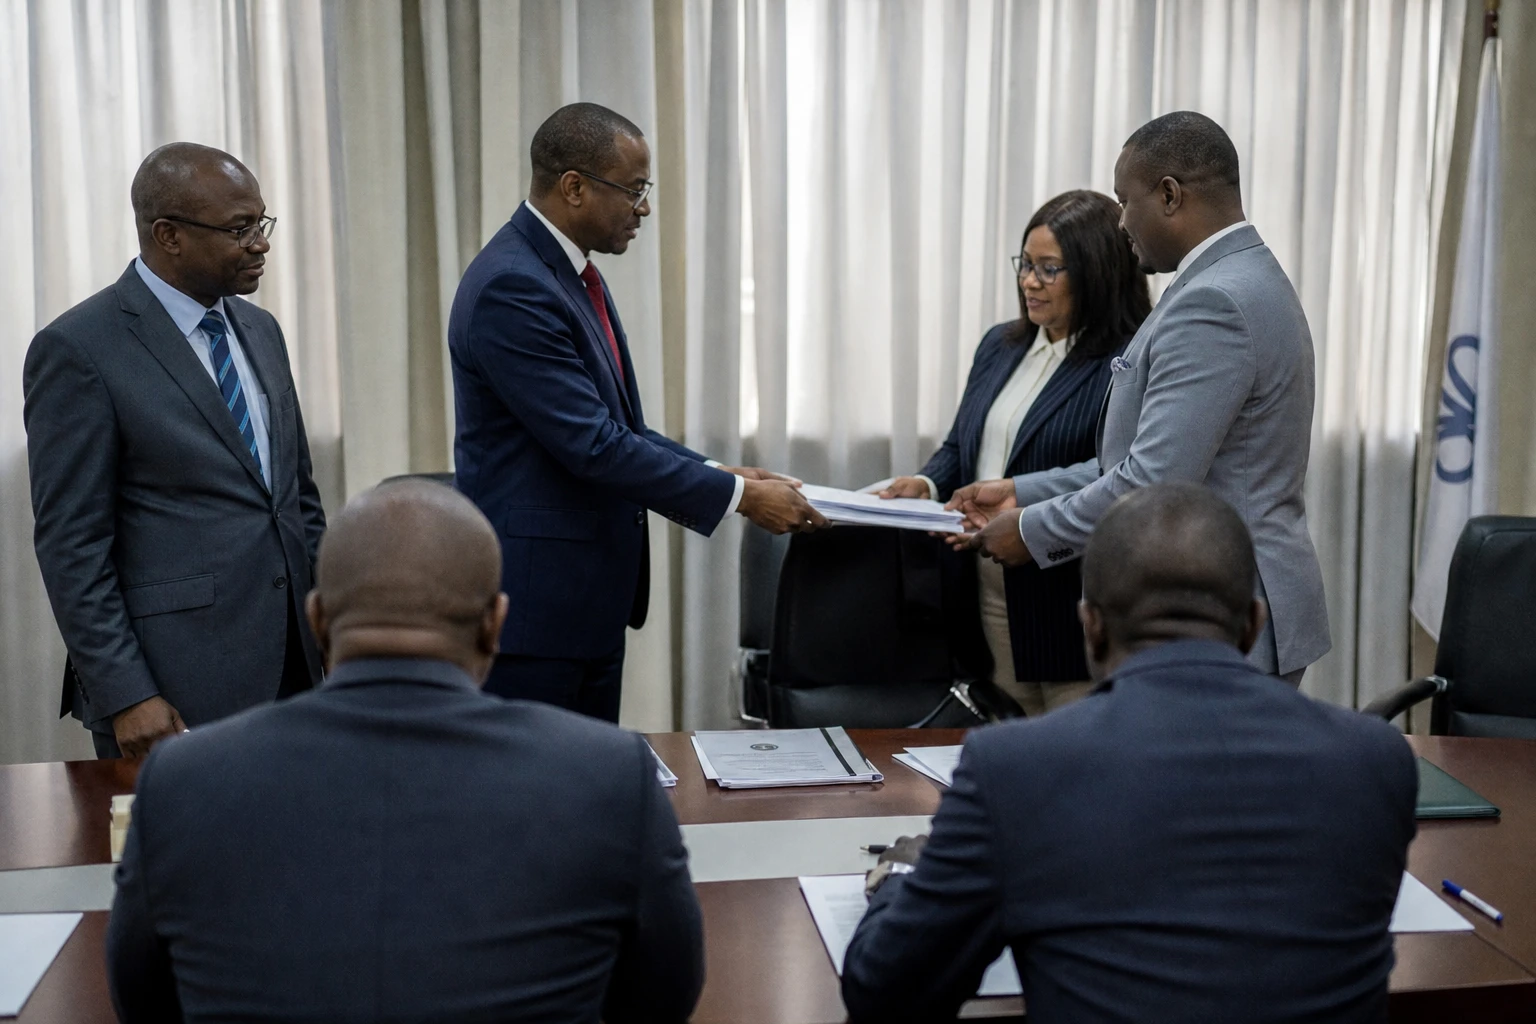
On 4 September 2026, a working session was held on the project to establish Samb’a Assurances Cameroun S.A. Discussions covered the presentation and subsequent transmission of the licensing application, ahead of its submission to Cameroon’s Ministry of Finance through the Insurance Directorate. The meeting brought together Abel Blaise Ezo’o Engolo, independent director, Barthélemy Zoua, chief executive officer, and Andrew Gwodog, founder and chairman of the subsidiary’s board.
This step is mandatory. The CIMA Code stipulates that microinsurance companies and insurance companies may not conduct the prescribed operations until they have obtained a licence. It also specifies that a company may operate only in the classes for which it has been authorised. In other words, the application must clear the regulatory hurdle before any products can be marketed.
The Cameroonian subsidiary was incorporated in Douala on 21 May 2026. Its announced capital is CFAF 615 million, divided among 59 shareholders. Another public presentation by the group cites capital of CFAF 615.51 million and subscriptions from 59 shareholders, confirming the initial figure’s order of magnitude.
The group says it is targeting customers often poorly served by traditional insurance products. The announced products would start at monthly premiums of CFAF 3,500, with distribution through Mobile Money, microfinance institutions and community networks. The target market includes informal-sector workers, farmers, small traders, artisans, artists, associations and small businesses.
Why microinsurance could take the sector to a new scale
Cameroon already has a sizeable insurance market. Figures published by the Ministry of Finance show CFAF 288.7 billion in premiums written in 2024, up from CFAF 274.6 billion in 2023. Non-life insurance — fire, accidents, miscellaneous risks and transport — generated CFAF 190.3 billion, while life insurance accounted for CFAF 98.4 billion. The market is growing, but microinsurance opens another door: frequency, volume and accessibility.
On the ground, the stakes are tangible. For a formal-sector employee, a conventional policy can be one line item among many in the household budget. For a market trader, farmer or independent driver, the calculation is different. Premiums must remain affordable, claims settlements easy to understand, and enrolment quick. This is where Mobile Money and microfinance networks become strategic: they reduce friction and bring the product closer to everyday use.
The CIMA Code also governs the types of activity that may be authorised. Microinsurance companies may apply for licences covering non-life operations and, under certain conditions, temporary life insurance. Savings and capitalisation products, by contrast, remain tightly regulated and are even prohibited on a company’s own account in several cases. This specialisation limits commercial abuses and underlines that microinsurance is not simply insurance with fewer features, but a distinct segment with its own rules.
For the average Cameroonian, the expected impact is twofold. On the one hand, more people could gain access to insurance through a simple, clear product with a low premium. On the other, the market could expand into underserved niches: basic health cover, crops, death, small assets, livestock or local trading activity. The potential is real, but it will depend on the offer’s credibility, the strength of the collection network and the speed of claims processing.
A Cameroonian step forward in a wider regional trend
Samb’a Assurances Cameroun’s project is more than a corporate venture. It forms part of a broader push for financial inclusion in Central Africa. The group already describes itself as operating in Gabon, where it launched activities in 2024, before announcing plans to expand its network into Cameroon. This regional expansion reflects a clear trend: African operators are seeking to build cross-border models rather than remain confined to a single national market.
For Cameroonian authorities, this process is also significant. It will test the CIMA framework’s ability to accommodate more flexible products without weakening policyholder protection. For industry players, it could spur competition, encourage digital innovation and broaden the customer base. For households, it will matter only if commitments are clear, exclusions easy to understand and claims settled on time.
At regional level, the application also highlights how microinsurance is becoming an economic as well as a social strategy. In CEMAC and the CIMA zone, it could support the gradual expansion of banking, the growth of Mobile Money and the partial formalisation of certain incomes. The next development to watch is the review of the licensing application by the competent authorities in Yaoundé, followed by the precise classes of insurance authorised. That is when the project will move from an ambition to a regulated player in the Cameroonian market.



