Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Cameroon
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
A discreet mineral, a highly political supply chain
In Kigali, the expansion of a tungsten mine says much more than an industrial success story. It reflects Rwanda’s new position in critical metals supply chains, as major powers seek suppliers deemed safer for their sensitive industries. Tungsten falls into this category: it is used in hard alloys, aerospace and applications linked to US defence.
The issue therefore goes beyond the Nyakabingo site alone. It concerns how a Great Lakes country and member of the East African Community can turn a mining resource into diplomatic and economic leverage. Rwanda is well integrated into this regional space, where trade flows, customs standards and industrial ambitions are increasingly converging.
Nyakabingo, a cornerstone of moving up the value chain
The Nyakabingo mine, operated by Trinity Metals, is at the heart of this development. The company says its shipments to the United States now account for up to 20% of US monthly consumption of primary tungsten concentrate. It also says it has shipped more than 320 tonnes of high-grade concentrate since a commercial agreement began in August 2025. These figures have been reported by several independent Rwandan media outlets, including The New Times and KT Press.
The timing highlights what is at stake. In May 2026, Trinity Metals said it was preparing an investment of $100 million to $200 million to expand its mining operations. Part of that sum is to fund a processing plant at Nyakabingo, with an announced cost of between $45 million and $60 million. The stated aim is straightforward: capture more value in Rwanda rather than limit exports to raw materials.
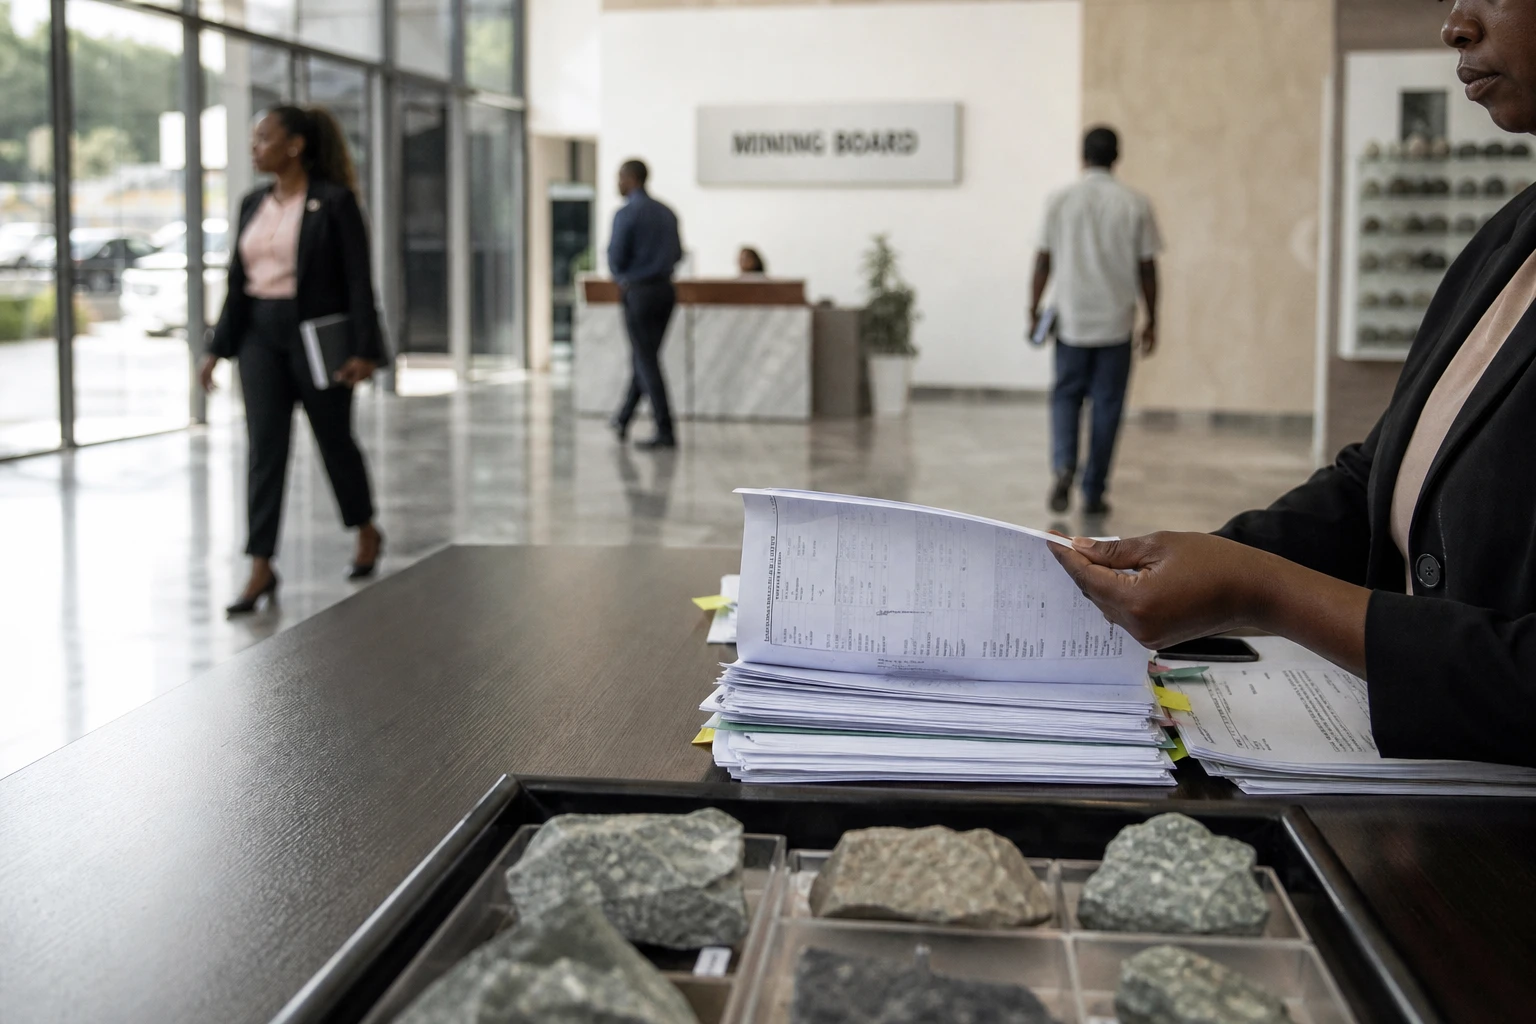
Rwandan authorities are pursuing the same goal. The Rwanda Mining Board says the country already earns significant revenue from its mining sector and wants to develop local processing of tungsten, lithium and other minerals. The sector generated $1.75 billion in export earnings in 2025, according to the institution. The Rwanda Development Board, for its part, says total exports reached $3.6 billion in 2025, a sign of an economy seeking to diversify its growth drivers.
Washington, Beijing and the supply battle
Rwandan tungsten is attracting attention because the global market is highly concentrated. China dominates a large share of supply and processing, and trade tensions have prompted Washington to secure alternative sources. The Pentagon says tungsten is an essential metal for aerospace, ground vehicles, munitions and several defence systems. It is already funding projects designed to stabilise US supplies of critical metals.
In this context, the US decision to reduce reliance on Chinese materials for military applications is increasing interest in African and other non-Chinese suppliers. Specialist media reports, citing Reuters, say a ban on the use of Chinese tungsten in US military equipment is due to take effect in 2026. At the same time, China has tightened its own rules on exports of certain strategic metals, including tungsten, adding pressure to global supply chains.
Rwanda is benefiting from this opening. But it should not be seen as a simple windfall. The country has spent years structuring a sector long characterised by artisanal mining, limited industrialisation and questions over traceability. The closer ties with US buyers show that compliance, certification and consistent volumes now matter as much as geology.
What this means for Rwanda and the region
For Rwanda’s economy, the goal is clear: sell less raw ore and more processed product. This creates more skilled jobs, improves margins and can support export earnings. The government also wants to increase the mining sector’s contribution under its 2024-2029 development strategy. Growth figures published for the first quarter of 2026 also show an economy driven by industry, with mining and quarrying activity up 20%.
For miners, subcontractors and communities in the country’s interior, Nyakabingo’s expansion could mean more activity, more infrastructure and more stable markets. But it also brings greater demands for safety, environmental oversight and tracking revenue flows. In a country where mining remains important to exports, transparency is an economic factor, not merely an administrative one.
The regional dimension is equally sensitive. Rwanda operates in an area where strategic minerals are often linked to political and security tensions. In the east of the Democratic Republic of the Congo, the United Nations again raised concerns in 2025 about smuggling risks and the movement of minerals from areas controlled by armed groups. In this context, Nyakabingo’s success will only be sustainable if traceability remains robust and logistics channels are free from suspicion.
A Rwandan story, but also an African one
The Nyakabingo case illustrates a broader trend: African countries are no longer only suppliers of raw materials; they are becoming potential arbiters in the reshaping of global value chains. Rwanda, already involved in the critical metals debate through tantalum and tin, and now with tungsten of direct interest to the US defence industry, is moving into an arena where economic sovereignty, mineral diplomacy and competition between powers intersect.
For East Africa, this trajectory also matters because it shows that regional integration through the East African Community can support more ambitious industrial strategies. The real question now is whether Kigali will turn this commercial advantage into a sustainable local value chain, with processing, jobs and revenue captured more effectively at home. That is what will determine the case’s continental significance, far beyond a single deposit in the Northern Province.