Algeria
 Egypt
 Libya
 Morocco
 Sudan
 Tunisia
 Benin
 Burkina Faso
 Cabo Verde
 Côte d'Ivoire
 Ghana
 Guinea
 Guinea-Bissau
 Liberia
 Mali
 Mauritania
 Niger
 Nigeria
 Senegal
 Sierra Leone
 The Gambia
 Togo
 Central African Republic
 Chad
 DR Congo
 Equatorial Guinea
 Gabon
 Republic of the Congo
 São Tomé and Príncipe
 Burundi
 Comoros
 Djibouti
 Eritrea
 Ethiopia
 Kenya
 Madagascar
 Malawi
 Mauritius
 Mozambique
 Rwanda
 Seychelles
 Somalia
 South Sudan
 Tanzania
 Uganda
 Angola
 Botswana
 Eswatini
 Lesotho
 Namibia
 South Africa
 Zambia
 Zimbabwe
When paying becomes a test of integration
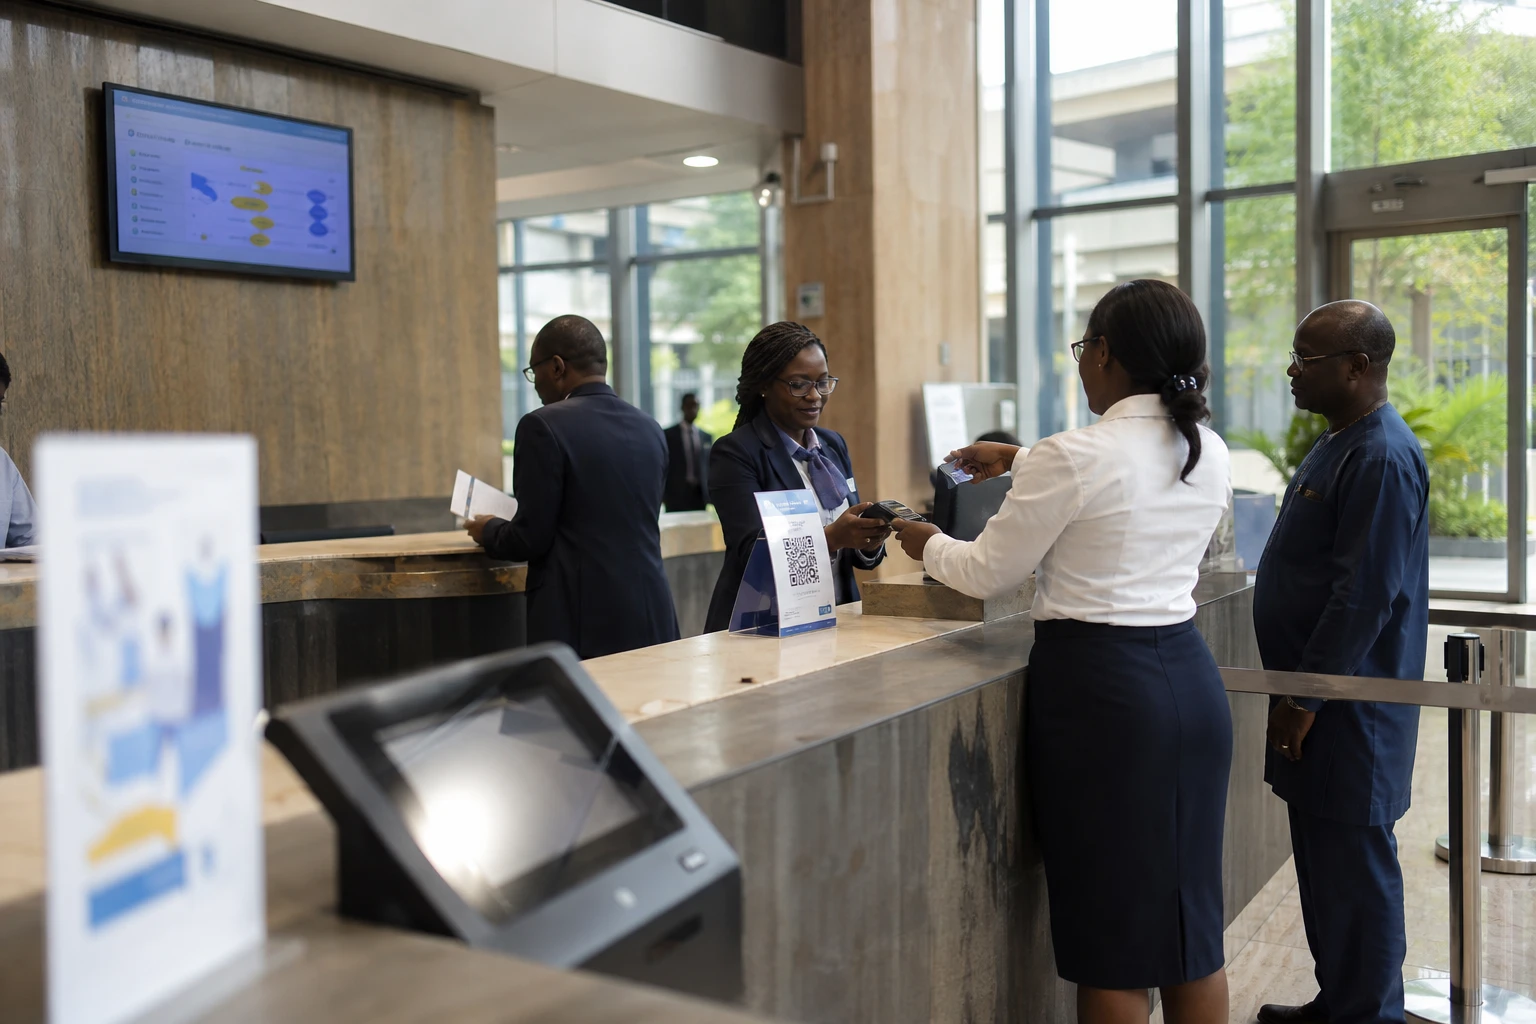
In Central Africa, a simple payment often remains more complicated than a journey between two neighbouring capitals. Fragmented payment methods between banks, microfinance institutions, e-wallets and merchants continue to hamper everyday transactions. The launch of an interoperable QR code in the CEMAC zone aims precisely to reduce this friction by establishing a common rule for actors that have not always used the same payment rails.
This project forms part of a clearly defined regional framework: CEMAC brings together Cameroon, the Central African Republic, the Republic of the Congo, Gabon, Equatorial Guinea and Chad, under the auspices of BEAC, whose headquarters are in Yaoundé. The central bank has already launched several technical payment reforms, with support from the sub-region’s adopted community framework for payment services. The community QR code extends this architecture as Central Africa seeks to make transactions faster, more transparent and less dependent on cash.
A common standard for six economies
On 8 April 2026, in N’Djamena, the Ministerial Committee of the Central African Monetary Union adopted the regulation approving the QR code standards, as well as those for the automated bill of exchange and direct debit. The text was approved alongside other monetary and prudential measures, showing that BEAC no longer treats digital payments as a mere technical tool, but as infrastructure for economic sovereignty.
On 29 July 2026, in Douala, BEAC Governor Yvon Sana Bangui officially presented the interoperable QR code intended for CEMAC’s six countries. The aim is clear: to enable a customer to pay a merchant or service provider without worrying about their bank, payment institution or e-wallet, provided they all comply with the same standard. The reform is intended less to create a new tool than to make systems that have so far operated in silos communicate with one another.
The promise is tangible. For households, it could reduce reliance on cash, particularly in cities where mobile payments are gaining ground. For small businesses, it could speed up payments and limit the costs associated with cash, input errors and settlement delays. For banks and electronic money operators, however, it means technical investment, common standards and stricter interoperability requirements. In a region where intra-community trade remains below its potential, the issue is therefore not only technological; it is also commercial and institutional.
The bridge between regional payments and the continental platform
This regional reform comes as CEMAC also connects to the continental level. On 8 July 2026, PAPSS announced BEAC’s membership of its network. PAPSS, the Pan-African Payment and Settlement System, is market infrastructure created to facilitate cross-border payments in local currencies between African countries, within the framework of the African Continental Free Trade Area (AfCFTA). The two institutions said they would work until the end of 2026 to operationalise the membership and progressively integrate CEMAC financial institutions.
The stakes are strategic. Even today, many payments between African businesses pass through intermediary currencies, often the US dollar or the euro, incurring additional costs and longer delays. PAPSS says it aims specifically to reduce this dependence by enabling direct settlement in local currencies where regulatory and technical conditions allow. From this perspective, BEAC’s QR code and membership of PAPSS are not two separate projects: together, they outline a single architecture, from local payments to cross-border settlement.
The move also carries political weight. In Central Africa, payment modernisation touches on trust in the currency, states’ ability to harmonise their rules and the role of public actors in digital infrastructure. BEAC, one of the continent’s few regional central banks, is thus signalling that its remit extends beyond monetary stability: it is also seeking to build practical bridges between national markets that remain too fragmented.
What this changes, and what to watch
For member states, the interoperable QR code could support the gradual formalisation of payments, improve transaction traceability and strengthen financial inclusion. For neighbourhood merchants, transport operators, service providers and small businesses, it could simplify payments without requiring heavy equipment. But success will depend on genuine adoption by banks, fintechs, payment networks and tax administrations, as well as the quality of support for users. A common standard only has an effect if it is widely accepted and properly connected.
The regional scope is significant, but implementation will matter even more. CEMAC has already established the regulatory framework for payment services, and BEAC has stated its intention to connect the sub-region progressively to PAPSS by the end of 2026. The most sensitive phase remains: effective interoperability between existing systems, actors’ compliance, transaction security and the ability to secure acceptance of these new practices in economies where cash remains widespread. This is when integration will cease to be a principle and become a visible part of everyday life.
At the continental level, this project joins other financial integration initiatives already under way in East, Southern and West Africa. For CEMAC, the challenge is not to remain a spectator to this reshaping. If the community QR code and PAPSS work as planned, transactions between Yaoundé, Bangui, Libreville, Brazzaville, Malabo and N’Djamena could become smoother, directly benefiting formal businesses and payment operators and, in time, the small transactions that drive the sub-region’s economic life.